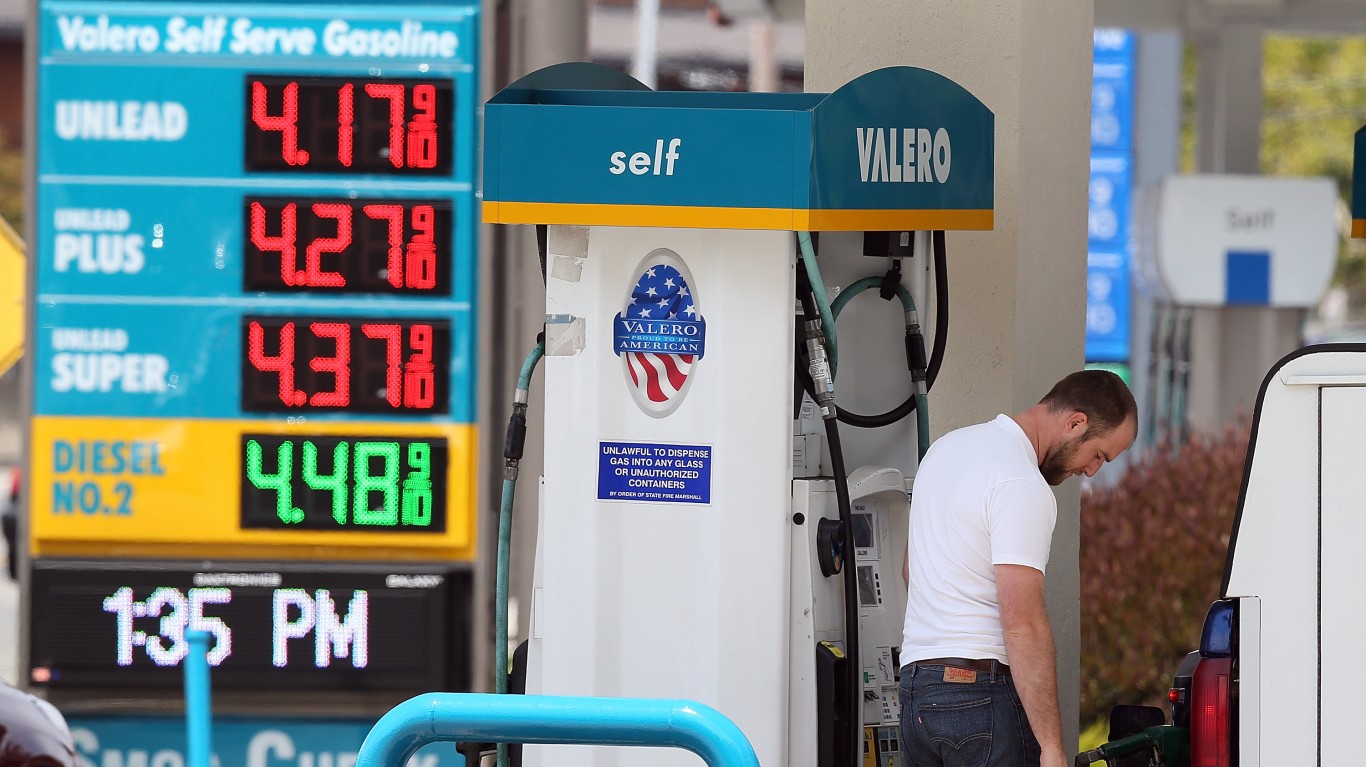Jim Cramer Says a 25% Surtax Just Got Added to Everything You Buy. Congress Never Voted on It.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
On CNBC’s Squawk on the Street in mid-September, Jim Cramer reframed a soft producer price report around a single input: diesel. He argued that America moves goods by truck, so a jump in diesel prices acts like a tax that every physical good has to carry. He put a number on it, calling it a 25% surtax that Congress never voted on and shoppers cannot opt out of, according to CNBC.
That framing landed at an awkward moment for consumer-facing equities. WTI crude was pressing toward $100 per barrel at the time, and the national average for regular gasoline had reached $4.157 per gallon on September 7. Carl Quintanilla noted on air that consumer discretionary names were down a fifth over the prior month, with restaurants leading the decline. The question for investors was whether that selloff already reflected Cramer’s surtax, or was only the opening move.
Why Diesel Is the Input That Matters
Diesel powers the trucks, and trucks touch nearly every package on a shelf. Unlike advertising or store remodels, a retailer cannot dial freight down when the fuel bill climbs. That is what gives Cramer’s 25% framing more weight than a headline inflation number.
Walmart (NASDAQ:WMT | WMT Price Prediction) quantified the pressure directly. CFO John David Rainey told analysts on the August earnings call that the company expected “more than $2 billion of incremental fuel-related costs this year above and beyond our original guidance assumptions.” He also flagged consumer psychology, noting that pump prices crossing $4 per gallon prompt households to make different spending choices.
McDonald’s (NYSE:MCD) echoed the theme from a different angle. CFO Ian Borden pointed to “continued inflationary pressures on things like food and paper and labor” and said the company pushed its 50,000-restaurant target from 2027 to 2028 because development costs kept climbing.
Cramer’s math sits above headline CPI, but it fits the operating commentary retailers were already giving. On air, he added, “we are a trucking nation… we are not a train nation.” CNBC noted crude was on an eight-day winning streak, described as about three years in the making.
Employment Cushion Cramer Doesn’t Trust
Cramer conceded the offset. He said, “Eventually it’s going to run into the consumer. It hasn’t yet because the consumer has a job and… the wages are running a little bit ahead of inflation, according to Brian Moynihan, the CEO of Bank of America.” He treated that cushion as temporary, not durable.
The sentiment data has since reinforced his skepticism. The University of Michigan Consumer Sentiment Index, which sat at 55.2 in July when the article was written, fell to 48.0 in October 2026, its lowest level in five months and 10% below where it stood a year earlier. Purchasing power concerns dominate the survey, and year-ahead inflation expectations have risen to 4.7%. From the May trough of 44.8, sentiment recovered only partially before sliding again, suggesting the wage-and-employment cushion has not been enough to restore consumer confidence against persistent energy and food costs.
The read here is that a job cushion beats a compounding energy cost only while payrolls hold. Once weekly hours slip or hiring cools, households facing $4-plus gasoline stop buying the marginal restaurant meal and trade down at the register. That is when Cramer’s surtax stops being a wholesale story and becomes an earnings story.
The 10-year Treasury yield, which was 4.83% at the time of publication, has since moved higher, touching above 5% in mid-October before settling near 4.95% in early November 2026. Higher long rates raise financing costs for retailers rebuilding supply chains and compress the multiples investors will pay for slower-growing consumer names.
What the Market Has Already Priced Into MCD, TGT, and WMT
The market shows selective damage across the three names. McDonald’s was down roughly 15% year to date at the time Cramer made his remarks, with global comparable sales growth of only 1.3% last quarter confirming the traffic problem he highlighted. By September 23, the stock had extended those losses to around 18% for the year.
That September 23 date mattered. McDonald’s held its long-awaited Investor Day in Chicago, unveiling a strategy called “McDonald’s NEXT” anchored by an $8.5 billion franchisee support commitment running through 2036. The plan set 2030 targets for operating margins in the low-to-mid 50% range and aimed to deliver roughly $100,000 in annual efficiency gains per average U.S. restaurant. Markets were unmoved by the ambition. Shares fell roughly 4% on the day to close around $238, hitting a four-year low, as investors focused on the near-term cost of the plan rather than its eventual payoff. Softer U.S. customer traffic remained the unresolved problem.
Walmart was off roughly 6% in the month before Cramer’s remarks, even after receiving approximately $2.9 billion of tariff refunds that it was reinvesting into prices. Management flagged that a large share of the reinvestment was landing in Q3, making that subsequent report the key data point.
Target (NYSE:TGT) was the standout, up more than 63% year to date at publication on a Q2 that included a $994 million pretax IEEPA tariff refund contributing $1.65 to EPS. Strip that out, and the underlying story was adjusted EPS up roughly 20% versus a year ago, per CFO Jim Lee. The full details are in Target’s Q2 8-K.
The broader context is that the XLY consumer discretionary ETF was down more than 6% in the month surrounding Cramer’s remarks, with restaurants and low-ticket retail absorbing the first round of pain. As of early November 2026, WTI crude trades near $95 per barrel, below the $100 threshold that Cramer pointed to as psychologically significant, and the national gasoline average has pulled back to around $4.16 per gallon. That retreat offers modest relief, but long-term Treasury yields remain elevated and consumer sentiment continues to track near multi-year lows.
Is MCD Stock a Buy?
McDonald’s is the cleanest way to test Cramer’s thesis, because its franchisees carry both food and freight inflation directly. The stock was trading near $253 when the original commentary aired. It then fell further through the September 23 Investor Day, landing near $238 as management’s NEXT strategy raised more questions about near-term spending than it answered about near-term traffic recovery.

The $3.38 adjusted EPS beat in the most recent quarter rode on international strength, while July U.S. comps went slightly negative. That is a fragile base heading into a prolonged diesel cost cycle.
Walmart looks better positioned given scale, food mix, and tariff-refund reinvestment. Target’s turnaround is real but partly refund-flattered. On MCD, the September 23 Investor Day did not deliver the catalyst the original thesis anticipated. The NEXT strategy sets a credible long-term path, but near-term traffic recovery depends on inflation easing and consumer sentiment rebuilding, two conditions that remain well short of fulfilled.
Editor’s note: This update adds post-publication context from McDonald’s September 23, 2026 Investor Day, including the company’s $8.5 billion franchisee support plan and the stock’s roughly 4% selloff to a four-year low on the day. Consumer sentiment figures have been refreshed to the final October 2026 University of Michigan reading of 48.0, down from the article’s July figure of 55.2, and the 10-year Treasury yield has been updated to reflect the early-November 2026 level near 4.95%, up from the 4.83% cited at publication.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.