Forget Nvidia. Apple Could Be the AI Stock to Watch Next.
Everyone knows Nvidia owns the AI trade, but a quieter giant with 2.5 billion active devices is building a monetization machine that could rewrite that assumption entirely.


Apple (NASDAQ:AAPL | AAPL Price Prediction) has quietly become one of the year’s better AI trades. Shares are up 22.56% YTD and 44.98% over the past year, powered by a reimagined Siri, an M5 silicon refresh, and a Services engine that keeps compounding.
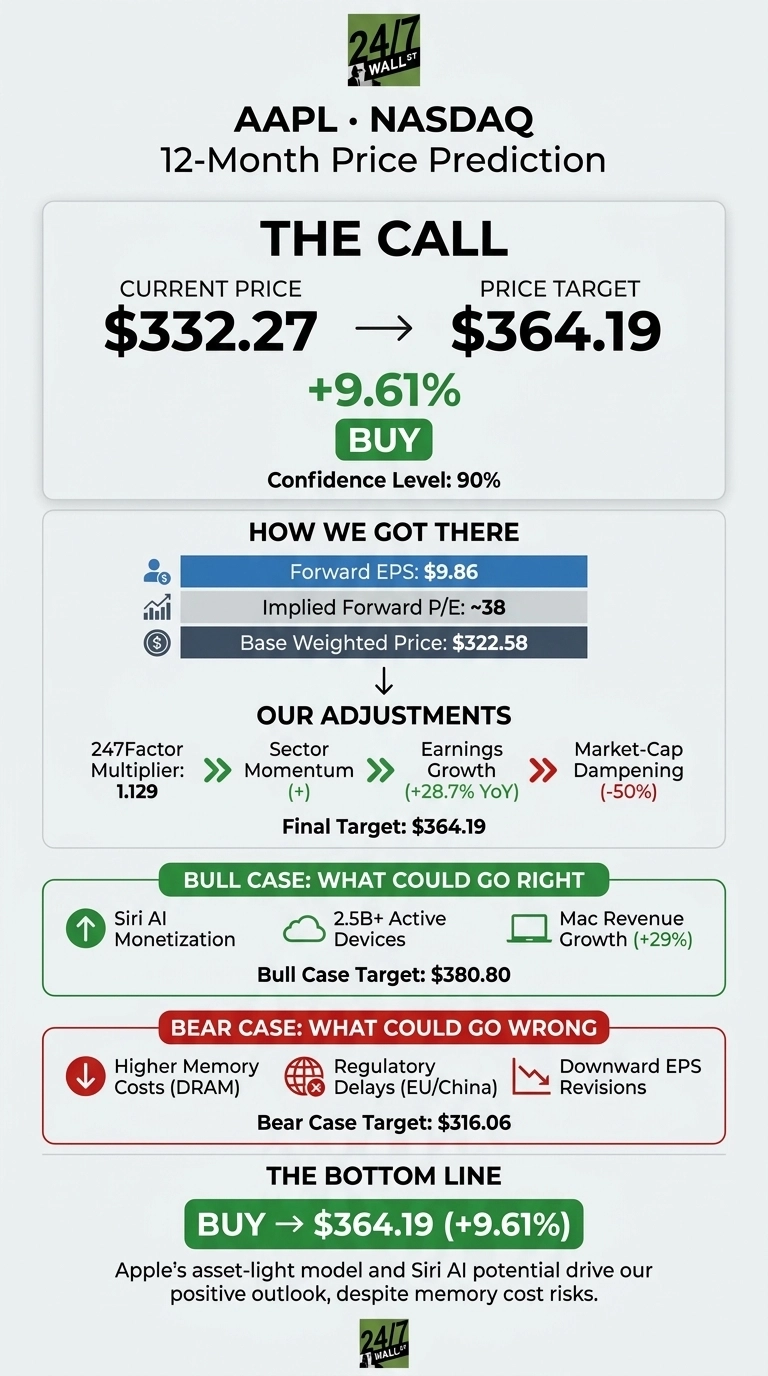
Our 24/7 Wall St. price target for Apple is $364.19 over the next 12 months, implying 9.61% upside from $332.27. Our recommendation is buy, with a 90% confidence rating.
| Metric | Value |
|---|---|
| Current Price | $332.27 |
| 24/7 Wall St. Price Target | $364.19 |
| Upside | 9.61% |
| Recommendation | BUY |
| Confidence Level | 90% |

Why Apple Just Had Its Best AI Quarter Yet
Apple’s Q3 FY2026 earnings report was the setup for the current rally. Revenue hit $109.42 billion, up 16.4% YoY, with iPhone at $54.25 billion and Services at a record $30.74 billion. EPS of $2.02 beat by 6.80%, the ninth straight beat.

Shares have climbed 9.93% in the past month alone, sitting roughly 6% off the 52-week high of $344.27. CNBC’s Josh Brown recently flagged Apple’s chart as giving a “classic tell”, and the stock has agreed: shares closed at $332.27 after a 1.75% single-day pop.
Why Bulls See Siri AI Breaking the Model
The bull thesis is simple: Apple owns the distribution. With 2.5 billion active devices, even modest AI monetization moves the needle. CEO Tim Cook told investors Apple is “off the charts excited about Siri AI” and confirmed “upgrade possibilities on iCloud Plus” as a monetization path.
Mac revenue grew 29% as enterprises deploy Apple Silicon for on-device inference. If Siri AI drives an accelerated iPhone upgrade cycle heading into holiday, our bull-case $380.80 is achievable. FY2027 consensus EPS sits at $9.57, with the high end at $10.67.

What Could Send Apple Back to $316
The Q3 gross margin of 50.1% included a 2pp one-time tariff refund benefit that will not recur. Memory costs are the bigger overhang. Cook warned “For September, we expect to pay even higher memory costs” and that DRAM pricing could keep rising. Regulatory delays in the EU and China are pushing Siri AI’s global rollout past the initial timeline.
Insider activity is neutral, and FY2027 EPS estimates have seen 24 downward revisions in the past 30 days. Bulls counter that the memory pressure reflects unprecedented iPhone and Mac demand, which Cook called “an incredibly strong iPhone and Mac product cycle“. A bear-case fade takes shares back to $316.06.
How Apple Compares to Microsoft and Alphabet
Microsoft (NASDAQ:MSFT) is the natural AI comp. Azure just crossed $100 billion in annual revenue with Q4 growth of 43%, and Microsoft trades at a P/E of 28. That is a full turn cheaper than Apple on earnings, but Microsoft’s $115.95 billion capex is compressing free cash flow.
Alphabet (NASDAQ:GOOGL) is the value play, trading at a P/E of just 15, with Google Cloud growing 82% in Q2. Both peers spend far more on AI infrastructure than Apple does, which is precisely the point. Apple’s asset-light model produces 171.4% ROE and 32.0% operating margins. On earnings multiple alone, Apple looks expensive. On capital efficiency, our target looks reasonable.
| Company | P/E | Operating Margin |
|---|---|---|
| Apple | 43 | 32.0% |
| Microsoft | 28 | 46.8% |
| Alphabet | 15 | 32.0% |
Buy Rating at 90% Confidence
The 24/7 Wall St. price target of $364.19 earns a buy at 90% confidence. The tipping factor is Siri AI, which converts Apple’s 2.5 billion-device install base into a recurring revenue lever without requiring hyperscaler-level capex.
The thesis strengthens if the December quarter confirms Services growth staying in double digits. The thesis weakens if memory costs erase more than 200 basis points of gross margin next quarter.

| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $338.02 |
| 2027 | $378.04 |
| 2028 | $396.74 |
| 2029 | $416.98 |
| 2030 | $456.58 |
These projections assume Apple executes on Siri AI monetization and Services continues its double-digit trajectory. Significant upside or downside could come from a foldable iPhone launch or sustained DRAM price inflation.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.