Apple Just Became Wall Street’s Favorite Mag 7 Stock for a Surprising Reason
While Alphabet and Microsoft burn through hundreds of billions on AI infrastructure, one Magnificent 7 giant is hitting fresh highs by doing the opposite, and Wall Street is starting to notice why that matters.

Apple has quietly done something none of its Magnificent 7 peers have managed in 2026. It has become the AI winner that spends the least on AI. While Alphabet plans $175 billion to $185 billion in 2026 capex and Microsoft just posted $115.95 billion in full-year capital spending, Apple is riding a 22% iPhone cycle, a reimagined Siri, and a memory-cost story into fresh highs.
Our 24/7 Wall St. price target for Apple (NASDAQ: AAPL | AAPL Price Prediction) is $361.66 over the next 12 months, implying 16.91% upside from $309.35. Our confidence is high.
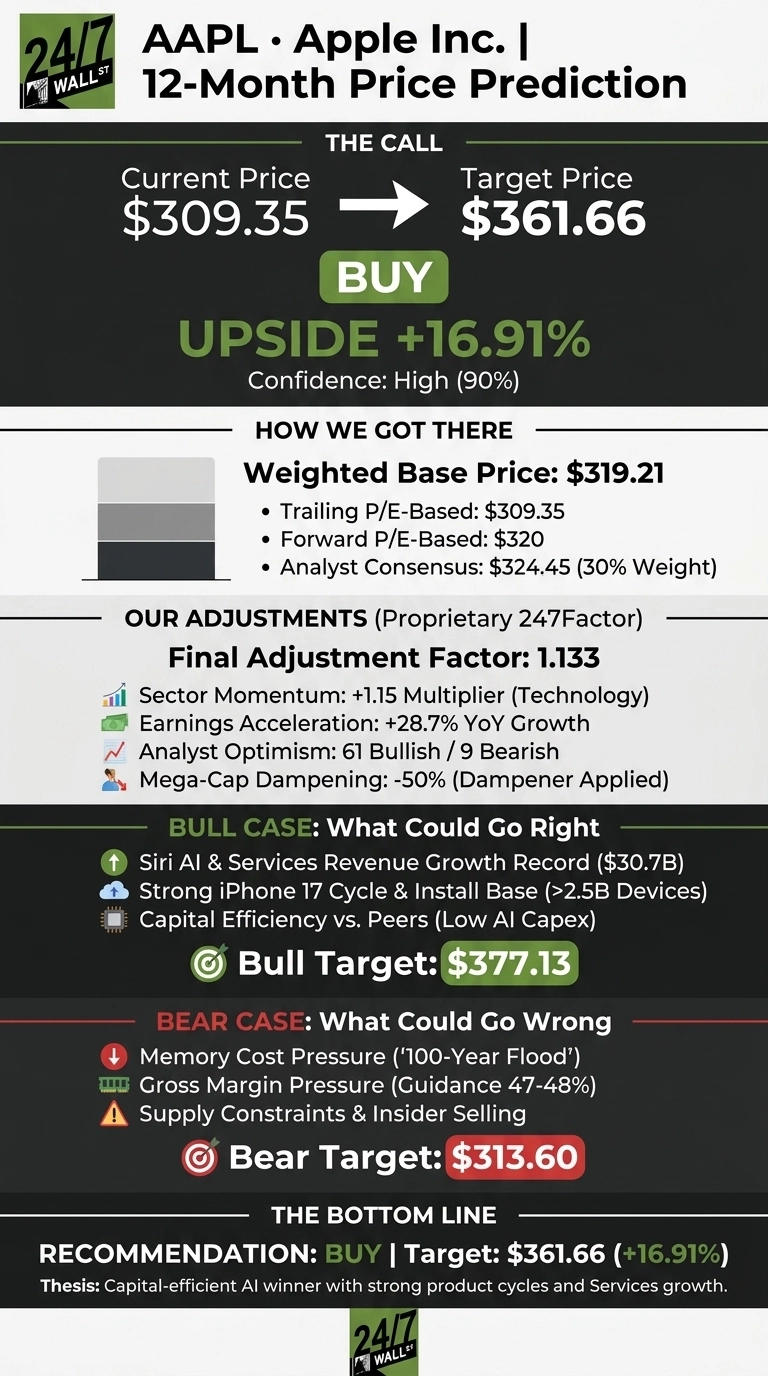
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $309.35 |
| 24/7 Wall St. Price Target | $361.66 |
| Upside | 16.91% |
| Recommendation | BUY |
| Confidence Level | 90% |

How the Capex-Light Narrative Took Over
Apple stock has returned 38.06% over the last year and 14.1% year to date, though shares have cooled 4.99% in the last month after tagging a 52-week high of $344.27.
The July 30 fiscal Q3 print was the catalyst. Revenue of $109.4 billion grew 16.36%, EPS of $2.02 beat estimates by 6.8%, and iPhone revenue jumped 22% to $54.3 billion. That marked Apple’s ninth consecutive EPS beat. A viral Reddit post captured the shift, noting “Apple’s capex is 1.8% of revenue, Alphabet’s is 37.5%”. Investors are re-rating Apple as the AI beneficiary without the balance-sheet risk.

Why Bulls See a Breakout to $377
Tim Cook called Siri AI “a completely reimagined version of Siri that is profoundly capable, deeply personal, and integrated seamlessly across our platforms.” He added, “I have never been more optimistic.”
The install base topped 2.5 billion devices, Services hit a record $30.7 billion, and Apple committed $600 billion to U.S. investment plus a $30 billion Broadcom (NASDAQ:AVGO) silicon deal. Prediction-market traders now price 85% odds on a foldable iPhone before 2027. Our bull-case scenario points to $377.13, roughly 22% upside.

What Could Go Wrong
Memory costs are the sharpest risk. Cook described DRAM pricing as “a 100-year flood on the memory pricing with exponential increases”.
September-quarter gross margin guidance of 47% to 48% is well below Q3’s 50.1%, and Q3 included a one-time tariff-refund tailwind worth roughly $0.11 of EPS. Insider activity has skewed net selling. That said, bulls would counter that supply constraints reflect “an incredibly strong iPhone and Mac product cycle“, not weakness. Our bear-case scenario lands at $313.60.
How Apple Compares to Microsoft and Alphabet
Apple trades at a P/E of 40, well above Microsoft (NASDAQ: MSFT) at 27. Microsoft posted 17.8% revenue growth with Azure at 43%, but its $115.95 billion capex bill is the exact overhang Apple avoids.
Alphabet (NASDAQ: GOOGL) grew Q2 revenue 24.2% with Google Cloud up 82%, yet posted negative free cash flow of $5.85 billion because of AI capex.
All of that spending has to land somewhere, which is the whole reason we mapped the power, cooling, and networking suppliers behind the buildout in a free AI infrastructure report. Apple’s ROE of 171.42% and free-cash-flow yield of 2.19% justify the premium. The peer group makes our 24/7 Wall St. price target look reasonable.

Apple Price Prediction 2026-2030
My verdict is buy at a 24/7 Wall St. price target of $361.66 with 90% confidence. The key factor is capital efficiency in an AI cycle where peers are drowning in capex.
Conviction strengthens if Siri AI adoption translates into a measurable Services acceleration by the December quarter. I would stay on the sidelines if September gross margin lands below the 47% low end of guidance.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $325 |
| 2027 | $362 |
| 2028 | $405 |
| 2029 | $455 |
| 2030 | $508 |
These projections assume Apple monetizes Siri AI through iCloud+ and defends Services growth. Significant upside could come from a foldable iPhone launch or a China rebound. Downside could stem from a prolonged DRAM shortage or regulatory action on the App Store.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.