Joby Slips and Is Down 53% This Year as the eVTOL Trade Keeps Unwinding; Archer Dips, EHang Eases
The eVTOL sector keeps bleeding out, and Joby, Archer, and EHang are all hovering near 52-week lows with no single catalyst to blame. What happens next depends on a certification outcome that could either reprice the entire thesis overnight or…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
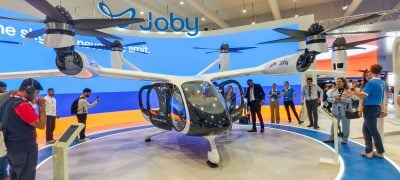
Shares of Joby Aviation (NYSE:JOBY | JOBY Price Prediction) are down 2% to $6.18 in midday Tuesday trading, extending a slide that leaves Joby stock down 53% year to date (YTD). The broader market is softer today too, but nowhere near this pace, with the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) down 0.5% to $757.14.
Archer Aviation (NYSE:ACHR) stock is also easing, down 2% to $5.38, with Archer now down 28% YTD and trading below its 50-day moving average of $5.47. Meanwhile, EHang Holdings (NASDAQ:EH) stock is down 1% to $4.45, and EHang is the worst performer of the group as it’s down 66% YTD.
Joby, Archer, and EHang all build electric vertical takeoff and landing (eVTOL) aircraft, and Tuesday’s session reads more like continued drift out of a theme that’s been unwinding for months than a fresh shock. Each name sits close to its 52-week low, with Joby’s low at $6.18, Archer’s at $4.30, and EHang’s at $4.345.
Continued Sector Drift
No announcement from Joby, Archer, or EHang accounts for today’s declines. All three are pre-revenue or early-revenue aircraft developers whose value rests on certification timelines and future commercial service rather than on current results, which makes them unusually sensitive to the cost of capital and to investor patience.
The recent overhang on EHang is more concrete. EHang withdrew its full-year 2026 revenue guidance of RMB600 million after a late-June piloted light-sport aircraft accident in China led regulators to slow low-altitude aviation approvals, and the Pomerantz law firm issued an investigation notice on EHang on September 3.
Joby and Archer have leaned into different narratives to defend their names. Archer has bolted on defense exposure through the Halo and Thunder platforms and the pending Wisk, Insitu and SkyGrid acquisition from Boeing (NYSE:BA), while Joby has emphasized certification progress and the Blade passenger business as a way to book revenue before the core air taxi service launches.
Certification Timing and Cash Burn
Joby’s August 5 quarterly release showed Q2 2026 revenue of $38.64 million against a $30.38 million consensus, but the core eVTOL air taxi business is still pre-revenue and Blade contributed $36.2 million of the top line. Joby guided second-half 2026 cash usage of $385 million to $415 million against $629.861 million in cash, and reported FAA type-certification progress at 83%/77% on Stage 3 and 20%/10% on Stage 4.
Archer widened its Q2 net loss to $263.2 million, held $1.56 billion in liquidity, and announced a deal to acquire Boeing’s Wisk Aero, Insitu, and SkyGrid businesses in exchange for a strategic Boeing equity stake. Insitu alone is expected to add more than $200 million in annual revenue once the transaction closes by year-end, and Archer’s Q3 2026 adjusted EBITDA is guided to a loss of $170 million to $200 million.
EHang delivered only 36 eVTOL units in Q2 2026 versus 52 a year earlier, and posted revenue of $11.56 million, down 46.6% year over year (YoY). EHang authorized a $30 million ADS repurchase program in June, but the withdrawn guidance has been the more consequential number, and EHang’s 50-day moving average of $5.21 now sits well below its 200-day average of $9.72.
What to Watch Next
Joby’s first eIPP flights are targeted for Dallas-Fort Worth in September, and the company is still aiming to carry its first paying passengers this year. The average analyst price target on Joby sits at $10.68, well above the current quote, and Archer and EHang carry comparable targets of $10.61 and $10.19 respectively, so the sell-side view across the group still assumes commercialization actually lands on time.

For Joby, the bull case is that certification is binary and a single approval reprices the whole thesis. The bear side argues that each quarter without eVTOL revenue makes the next capital raise more expensive for shareholders already in the name.
Investors can watch for whether the Dallas-Fort Worth eIPP demonstrations convert to paid service before year-end, and should keep their exposure to pre-revenue eVTOL names small enough that a delayed certification doesn’t wreck the plan (we wrote a free playbook on speculating with just 5% of a portfolio here: Small Stakes, Big Swings).
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk.His work has appeared in The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, TalkMarkets, Finmasters, 24/7 Wall St., and others.With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.