The AI Boom Has a Secret Weapon, and It’s Marvell
Marvell has surged over 150% this year on the back of explosive data center growth, but Wall Street's consensus target may still be too conservative. Here is why analysts keep chasing the numbers, and what it would take to push…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) has quietly become one of the most important names in the AI infrastructure buildout. Data center revenue hit $2.17 billion last quarter, up 46% year-over-year, and now represents 79% of total revenue.
Shares are up 156.98% year-to-date and trade at $218.07. Can this stock reach $400 in 2027?

What’s Holding Marvell Back Right Now
After a strong run, MRVL has cooled. Shares are down 2.45% over the past week and essentially flat over the past month at 0.46%, with a 7.64% single-session drop today. A beta of 2.25 means MRVL trades like a leveraged call on AI sentiment.
Coverage from CNBC and Barron’s grouped Marvell into a broad chip-sector reset alongside Intel, AMD, and Oracle. Digestion after a 156% run explains the pause. Concerns about customer concentration and hyperscalers building silicon in-house also weigh on the multiple.
Wall Street Sees 30% Upside. Our Model Says More
The Street is bullish. The consensus target sits at $284.64, with 8 strong buys, 31 buys, 5 holds, and zero sell ratings. That is 89% bullish coverage. Our internal base case lands at $301.49, implying 27.7% upside, and our bull scenario reaches $355.82.
Analysts are anchored to fiscal 2027 EPS of $4.2011, but fiscal 2028 estimates have ripped from $6.1726 ninety days ago to $6.7209 today. Consensus is chasing the numbers rather than leading them. That is where targets get raised repeatedly.
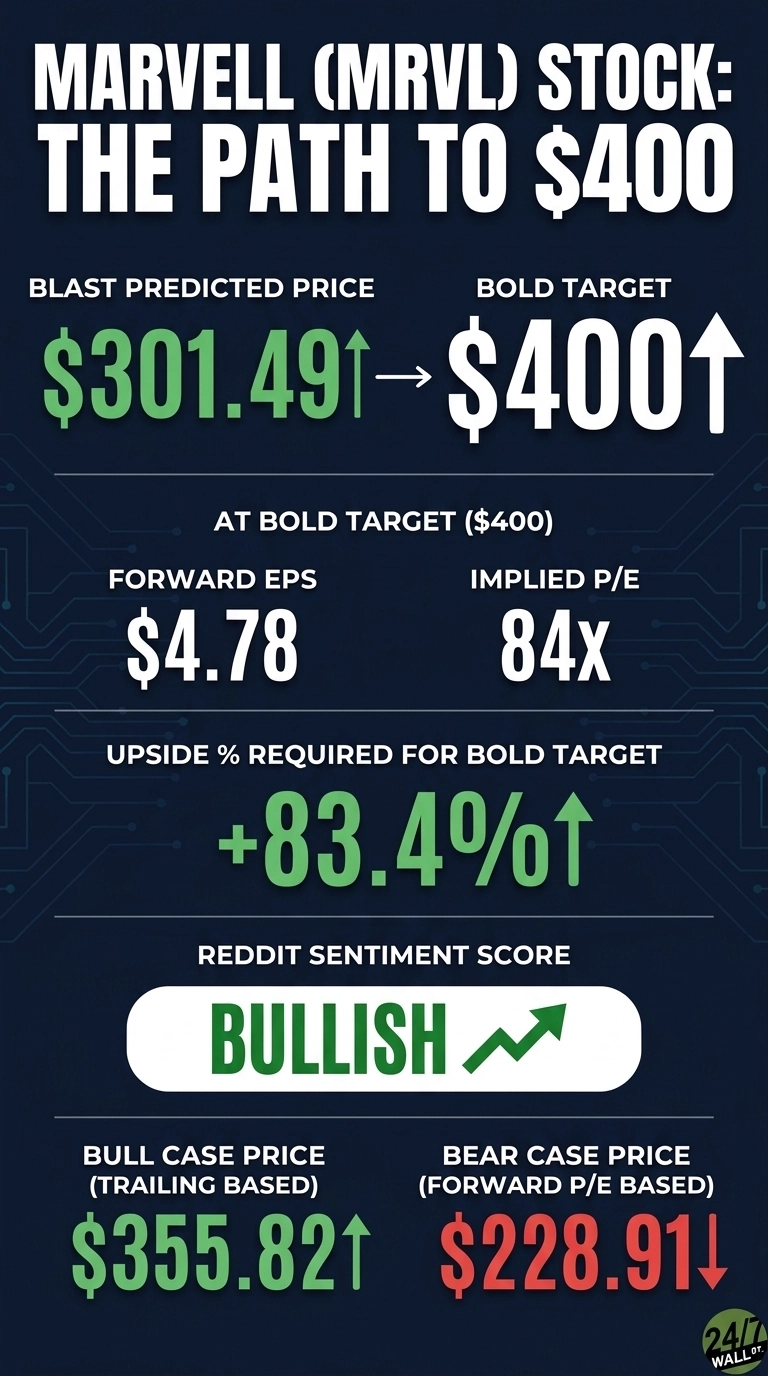

Path to $400 Per Share
Reaching $400 from today’s price of $218.07 would require an 83.4% gain. With forward EPS of $4.78, a price of $400 implies a forward P/E of 84x. Our base case of $301.49 implies 72x, meaning the bold target requires roughly 12x of additional multiple expansion.
That is aggressive but not absurd for a company where CEO Matt Murphy told investors, “AI-related bookings remain exceptionally robust, and we expect our revenue growth to accelerate further through the remainder of fiscal 2027.”
Management raised the fiscal 2027 revenue outlook to roughly $12 billion, expects fiscal 2028 data center revenue to grow more than 60%, and said custom silicon will “over-double” next year.
The expanded Google agreement validates the custom XPU thesis. Add scale-up optics that Marvell called a “massive new TAM”, and the multiple compression story writes itself as EPS climbs toward the $6.72 fiscal 2028 consensus. The biggest risk is hyperscalers bringing more silicon design in-house.

Where Marvell Trades Today vs. Its Earnings Power
At $218.07, shares trade at roughly 46x forward EPS of $4.78. For a business growing data center revenue 46% year-over-year with non-GAAP operating margin heading toward the 38% to 40% long-term target range in Q4, that multiple is defensible.
Shares sit below the 52-week high of $329.80 and above the 52-week low of $66.19. MRVL has returned 1,784.9% over ten years. This stock rewards patience when the thesis holds.
Is $400 Realistic?
Reaching $400 from $218.07 requires an 83.4% gain. It is a stretch.
But three things could get us there: fiscal 2028 EPS estimates continuing to rise on custom silicon ramps, the Google warrant translating into visible design win momentum ahead of the October 6, 2026 Investor Day, and scale-up optics revenue exceeding management’s outlook.
A hyperscaler capex reset would derail it fast. We’ve outlined the blueprint for how Marvell Technology could reach $400 in 2027 (and we reverse-engineered what the biggest tech winners looked like early on in a free playbook you can grab here).
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.