The AI Stock I’m Buying on Repeat (And It Isn’t Nvidia)
Everyone talks about one AI chip company, but a quieter rival is printing cash, slashing debt, and locking in the hyperscalers designing around it, and the recent pullback just made the case stronger.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
I keep hitting the buy button on Broadcom (NASDAQ:AVGO | AVGO Price Prediction), and September’s pullback just handed me another reason to do it again. The stock is down 12.28% over the past month and essentially flat year to date at $344.72, while the business underneath it just posted the quarter of a lifetime. That gap is where my conviction lives.
Why I Keep Adding at These Prices
My thesis is simple. Broadcom is quietly becoming the plumber for the AI build-out that everyone else rents from a single GPU vendor. When a hyperscaler decides its own workloads deserve their own silicon, they call Hock Tan. Custom accelerators are a different business than merchant GPUs, and I want to own it for the next decade.
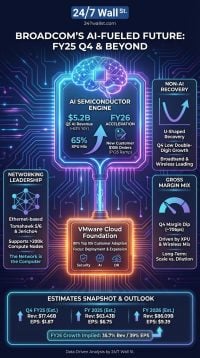
The Q3 FY2026 numbers make the case without me embellishing anything. Revenue landed at $29.59 billion, up 85.5% year-over-year. AI semiconductor revenue alone hit $16.70 billion, up 221% YoY and 54% sequentially. Free cash flow was $13.66 billion, or 46% of revenue. Operating income jumped 171.02% YoY. Those are cash generation numbers I structure a retirement position around.
Second, the balance sheet moved the right way. Cash rose to $23.98 billion, up 123.69% YoY, while total liabilities dropped 4.21% YoY. Management repaid $5.6 billion of long-term debt in the quarter and another $1.5 billion after quarter end. Deleveraging while free cash flow nearly doubles is the combination I want.
Third, the dividend keeps compounding. The quarterly payout sits at $0.65, following a 10% raise that marked the 15th consecutive annual dividend increase since fiscal 2011. My yield-on-cost climbs every year I hold.
Passing on Nvidia, Again
The obvious alternative is NVIDIA (NASDAQ:NVDA), and I own some. I keep adding to Broadcom instead for two verifiable reasons. First, income. Broadcom pays a forward annualized dividend of $2.60 per share behind a 15-year raise streak, a profile Nvidia does not meaningfully match. Second, valuation on forward earnings. Broadcom trades at a forward P/E of roughly 19 with a PEG of 0.358. Broadcom is also the pick-and-shovel play on Nvidia’s own customers designing around it: Google, OpenAI, Meta and Anthropic are all named Broadcom XPU customers, with the Anthropic-plus-OpenAI financing platform targeting 20 gigawatts of compute by the end of 2028.
Risk I Take Seriously
Customer concentration is real. Tan said it plainly: “we have only six customers to deal with.” If one delays a program or in-sources further, the AI revenue curve bends. I hold the position anyway because the FY2027 AI outlook of approximately $115 billion and FY2028 outlook of $230 billion come with management saying supply is already secured, and the Infrastructure Software segment, up 29% YoY to $8.75 billion at a 94% gross margin, cushions any single-customer shock.
What Keeps the Buy Button Live
Tan told the September call, “Q3 demand was simply hot and we’re just getting started.” Management is guiding to over $30 in earnings per share in fiscal 2028. At today’s price, that math is why my next contribution goes to the same ticker it went to last month, and the month before that. (The traits that showed up in the biggest tech winners years before their runs are the ones we cataloged in a free playbook here: The Next Nvidia Playbook.)
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.