Here’s Why I’m Buying More Broadcom as Spiking Treasury Yields Rock AI Stocks

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

I keep hitting the buy button on Broadcom (NASDAQ:AVGO | AVGO Price Prediction), and last week’s selloff handed me another reason to do it. When the 10-year Treasury yield ripped to 4.75% on July 31 and dragged AI names lower, AVGO fell 12.87% in a single week. I added again.
Here is what pulls me back. Broadcom designs the custom ASICs that hyperscalers like Alphabet (NASDAQ:GOOGL), Meta Platforms (NASDAQ:META), and OpenAI are locking into multi-year contracts to run their AI clusters. When borrowing costs climb, hyperscalers get pickier about capex, and pickier hyperscalers pick cheaper silicon over general-purpose GPUs. That is Broadcom’s edge, and rising Treasury yields sharpen it.
Data That Keeps Me Adding
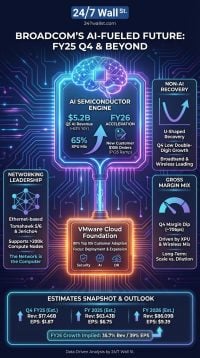
Start with the AI ramp. Q2 FY2026 AI semiconductor revenue reached $10.80 billion, up 143% year-over-year. Management guided Q3 AI revenue to $16.0 billion, over 200% year-over-year, and reiterated a fiscal 2027 target of “in excess of $100 billion”. Q2 AI bookings alone were over $30 billion against $10.8 billion shipped, with Hock Tan saying visibility now extends to 2028. That pipeline sits on signed contracts, including a 3 gigawatt Meta MTIA commitment through 2028 and a 10 gigawatt OpenAI deployment by 2029.
Second, the profitability is already here. Q2 operating income hit $10.788 billion, up 85.07% year-over-year. Free cash flow was $10.262 billion, or 46% of revenue. Adjusted EBITDA margin landed at 69% of revenue. Cash on the balance sheet more than doubled year-over-year to $19.628 billion. Fiscal 2025 threw off $26.914 billion in free cash flow.
Third, capital returns. Broadcom has raised its dividend for 15 consecutive years since fiscal 2011. The current quarterly payout is $0.65, and the company paid $3.1 billion in Q2 dividends. Management also authorized a $10 billion buyback through December 31, 2026, with $7.8 billion used in Q1 and another $600 million in Q2.
Why AVGO, Not Nvidia
NVIDIA (NASDAQ:NVDA) is the reflex pick, and I own some. My money keeps landing here because Broadcom trades at a forward P/E of 20x, a rare multiple for a business guiding AI revenue growth over 200% next quarter. Broadcom pairs that with a 15-year dividend increase streak that Nvidia’s token payout cannot match, plus the analyst target sits at $527.88. As for the Treasury bonds many retirees are reaching for, 4.65% is fair income, and it caps at 4.65%. Broadcom is compounding free cash flow at 60.07% year-over-year.
Risk I’m Watching
Customer concentration. A handful of hyperscalers drive the AI ramp. If Google, Meta, or OpenAI slow orders or shift to fully internal designs, the guidance breaks. Broadcom also carries $91.467 billion in total liabilities from the VMware deal, and higher rates make servicing that debt costlier. What blunts the risk for me is booking visibility through 2028, the gigawatt-scale contractual commitments already logged, and the fact that shareholders’ equity climbed to $87.691 billion while total liabilities actually declined 3.76% year-over-year.
Forward Conviction I Keep Acting On
Rate fear is compressing growth multiples, and AVGO now sits at $364.03, well below its 52-week high of $494.18. Full-year FY2026 AI revenue is guided to $56 billion, with the path to over $100 billion in FY2027 already backed by customer commitments. When the market marks down a business generating $26.914 billion in annual free cash flow with a 15-year dividend growth streak because the 10-year moved 5 basis points, I do not sit on my hands. I buy more.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.