Up 315% In 12 Months, This is Where Intel Will Trade in 2027
Intel has shocked the market with a historic run, but the real debate is whether the forces driving that surge can push shares to a level most analysts refuse to put in their models.

Intel (NASDAQ:INTC | INTC Price Prediction) has been the comeback story of the year. Shares are up 161.2% year to date and 291.64% over the last 12 months, powered by a full-throated pivot to AI-era CPUs, a working 18A node, and a foundry business that is finally showing signs of life.
CEO Lip-Bu Tan just delivered the seventh consecutive quarter of exceeding financial expectations. So the question I want to answer is simple. Can INTC go from roughly $96 to $150 by 2027?
What’s Holding Intel Back Right Now
The rocket ship has cooled. INTC is down 4.52% over the past month and up just 0.61% in the last week, with a brutal 6.37% premarket drop on the most recent session.
Three overhangs explain the pause. First, dilution fears from the proposed $15 billion common stock offering announced in August.
Second, Intel Foundry still posted a $2.1 billion operating loss last quarter, and management warned 2027 capital expenditures will run significantly above 2026 levels, which already sit at more than $20 billion.
Third, this is a volatile name. Beta sits at 2.231, meaning every macro wobble hits INTC twice as hard.
Wall Street Sees 20% Upside. My Read Is Bigger
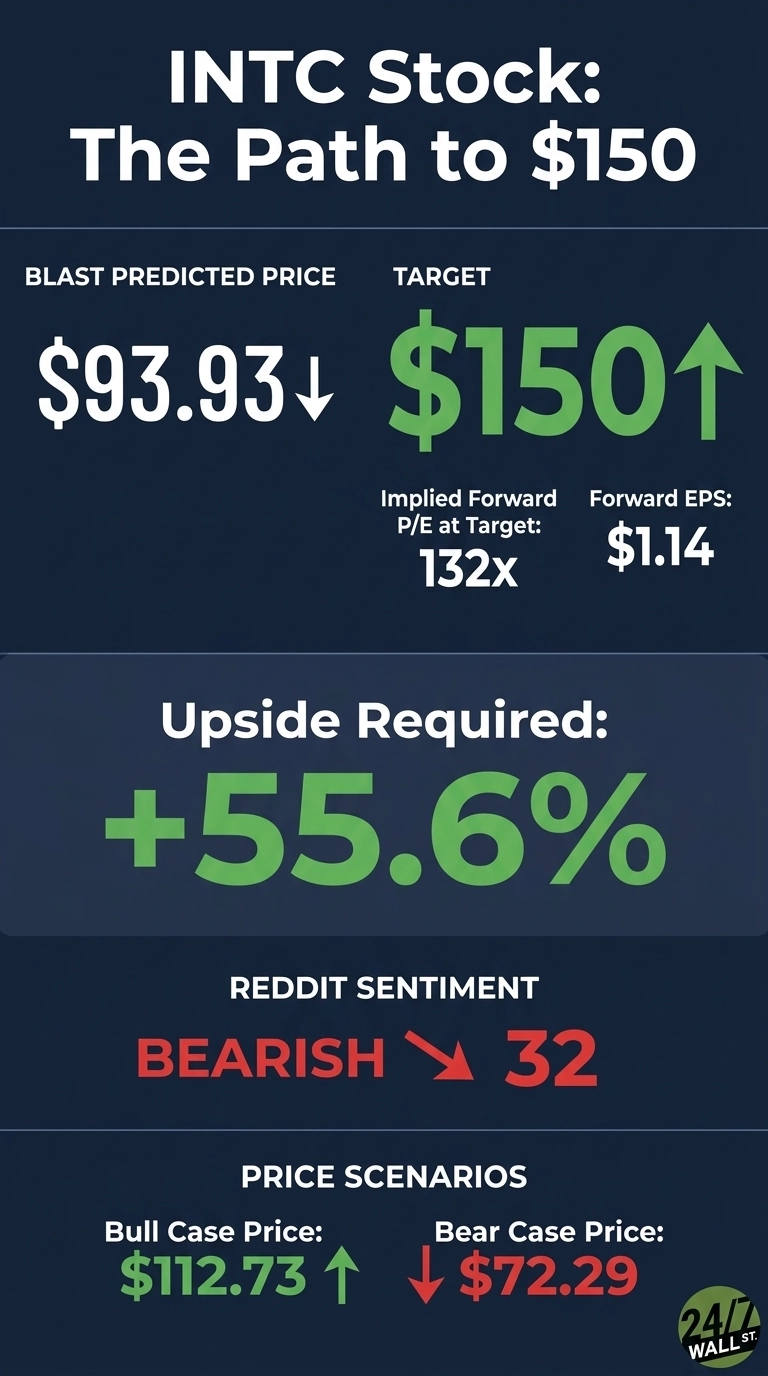
Consensus is cautious. The average analyst target is $115.74, implying roughly 20.1% upside. The ratings breakdown shows 1 Strong Buy, 13 Buys, 32 Holds, 1 Sell, and 1 Strong Sell. Our own model is even more subdued, projecting a base case of $93.93 with a bull scenario of $112.73 and a bear of $72.29, at high confidence.
I think both views are anchored to trailing losses. Only 29% of analysts are bullish, yet the FY2027 EPS consensus has climbed from $1.5167 ninety days ago to $2.0422 today. When estimates move that fast, targets usually follow.

Path to $150 Per Share
Reaching $150 from today’s price of $96.38 would require a gain of 55.6%. With forward EPS of $1.14, a price of $150 implies a forward P/E of 132x. Our base case of $93.93 already implies 94x, meaning the bold target requires 37x of additional multiple expansion. Rich, until you factor in the trajectory of that EPS number.
Consensus 2027 EPS could easily print above the high estimate of $3.4400 if Foundry breakeven arrives on schedule and Xeon 6 keeps its momentum.
Tan told investors, “AI is driving unprecedented demand for compute, and as we continue to execute, Intel is well-positioned to capture sustainable growth across our CPU franchise, ASICs, advanced packaging and vast wafer foundry network.”
Q2 delivered the strongest revenue growth in 15+ years, DCAI grew 59% year-over-year, and 18A output tracked roughly 25% above target. Adjustment factor sits at 1.087, reflecting technology sector momentum.
The biggest risk: an Intel 14A pause if no external foundry customer signs.
Where Intel Trades Today vs Its Earnings Power
At $96.38 against $1.14 forward EPS, INTC currently trades at roughly 85x forward earnings. Rich on the surface, but sensible if 2027 EPS lands anywhere near the $2.0422 consensus, which would collapse the multiple back toward 47x.
Shares sit closer to the top of a wild 52-week range of $24.22 to $142.35. Zoom out further and the 10-year return is 233.93%. The valuation case for $150 rests entirely on earnings racing to catch the multiple.

$150 Is a Stretch, But Here’s Why It’s Possible
Reaching $150 in 2027 requires that 55.6% gain from here. My verdict: a stretch, but not a fantasy.
Three things need to break right. Xeon 6 and Clearwater Forest must extend the strongest server growth on record. Intel Foundry needs to narrow that $2.1 billion quarterly loss and land an external 14A anchor customer. And FY27 EPS must push toward the $3.44 high estimate.
A capex overrun without matching backlog would derail the entire thesis. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Intel could reach $150 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.