Prediction: Intel Could Be the Tech Comeback Story of the Decade
Intel just posted its strongest revenue growth in over 15 years, and shares have already tripled. The question now is whether the forces driving this turnaround are powerful enough to push the stock another 46% higher by 2027.

Intel (NASDAQ:INTC | INTC Price Prediction) just delivered what CEO Lip-Bu Tan called “the strongest revenue growth in more than 15 years”, with Q2 2026 revenue of $16.128 billion and Data Center and AI revenue rocketing 59% year over year.
Shares have followed, up 318.29% over the past year to $102.94. Now comes the harder question. Can Intel push through $150 by 2027 and cement its status as the tech comeback story of the decade? I think there is a path. It requires several things to keep breaking right.

Why Intel Shares Could Stall From Here
The run has been staggering, but momentum is cooling. Intel is up just 1.97% over the past month even after a 7.45% weekly bounce. News sentiment sits at a constructive 63.32, yet the broader composite has slid, with a 7-day change of -18.8.
Two very real overhangs explain the pause. Intel Foundry is still bleeding, posting a $2.1 billion operating loss in Q2, and the Q2 GAAP net loss reached $11.033 billion because of a $12.53 billion non-cash CHIPS Act escrow charge. With a beta of 2.231, this stock swings hard in both directions.
Wall Street Sees Modest Upside. Our Model Is More Cautious
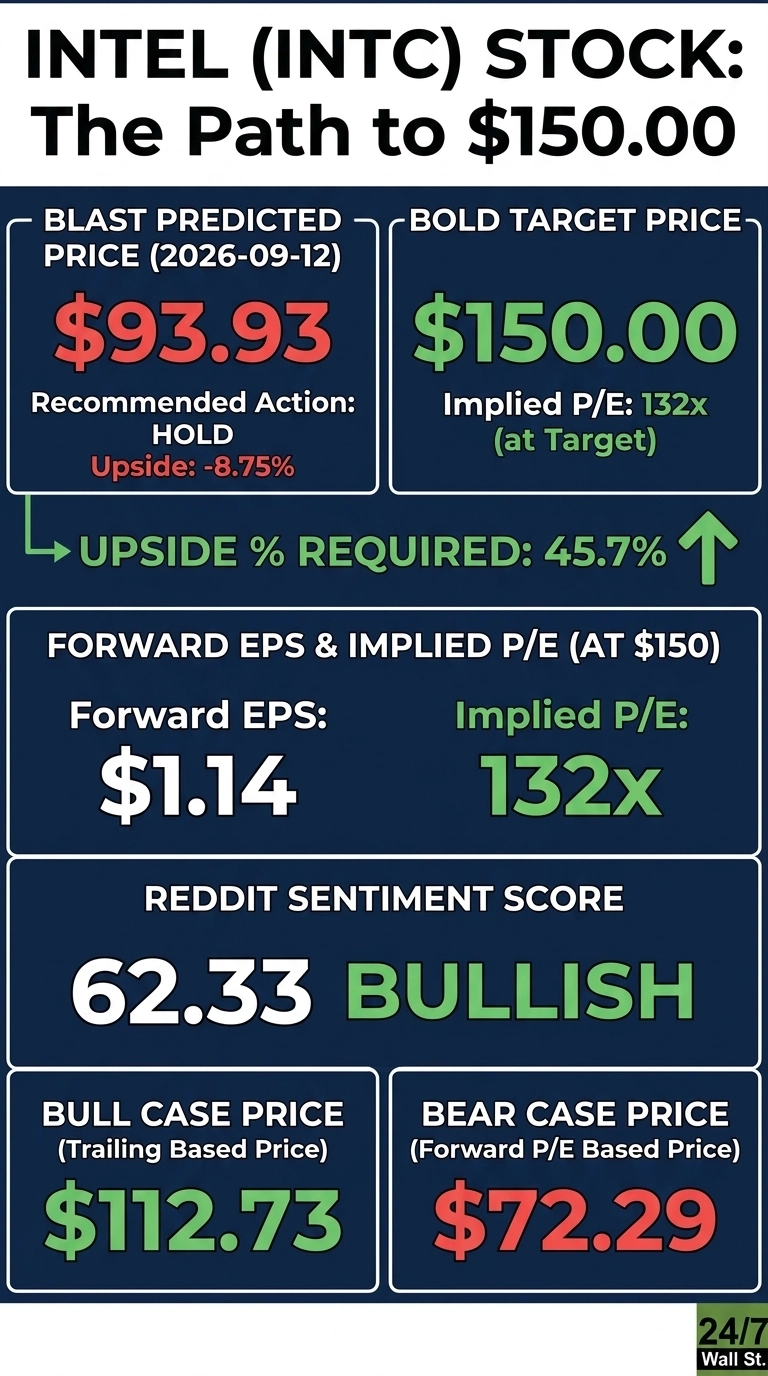
The Street’s consensus price target sits at $115.74, with 1 strong buy, 13 buy, 32 hold, 1 sell, and 1 strong sell rating. Our own model is tougher, calling for a base case of $93.93 with -8.75% upside, a bull case of $112.73, and a bear case of $72.29. Model confidence is high at 0.9.
My take: with bullish analyst share at 29 versus 4 bearish and DCAI compounding at a 59% pace, the Street is anchored to a pre-turnaround Intel that no longer exists.

Path to $150 Per Share
Reaching $150 from today’s price of $102.94 would require a gain of 45.7%. That is a big move on top of a stock that has already tripled. Here is the multiple math.
With forward EPS of $1.14, a $150 price implies a forward P/E of 132x. Our base case of $93.93 already implies 94x, meaning the bold target requires roughly 37x of additional multiple expansion.
That only works if forward EPS re-rates fast. Non-GAAP EPS has already climbed from $0.15 in Q4 2025 to $0.42 in Q2 2026, and Q2 operating cash flow hit $7.006 billion.
Tan told investors “strong demand for our products continue to outpace our growing supply” and the ASIC business is approaching a $2 billion run rate targeting $4 billion. The primary risk is that Intel Foundry losses persist and force another equity raise.

Where Intel Trades Today vs Its Earnings Power
At $102.94 against forward EPS of $1.14, Intel trades at roughly 90x forward earnings. That looks expensive on the surface, until you remember EPS is still depressed by Foundry losses and CHIPS-related charges.
Shares sit between a 52-week low of $24.22 and a 52-week high of $142.35, and the 10-year return of 256.65% shows this name can compound when execution lands. The bull case rests on earnings catching up to the price.

Is $150 Realistic? My Verdict
Reaching $150 requires a 45.7% gain from here. My verdict: a stretch, but a credible one.
Three things need to go right. Intel 18A yields keep tracking ahead of plan, DCAI holds a growth rate above 40%, and Foundry’s quarterly loss narrows meaningfully by late 2027. A stall in external foundry commitments would derail the story fast.
Investors hunting for the next monster semiconductor run should study what the early signals looked like in past winners (we cataloged those traits in a free Next Nvidia playbook). Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Intel could reach $150 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.