Retirees Who Leave Florida for Good Will Say Health Care Was the Reason Nobody Talked About
Most retirees who leave Florida point to family ties or the heat, but a quieter force drives more departures than anyone tracks, and it tends to show up for the first time in a specialist's waiting room.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Access to specialist care can play a bigger role in where retirees choose to live, especially in January. A retiree in Sarasota or Naples calls a rheumatologist after a new diagnosis, only to learn that the practice isn’t accepting new Medicare patients or that the next available appointment is months away. Retirees who leave Florida often point to family or the heat, but trouble getting timely medical care can also factor into the decision.
Most coverage of retirees leaving Florida focuses on insurance premiums and property taxes, but this piece looks at access to care, which is harder to measure. Below is what it takes to retire in Florida without health care becoming the reason to leave.
Plenty of Hospitals but Not Enough Open Appointments
Florida’s health care access depends on how many older patients there are for each doctor willing to take them, and that ratio varies widely by county. In a 2022 Florida Trend report, Polk County had one primary care doctor for every 2,080 residents. Next door in Hillsborough, it was one for every 1,210 people.
That gap helped make Lakeland Regional’s emergency department one of the busiest in the country, with more than 190,000 patient visits annually. Those figures are several years old. The county gap offers a clear measure of how unevenly primary care access is distributed.
Winter compounds the problem. Practices in snowbird-heavy areas take in a seasonal wave of part-year residents on top of year-round patients, creating different availability for those who arrive in July versus February.
Medicare Advantage Can Make Leaving Expensive
In Florida, 57% (3.0 million) of Medicare beneficiaries were in Medicare Advantage in 2025. KFF puts the national share at 55% in 2026. Medicare Advantage is the private-plan alternative to Original Medicare. Premiums are often low, but the plans run on provider networks drawn county by county, so a plan offered in Lee County may not exist in Polk, and it almost certainly won’t work in Ohio.
Moving out of a plan’s service area triggers a guaranteed issue right, meaning a Medigap insurance company must sell supplemental coverage without health questions. The application window is tight: no later than 63 days after your Medicare Advantage plan coverage ends. New enrollees also get a one-time 12-month trial right, closing 63 days after year one ends. The January through March Advantage open enrollment period lets someone drop a plan, but it does not guarantee Medigap access. Outside those windows, insurance companies in most states can ask health questions, charge more, or deny coverage. Connecticut and New York offer Medigap guaranteed issue year-round, though premiums run higher.
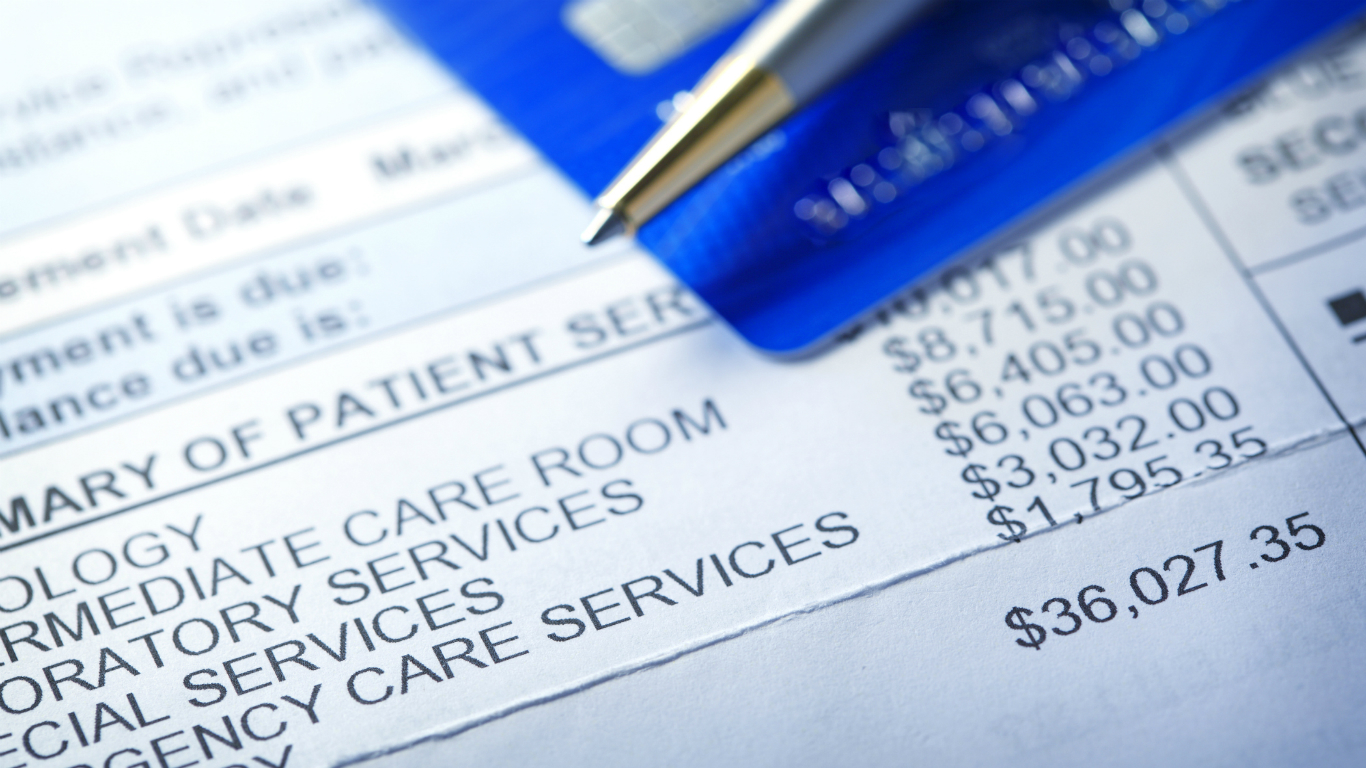
Original Medicare without a supplement has a $1,736 inpatient deductible in 2026, plus $217 a day in skilled nursing coinsurance for days 21 through 100. One hospital stay followed by a full rehab stay comes to $19,096, and that is before the premium surcharges and coverage gaps we cataloged in a free Medicare guide. For a retiree with a diagnosis who gets turned down for Medigap up north, that’s the real cost of moving, and it can come back with every serious episode.
Needing Care Changes Every Calculation
A couple managing independently faces different calculations once one spouse needs ongoing care. Distance from adult children often requires paying for help that family might otherwise provide. Reasons for moving include a diagnosis that requires regular specialist visits, a hospital stay that shows limited local support, or one spouse becoming a full-time caregiver. Moving closer to family can also lower living costs. The federal government’s regional price index puts Florida at 103.414, compared with 94.326 for North Carolina and 91.87 for Tennessee, where 100 is the national average.
Moves That Keep Every Exit Open
Retiring in Florida works best when the health care plan leaves room to leave. Turning 65 opens the one-time Medigap open enrollment window. Anyone who might ever move north should take a close look at Original Medicare plus Medigap during that window. Anyone who picks Advantage should treat the 12-month trial as a real decision deadline.
Paying for that $19,096 risk each year at a 4% withdrawal rate would take about $477,400 of portfolio. Some retirees instead hold a reserve of roughly $20,000 in a Treasury ladder or cash and secure a supplement while it’s still guaranteed, which costs much less. The 2027 COLA is tracking toward 3.3%. That helps with living costs, while supplemental coverage still depends on buying a policy during a guaranteed window.
Before listing a house, retirees can call ahead. They can ask specialists who treat their existing conditions in the county they’re considering whether the practice will accept a new Medicare patient with that condition in February, and which plans it takes.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.