Here’s When Nividia’s Dominance Fades, Opening Broadcom’s Era of Dominance
NVIDIA just posted triple-digit growth and Broadcom matched it with a custom chip story that has hyperscalers quietly betting billions against the GPU. Something has to give, and the timeline is closer than most investors realize.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) and Broadcom (NASDAQ:AVGO) delivered blockbuster AI quarters within a week of each other. NVIDIA’s Q2 FY2027 earnings report reinforced GPU dominance. Broadcom’s Q3 FY2026 report showed custom accelerators scaling faster than expected. AI compute is shifting from training-heavy GPU workloads toward inference-optimized ASICs, and both quarters offered evidence of how that handoff might unfold.
Blackwell Ultra Powers One Quarter, Custom XPUs Power the Other
NVIDIA posted revenue of $96.22B, up 105.8% YoY, with Data Center at $89.02B (+117%) and Networking at $40.31B (+138%). Jensen Huang told investors “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable.” Q3 guidance sits at $108.0B ±2%, excluding China.
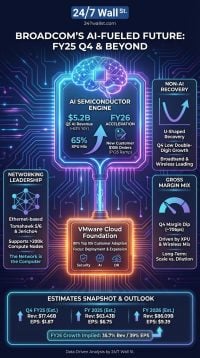
Broadcom’s story was one of concentration. AI semiconductor revenue reached $16.70B, up 221% YoY and 54% sequentially. Google’s Ironwood TPU v7 shipped in volume, TPU v8i began production, and OpenAI’s Jalapeno accelerator started shipping. Hock Tan guided Q4 AI revenue to roughly $21.7B (+236% YoY).
| Business Driver | NVIDIA | Broadcom |
| Main AI Engine | Blackwell Ultra, Vera Rubin | Custom XPUs for Google, Anthropic, OpenAI, Meta |
| Latest AI Growth | Data Center +117% YoY | AI semis +221% YoY |
| Networking Bet | Spectrum-X, NVLink 72 | Tomahawk 6/7, Tomahawk Ultra |
Platform Fortress Versus Workload Tuned Silicon
Huang framed NVIDIA as “a full-stack AI factory platform”, arguing rivals sell “inference-specific chips for one cloud or one service”. Management guided fiscal 2028 revenue growth of approximately 70%.
Broadcom’s counterargument came from customer wins. Tan claimed TPU v8i is “comparable if not surpasses the Vera Rubin GPU”, and that Jalapeno runs OpenAI workloads at “half the cost of a GPU”. Anthropic is expected to deploy five gigawatts of TPU v8i in 2027, and Broadcom has secured supply for roughly $115 billion of AI revenue in fiscal 2027 and $230 billion in fiscal 2028. That suggests investors have a reasonable timeframe to expect Broadcom could begin eroding Nvidia’s dominance in the very near future.
Supply Constraints Decide the Race
Both companies are supply-constrained. NVIDIA warned of “extreme pricing conditions in memory“. Broadcom is opening a Singapore substrate factory in fiscal 2027 and tripling laser capacity. Watch whether Vera Rubin holds its “fastest product ramp in NVIDIA’s history” promise and whether Broadcom converts its 10-gigawatt 2028 Anthropic pipeline into shipped silicon.
Why I Own Both, But Weight Them Differently
NVIDIA’s CUDA, integrated networking, and financing partnerships with Apollo, BlackRock, Blackstone, Brookfield, Goldman and KKR build a moat ASICs can chip at but not crack. Broadcom trades at a forward P/E of 18 versus NVDA at 23, despite a clearer glide path from $58 billion in fiscal 2026 AI revenue toward $230 billion in fiscal 2028. Defensive AI investors get more comfort from NVIDIA. Investors chasing the inference era have the more interesting call in Broadcom’s XPU cohort (we reverse-engineered what the biggest tech winners looked like early and turned it into a free playbook here).
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.