Prediction: AMD’s Biggest Growth Opportunity May Still Be Ahead
AMD just posted the most consequential quarter in its history and Lisa Su says the company is tracking ahead of its own targets, yet the stock sits 5% below its peak with Wall Street split on what comes next. Here…

Advanced Micro Devices just posted the most consequential quarter in its history, and Lisa Su thinks the story is only getting started. AMD (NASDAQ:AMD | AMD Price Prediction | AMD Price Prediction) delivered $11.5 billion in Q2 2026 revenue, with Data Center sales up 107% year over year to $6.72 billion.
Shares have responded, ripping 148.76% year to date. Yet at $532.75, I still think the biggest leg is ahead. The question I want to answer: can AMD reach $800 by 2027?
What’s Holding AMD Back Right Now
Even after a monster year, AMD has hit some turbulence. Chip stocks pulled back sharply this month on concerns about the pace of AI capex, with AMD sinking 6% during a September 14 selloff tied to AI pacing worries. The stock still sits 5% below its 52-week high of $584.73, and momentum has cooled to a 2.24% gain over the past week and 5.29% over the past month.
Part of the hesitation is valuation. Part is a beta of 2.48, which means every macro wobble hits AMD harder than the average chip stock. And Gaming revenue fell 31% year over year to $779 million, a reminder that not every segment is participating in the AI boom. Investors want proof the Helios ramp lands cleanly before paying up further.
Wall Street Sees 15.7% Upside. I Think That’s Too Cautious
The sell-side is bullish, but not aggressive. The consensus analyst target sits at $616.51, implying roughly 15.7% upside from here. The recommendation split is 4 Strong Buy, 39 Buy, 11 Hold, and zero sells, with 80% bullish sentiment.
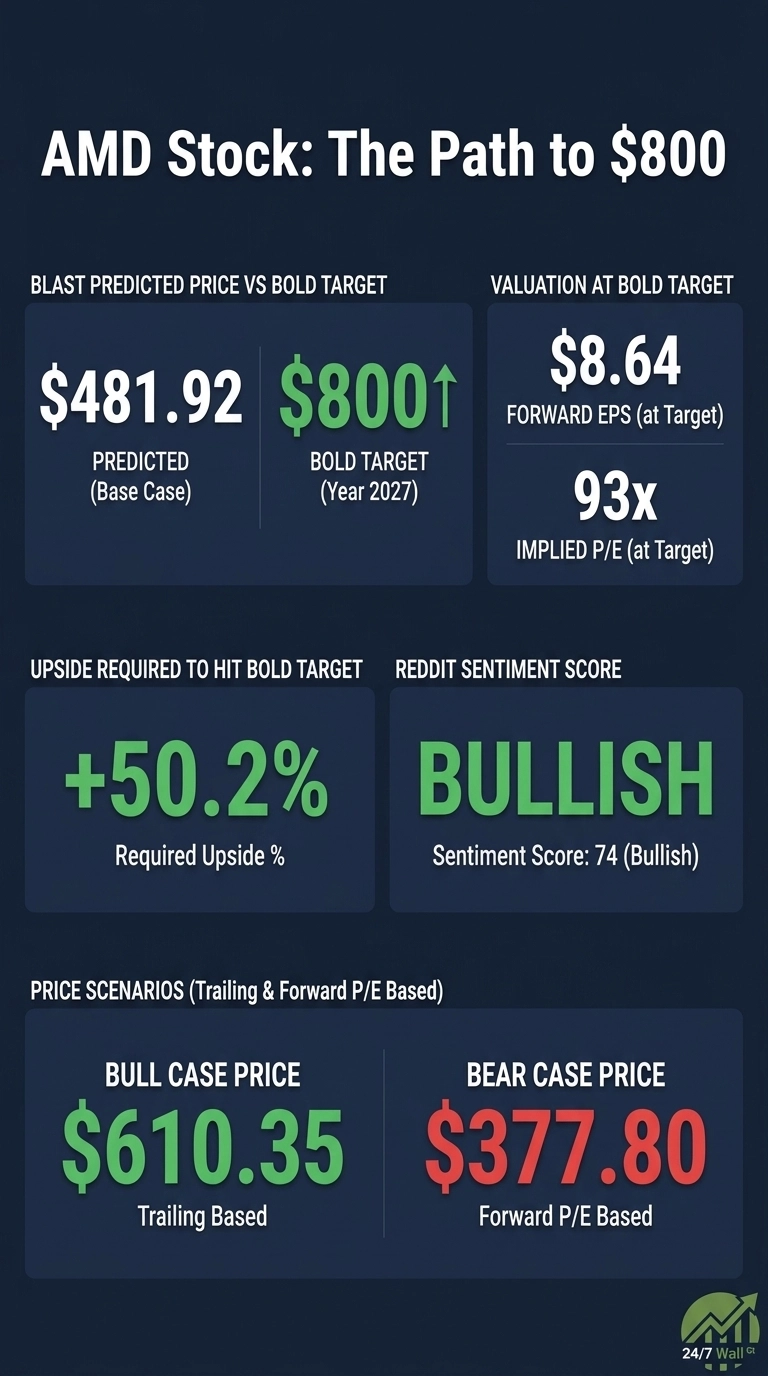
Our own model is more restrained near term, with a base case of $481.92 and a bull case of $610.35 over the next 12 months, producing a hold rating.

But I think both views underweight what happens when Helios shipments actually scale. Su told investors AMD is “tracking materially ahead” of its Financial Analyst Day model and expects to “significantly exceed our $20 annual EPS target within our strategic timeframe.” That reframes the entire multiple debate.
Path to $800 Per Share
Reaching $800 from today’s price of $532.75 would require a gain of 50.2%. With forward EPS of $8.64, a price of $800 implies a forward P/E of 93x.
Our base case of $481.92 already implies 91x, meaning the bold target requires only about 1x of additional multiple expansion. This is fundamentally an earnings story, not a multiple story.
Su told analysts AMD expects Data Center segment revenue to more than double year-over-year in 2027, with server revenue growing more than 70% for the full year 2027.
Anchor customers include OpenAI, Meta, Anthropic (up to 2 gigawatts of MI450 GPUs in Helios), and Microsoft Azure. Su said “Customer pull for Helios is very strong and tracking ahead of our initial forecasts.” The main risk is Helios yield timing in the early quarters of the ramp.
Where AMD Trades Today vs Its Earnings Power
At $532.75 and $8.64 in forward EPS, AMD trades at a current forward P/E of 62x. That looks steep in isolation, but earnings are compounding at a pace that quickly rerates the math.
Shares sit near the 52-week high of $584.73 and well above the 52-week low of $149.85. Long-term holders have been paid handsomely, with AMD returning 8,705.79% over the past decade. If Data Center more than doubles again in 2027 as guided, the current multiple compresses fast even without price appreciation.

Is $800 Realistic? Here’s My Take
Reaching $800 requires a 50.2% gain from here. I call that a stretch, but a credible one.
Three things need to go right: Helios must ship on schedule through Q4 2026 and 2027, the Anthropic first-gigawatt deployment slated for H1 2027 has to convert to revenue, and EPYC Venice needs to hold gross margin above the 56% line. A stumble on Helios yields or a broader AI capex pause would derail it.
Worth remembering too that AMD is only one slice of the buildout: the power, cooling, and networking suppliers behind these data centers are their own trade, and we profiled seven of them in a free report on the AI infrastructure names beyond the chipmakers. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how AMD could reach $800 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.