Prediction: Seagate Could Be a Surprisingly Big Winner From the AI Boom
Hard drives look like a relic next to the glamorous AI chip trade, yet Seagate shareholders have watched the stock surge nearly 300% in a single year. The real question is whether the forces driving that run have staying power…


Seagate has turned into one of the most surprising AI beneficiaries in the entire tech complex. Hard drives sit in the unglamorous corner of the AI stack, yet hyperscalers still need somewhere to warehouse the exabytes their models generate.
That has translated into a moonshot for shareholders and a fresh question for buyers today: does the 24/7 Wall St. price target justify chasing the stock at these levels?
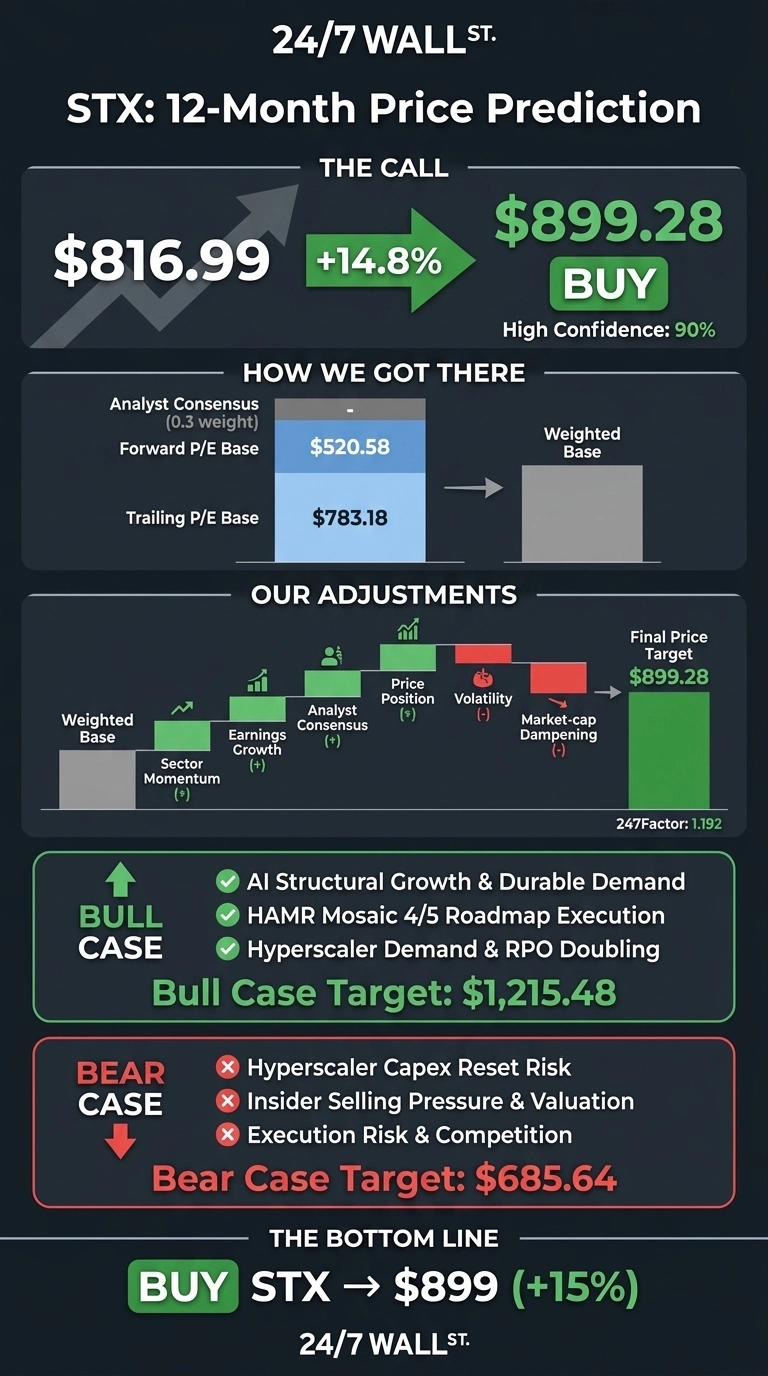
Seagate Technology (NASDAQ:STX | STX Price Prediction) trades at $816.99 in early Thursday action, and our proprietary model uses a reference price of $783.18. Our 24/7 Wall St. price target for Seagate is $899.28, implying 14.82% upside over the next 12 months. The recommendation is a buy, and our confidence is high at 90%.
| Metric | Value |
|---|---|
| Current Price | $816.99 |
| 24/7 Wall St. Price Target | $899.28 |
| Upside | 14.82% |
| Recommendation | BUY |
| Confidence Level | 90% |

A Structural AI Story Hiding in a Legacy Sector
Seagate is up 290.14% over one year and 197.42% year to date, though shares have cooled 17.87% over the past month from a 52-week high of $1,144.18.
The pullback follows a blowout fiscal Q4 report on July 28, 2026: revenue of $3.63 billion (up 48.49% year over year) and non-GAAP EPS of $5.71, beating expectations by 12.11%. Full-year FY26 free cash flow hit a record $3.105 billion, up 279.58%.

Why Bulls See a Breakout Ahead
Management now guides to “a minimum of 20% over the next few years” in annual revenue growth, up from prior mid-teens targets. CEO Dave Mosley said Seagate is “now entering a period of structural growth” and that nearline capacity is “almost fully allocated through calendar 2027.”
Mosaic 4 HAMR drives deliver up to 44 terabytes per drive, and Mosaic 5 is targeting 50 terabytes with qualification shipments in late 2027. The top three cloud service providers alone have nearly doubled remaining performance obligations to $1.1 trillion.
Fiscal 2028 consensus EPS has been revised up to $55.37, and a bull case aligned with the Street target puts shares at $1,215.48 in 12 months.

What Could Go Wrong
The bear case starts with concentration risk. If hyperscaler capex normalizes, exabyte pricing power fades quickly. Seagate carries a trailing PE of 58 and a price-to-book of 85, leaving little margin for a miss.
Insiders have been steady sellers, with CEO Mosley disposing of shares at prices between $783.83 and $862.13 across August and September. Bulls would counter that much of that activity ties to restricted-share vesting and option conversions, not conviction sales. Our bear case lands at $685.64.

How Seagate Compares to Western Digital and Micron
Western Digital (NASDAQ:WDC) is the direct HDD duopoly partner and the cleanest apples-to-apples read. WDC trades at a forward P/E of 21, essentially matching Seagate’s 23, with quarterly revenue growth of 43.8%. That parity suggests our target sits reasonably in line with the peer set.
Micron Technology (NASDAQ:MU) captures the memory side of the AI storage trade. Micron’s forward P/E of just 6 versus Seagate’s 23 highlights how much re-rating has already occurred in STX, arguing for a disciplined price target rather than chasing consensus.
| Company | Forward P/E | Beta |
|---|---|---|
| Seagate | 23 | 2.09 |
| Western Digital | 21 | 2.18 |
| Micron | 6 | 2.22 |
Seagate Price Prediction 2026-2030
The 24/7 Wall St. price target of $899.28 supports a buy with 90% confidence. The tipping factor is capacity allocation: Seagate has already sold out its HAMR supply through calendar 2027 at negotiated pricing.
A pullback toward the $750 area would look more attractive if fiscal Q1 delivers on the $4.10 billion revenue guide. The setup deteriorates if hyperscaler capex commentary softens or if HAMR yield stumbles into the Mosaic 5 ramp.
Looking further ahead, our model projects the following base-case trajectory, assuming continued HAMR execution and durable AI-driven exabyte demand.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $825 |
| 2027 | $930 |
| 2028 | $1,052 |
| 2029 | $1,120 |
| 2030 | $1,196 |
These projections assume Seagate continues converting its HAMR roadmap into pricing power. Significant upside or downside could come from a faster Mosaic 5 ramp or a hyperscaler capex reset.
Storage is only one slice of the picking-and-shoveling trade around AI infrastructure, and we pulled together seven non-chipmaker names riding the same buildout in a free report here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers).
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.