Prediction: This Is Where Nvidia Stock Could Be by the End of Next Year
Nvidia shares have already delivered 900% over five years, but a specific multiple applied to a rising earnings estimate points to a price target that Wall Street has not yet penciled in. Here is the math behind the case for…

NVIDIA (NASDAQ: NVDA | NVDA Price Prediction) has spent the last year proving that the AI infrastructure buildout is not slowing down. Shares are up 17.39% year to date and 25.2% over the past year, extending a run that has delivered 901.72% over five years.
CEO Jensen Huang framed the current moment bluntly on the August call: “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue.”
With Vera Rubin in full production and hyperscaler backlogs swelling, the question I keep hearing is how high shares can go. Here is what NVIDIA needs to do to reach $400 by the end of 2027.

Wall Street Already Sees Big Upside From Here
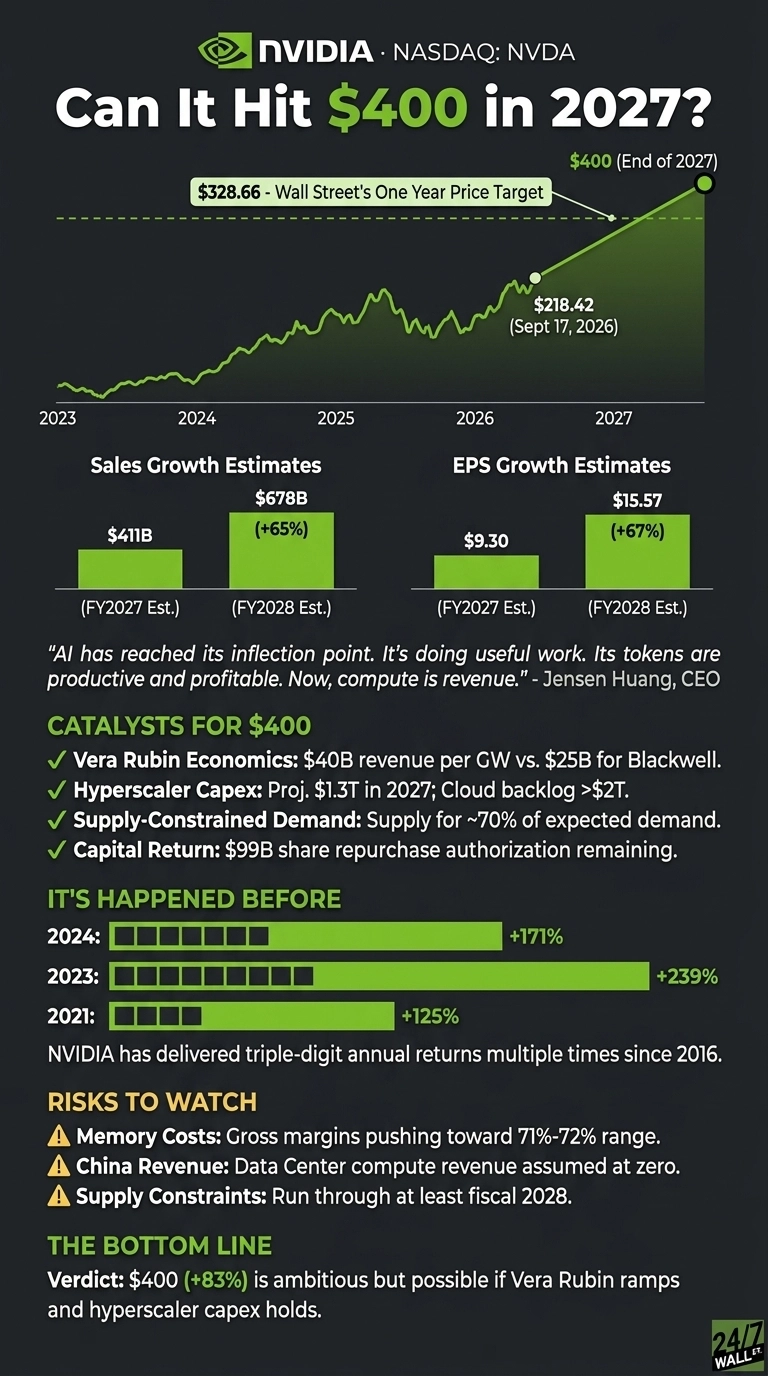
The Street is unusually aligned on NVIDIA. The average analyst target sits at $328.66, with 9 strong buys, 48 buys, 2 holds, and 1 sell. Estimates keep climbing: the FY2028 EPS consensus has moved from $12.6718 ninety days ago to $15.5675 today, backed by 39 upward revisions in the last 30 days and zero cuts.
FY2027 revenue consensus now sits at $411.29 billion. NVIDIA has also beaten expectations in five straight quarters, most recently by 6.29% on EPS and 4.51% on revenue, so actual results have consistently run ahead of the model.
Path to $400 Per Share
At $218.42, NVDA trades at roughly 23x forward earnings, essentially in line with the S&P 500’s forward multiple around 21x to 23x despite growing revenue 105.85% year over year. Applying a 26x multiple to the current FY2028 EPS estimate of $15.5675 gets you into the $400 zip code, and the high-end FY2028 estimate is already $18.7460.

What could push NVIDIA to $400?
- Vera Rubin economics. Revenue opportunity per gigawatt jumps from $25 billion on Blackwell to $40 billion on Vera Rubin, and management expects it to be the fastest product ramp in NVIDIA’s history.
- Hyperscaler capex. Top-five hyperscaler spending is projected at nearly $800 billion in 2026 and $1.3 trillion in 2027, with cloud backlog already greater than $2 trillion.
- Supply-constrained guidance. Management guided FY2028 revenue growth of approximately 70%, noting customer forecasts imply doubling and that NVIDIA has supply for only about 70% of expected demand.
- Capital return. $99 billion remains under buyback authorization, with $26 billion returned in Q2 alone.
- Anchor customers. OpenAI commitments represent roughly 12 gigawatts of NVIDIA compute, AWS is deploying an additional 2 million GPUs, and financing partners are mobilizing over $500 billion of third-party capital.

NVIDIA Has Done Bigger Moves Before
A run to $400 by end of 2027 requires roughly 83% upside from here. That sounds steep, but NVIDIA returned 224% in 2016, 125% in 2021, 239% in 2023, and 171% in 2024.
With a market cap already at $5.12 trillion, repeating those triple-digit years is harder, but a 15-month push through consensus is well within the company’s historical range. Prediction-market sentiment is also constructive, with a composite score of 75.66 and a bullish direction.
Is $400 Realistic? My Take
Getting to $400 requires NVIDIA to keep beating estimates, Vera Rubin to ramp as advertised, and hyperscaler capex to hold at forecast levels.
Risks are real: memory costs are pushing gross margins from 75% toward 71% to 72% before recovering, China Data Center revenue is assumed at zero, and supply constraints run through at least fiscal 2028. The buildout also has a second layer of beneficiaries beyond the chipmaker itself, and we profiled seven of them, from power to cooling to networking, in a free AI infrastructure report.
Even so, with estimates rising, buybacks active, and demand outpacing supply, returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how NVIDIA could see outsized returns by the end of 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.