Nvidia’s Blowout Earnings: How High Can the Stock Go Now?
NVIDIA just delivered one of the most staggering quarters in corporate history, yet the stock trades as if Wall Street missed the memo. Whether that gap closes toward $350 depends on three things falling into place at exactly the right…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) just posted one of the most consequential quarters in corporate history, and the stock barely flinched. NVIDIA reported Q2 FY27 revenue of $96.22 billion, up 105.8% year over year, with Data Center alone pulling in $89.02 billion.
Yet shares closed at $209.66, up just 12.55% year to date. CEO Jensen Huang told investors “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue.” Can NVIDIA reach $350 in 2027? Here is the case.

Why NVDA Shares Are Lagging Their Fundamentals
NVDA is down 3.63% over the past week despite blowout results, and the 1-year return of 15.49% trails fundamentals badly. With a beta of 2.215, this is volatile. Three concerns weigh on investors:
- no China Data Center compute revenue in the Q3 outlook
- Gross margins guided from 75% down to 74% in Q3, expected to bottom in the 71% to 72% range in Q4 as memory prices climb
- $279 billion in supply commitments and $108.5 billion in guarantee obligations feed a “circular financing” narrative around frontier AI labs
DSO stretched to 60 days from 45. The market is quietly asking whether growth this large is sustainable.
Wall Street’s $304 Target May Be Too Cautious
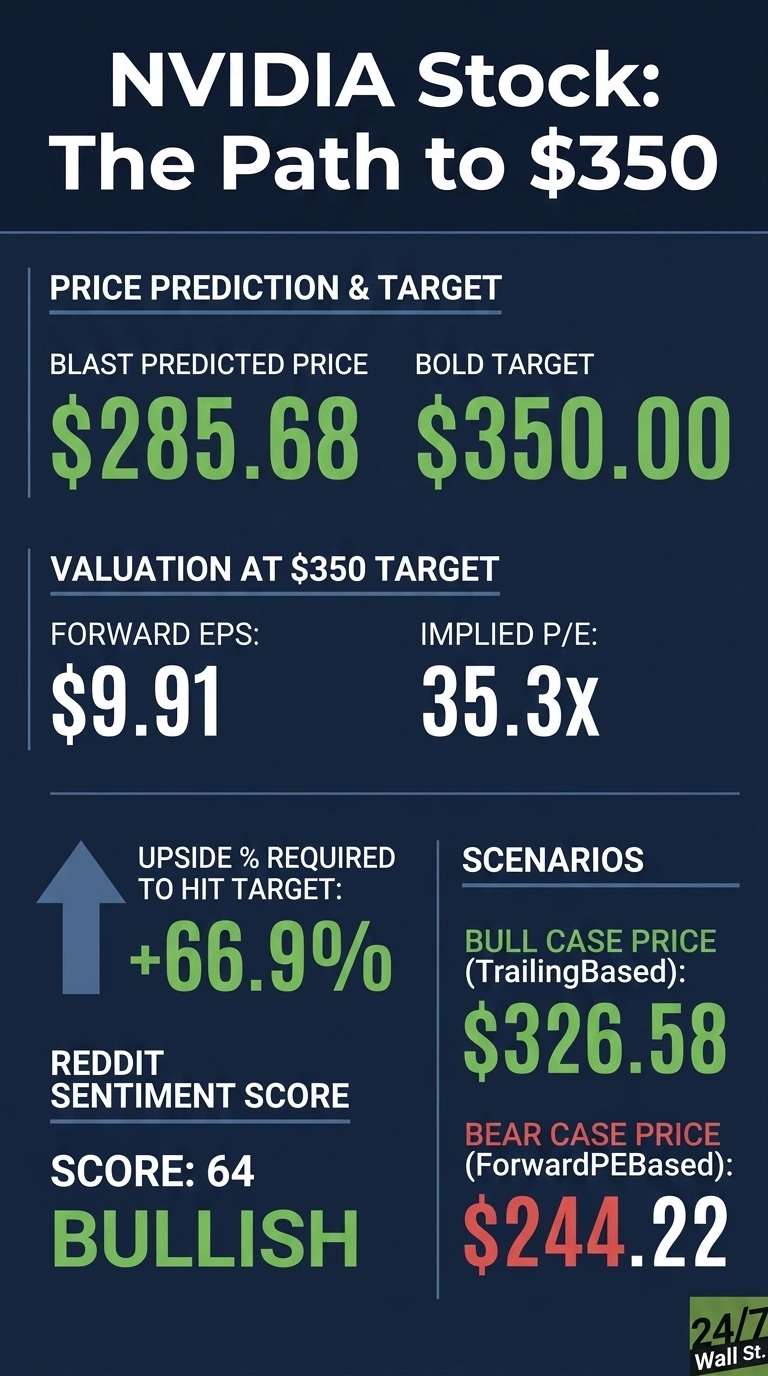
The Street’s average price target sits at $304.73, with coverage heavily bullish: 10 strong buy, 48 buy, 2 hold, 1 sell. Our internal model pins base case at $285.68 with high confidence, bull case at $326.58, and bear case at $244.22.
Quarterly earnings growth accelerated 214.5% year over year, and management guided fiscal 2028 revenue to grow approximately 70%. Analyst sentiment is 95% bullish, but consensus targets have not repriced to that trajectory.
When Huang says “At this moment, we have supply for 70%. We have more supply than 70%, but about 70%. Our demand is much higher than that”, the case for a higher multiple is math the models have not caught up to.

Path to $350 Per Share
Reaching $350 from today’s price of $209.66 would require a gain of 66.9%. With forward EPS of $9.91, a price of $350 implies a forward P/E of 35x.
Our base case of $285.68 already implies 30x, so the bold target requires roughly 5x additional multiple expansion. NVDA currently trades at a forward P/E of just 24x, meaning I am arguing for modest re-rating on genuinely accelerating earnings. Catalysts are stacked:
- Vera Rubin is in full production and expected to be NVIDIA’s fastest ramp ever
- Revenue opportunity per gigawatt jumps from $25 billion (Blackwell) to $40 billion (Vera Rubin)
- AWS just committed to 2 million additional GPUs
- Cloud backlog exceeds $2 trillion
- Top-five hyperscaler capex is tracking toward $1.3 trillion in 2027
Q3 revenue guidance of $108 billion, plus or minus 2% is compounding revenue. The buildout behind those numbers has to be powered, cooled, and networked by somebody, and we rounded up seven of those suppliers in a free report on the AI infrastructure names that aren’t chipmakers.
Risk: memory cost inflation could delay the re-rating into fiscal 2028.

Where NVIDIA Trades Vs Its Earnings Power
At $209.66 against $9.91 in forward EPS, NVDA trades near 21x forward earnings. For a company growing revenue over 100% year over year at 75% gross margins and 65.6% operating margins, that looks cheap.
Shares sit between a 52-week low of $163.85 and a high of $236.26. Over the last decade the stock has returned 13,660.88%. The bull case rests on earnings power compounding faster than the multiple compresses.
Is $350 Realistic?
$350 requires a gain of 66.9% from today’s $209.66. A stretch, but not a fantasy.
Three things need to go right: Vera Rubin ramps cleanly without supply chain slippage, gross margins recover to the 72% to 73% range in fiscal 2028, and Wall Street re-rates the multiple as FY28 growth crystallizes. The key risk: any credible signal that hyperscaler capex is peaking. We’ve outlined the blueprint for how NVIDIA could reach $350 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.