Arm’s Shift From Royalties to Silicon Manufacturing Could Reshape Chip Economics
Arm's CEO cited the same customer demand figure in July and September, yet the stock reacted in completely opposite ways. What shifted between those two moments could redefine how the entire chip industry prices silicon.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Arm (NASDAQ:ARM | ARM Price Prediction) stock has moved in three different directions on the same customer-demand figure in four months. The chip designer plunged from an early-September peak near $452 in June to just under $244, a 46% drawdown reflecting a broader unwind of AI capital-spending optimism. On September 18, shares closed at $275.61, up 4.04%, after CEO Rene Haas told Jim Cramer that demand for Arm’s technology has “never looked better.”
Haas has cited the AGI CPU demand figure before. Arm unveiled the chip in March with a roughly $1 billion revenue guide across fiscal 2027 and 2028. By May, disclosed customer demand had already surpassed that figure, yet the stock fell because the guide did not move. In July, Haas said demand “now exceeds $2 billion.” In September, the same $2 billion figure produced the biggest rally yet. The tone changed.
What Actually Changed Between May and September

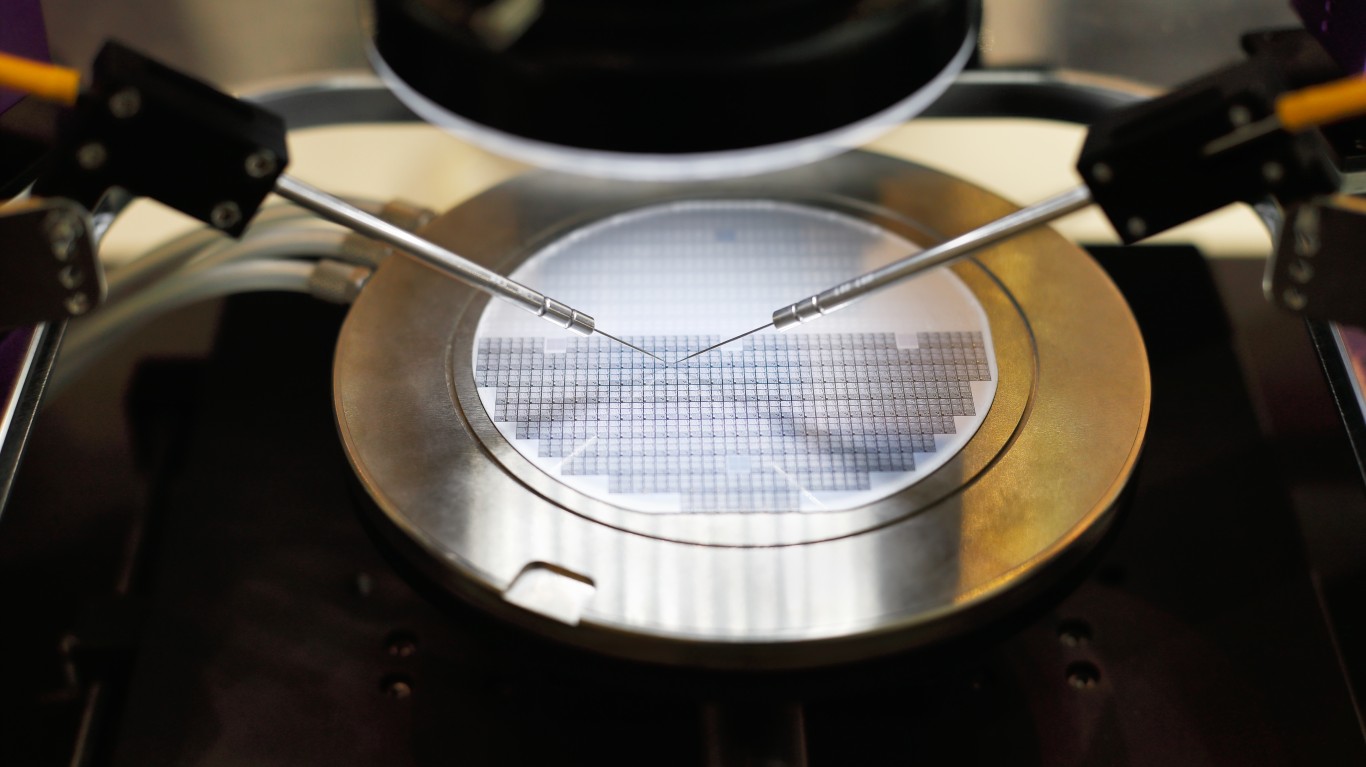
Supply is what changed. In July, Haas told analysts that “our confidence level and being able to secure the supply necessary has gotten better” across wafers, substrates, test capacity, and memory.
Margins on the in-house silicon are modest by Arm’s standards. Child said first-generation gross margin will land in the high 30% range, maybe low 40s, with a longer-term path to 50%. Compare that to Arm’s corporate 92.5% gross margin on royalties, and the mix shift is real.
Where NVIDIA and Qualcomm Sit on the Same Trade
NVIDIA (NASDAQ:NVDA) benefits from this shift. Haas said NVIDIA’s Arm-based Vera CPU delivers “up to 50% higher CPU performance and two times greater energy efficiency than comparable x86 systems,” feeding Arm’s royalty stream.
Qualcomm (NASDAQ:QCOM) sits on both sides. It announced an Arm-based data-center CPU called Dragonfly C1000, yet remains Arm’s legal adversary, with the Nuvia license trial expected in Q4 2026. A loss could reprice per-chip royalties across the industry.
Arm trades at a trailing P/E of roughly 326x after a 152.14% year-to-date run. Q1 fiscal 2027 EPS of $0.25 missed the $0.4038 estimate by 38.09%, with operating margin compressed to 7%.


Data-center royalty revenue more than doubled year over year, and Neoverse shipments passed 1.5 billion cores, with the last 500 million arriving in nine months. That is the earnings mix a $294 billion market cap is discounting, and it is the same buildout feeding the power, cooling, and networking names we profiled in a free report on seven AI infrastructure suppliers that aren’t chipmakers.
Bull and Bear Case for ARM Stock

The bull case rests on the AGI CPU converting on time. Haas framed the quarter as a “tale of two stories,” with Meta as lead partner and NVIDIA, Google Axion, AWS Graviton 5, and Microsoft Cobalt all seeded on Neoverse. If the CPU total addressable market moves toward the $200 billion range Child referenced, current royalty growth understates the runway.
Capacity is the deciding variable. Arm needs first shipments at the end of calendar 2026 to hold this valuation.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.