This Energy Stock Has 130% Upside Potential
Oklo shares have been crushed over the past year, yet the company just pulled off something no other advanced nuclear startup has done at full scale. Whether that milestone is already priced in or barely noticed depends on which numbers…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

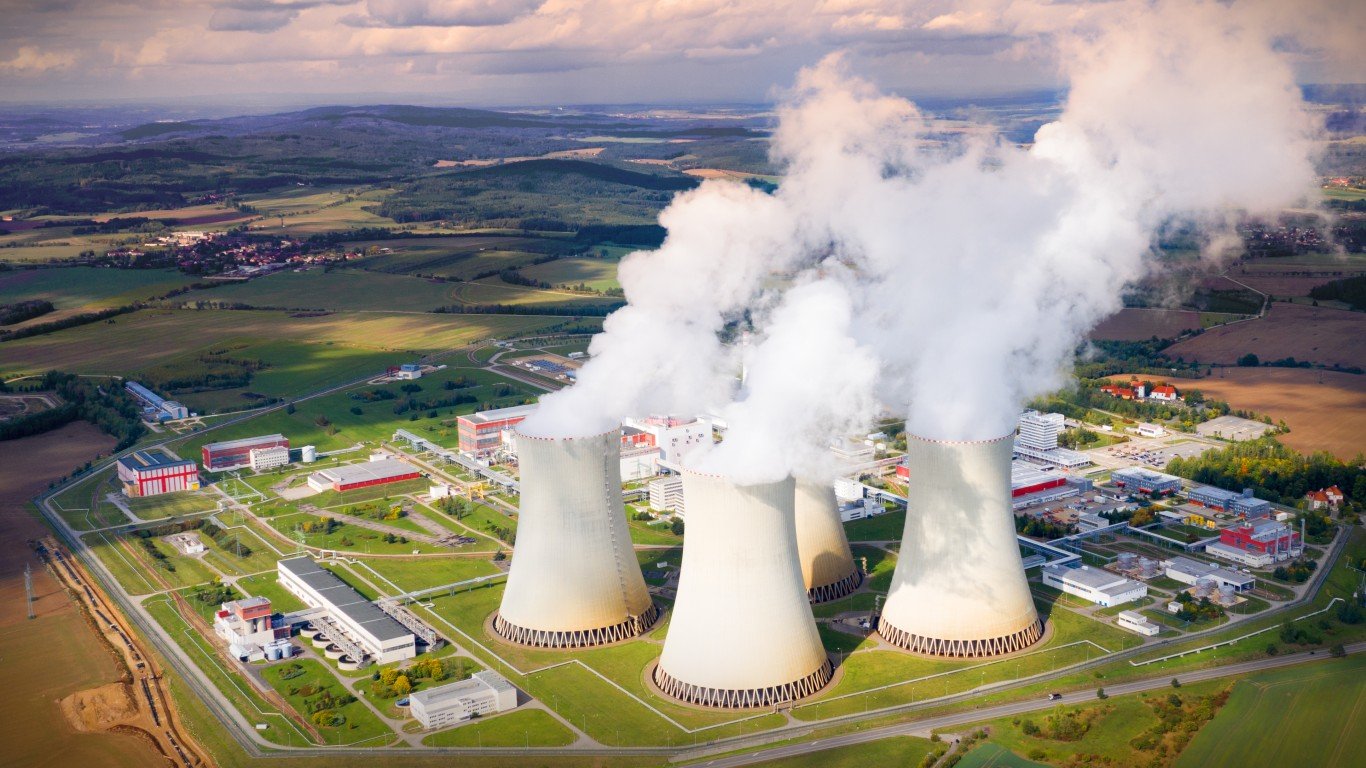
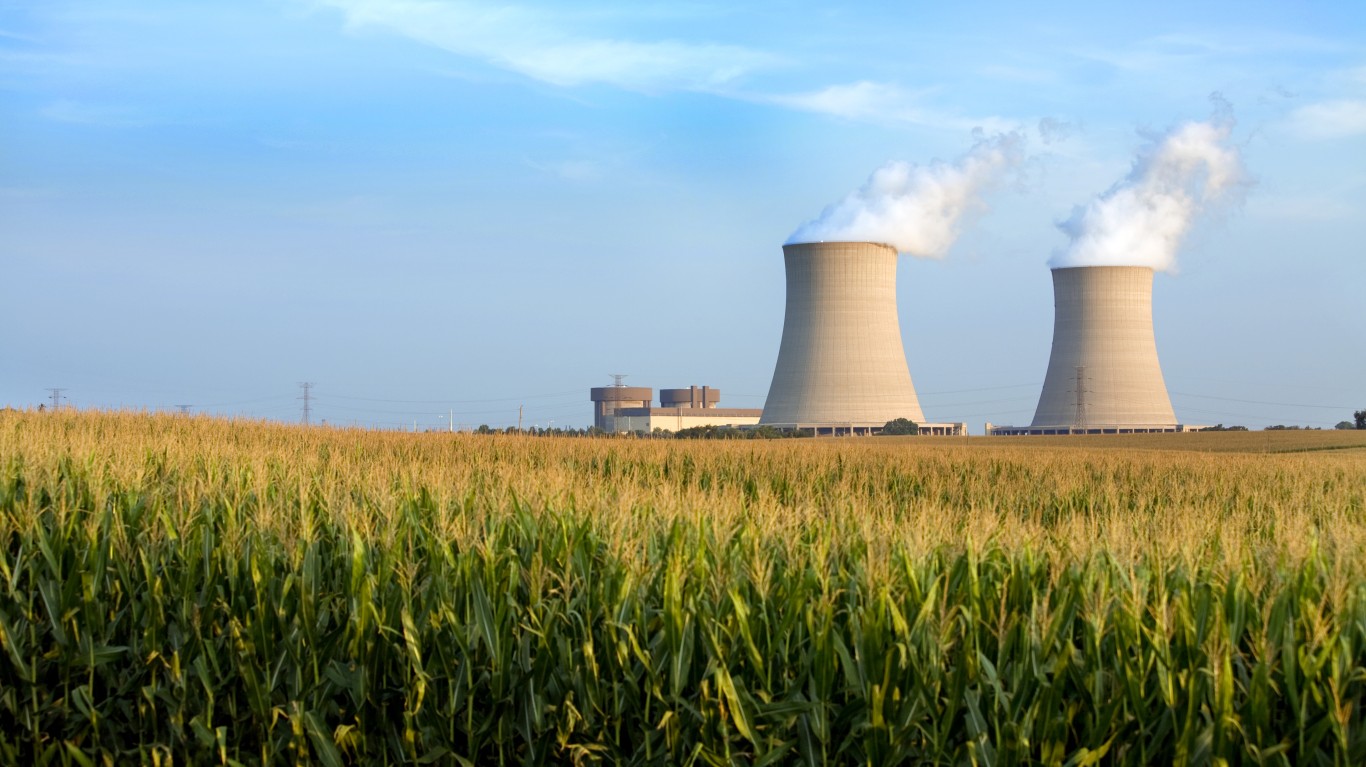
Advanced nuclear is one of the few investment themes where the ceiling is defined by physics and grid capacity rather than market saturation. Oklo (NYSE:OKLO | OKLO Price Prediction) sits at the center of that story.
After a punishing year in the share price, our proprietary model sees meaningful room for a rebound. The stock trades at $38, and our 24/7 Wall St. price target is $87.11, implying 129.24% upside over 12 months. Recommendation: buy with moderate confidence.
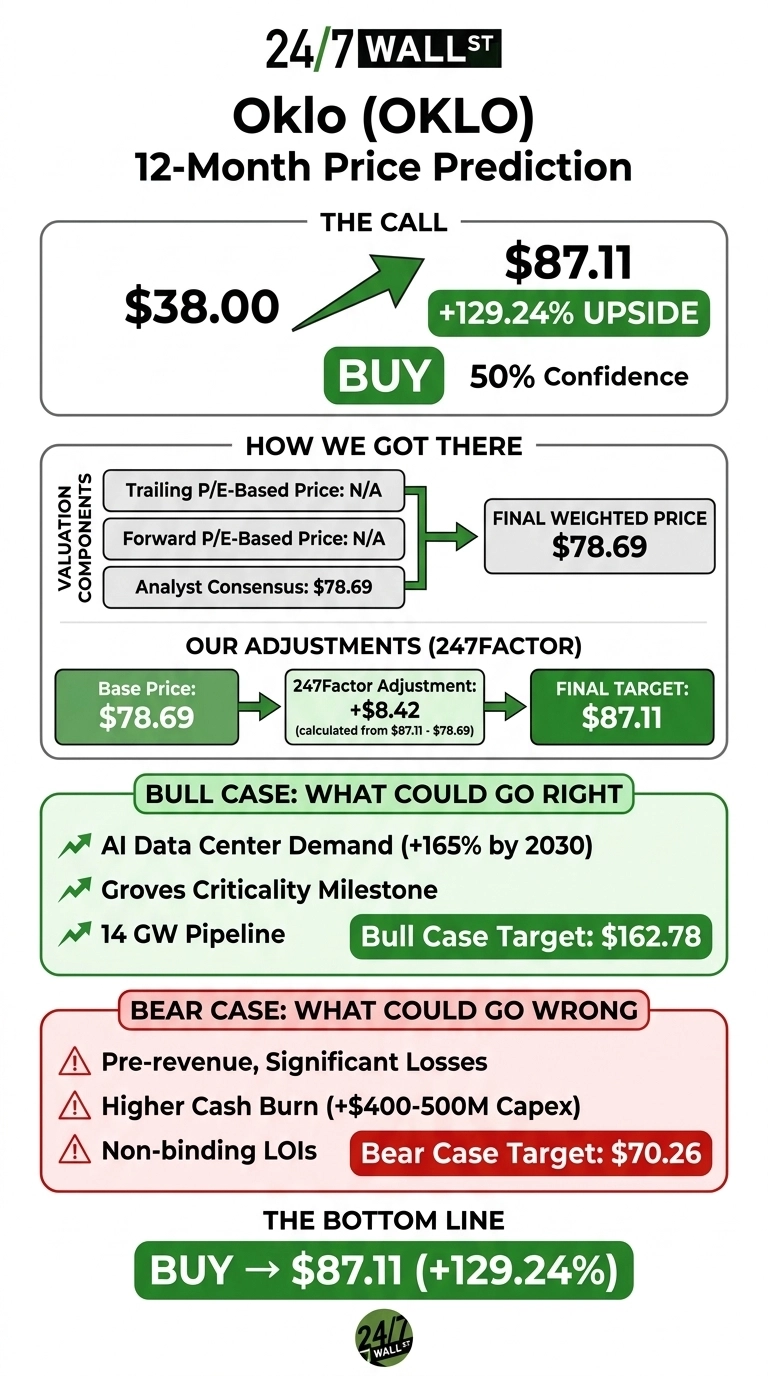
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $38.00 |
| 24/7 Wall St. Price Target | $87.11 |
| Upside | 129.24% |
| Recommendation | BUY |
| Confidence Level | 50% |

A Brutal Year Meets a Genuine Milestone
Oklo shares are down 63.8% over the past year and 47.05% year to date, falling from a 52-week high of $193.84 to $34.38. The one-month move is down 11.5%, though shares have ticked up 4.91% in the past week.
The operational story runs the other direction. On the Q2 2026 call, management said Groves “reached first criticality in early August 2026,” going from greenfield to criticality in “a little over 11 months from groundbreaking.” Oklo ended the quarter with $3 billion in cash and marketable securities, a war chest few pre-revenue peers can match.
Why Bulls See a Breakout Ahead
The bull case rests on demand scale and execution speed. Oklo’s pipeline sits at roughly 14 GW, anchored by a 12 GW master power agreement with Switch, a 500 MW LOI with Equinix carrying a $25M prepayment, and Aurora Ohio’s planned 1.2 gigawatt campus with Kiewit.
Goldman Sachs projects AI data center power demand up 165% by 2030. CEO Jacob DeWitte framed fuel as “not a constraint; it’s an opportunity.” Bull-case scenario points to $162.78 if Aurora INL hits 2028 startup and additional LOIs convert.

Risks Worth Watching
Oklo is pre-revenue. FY24 net loss was $73.62M, and 2026 cash burn guidance was raised to $120 million to $150 million for operations plus $400 to $500 million for property, plant, and equipment.
Most customer agreements remain non-binding LOIs. Bulls counter that higher spend reflects accelerated procurement at Aurora INL and opportunistic fuel purchases. Bear-case scenario lands at $70.26, above today’s price.

How Oklo Compares to BWXT and NuScale
BWX Technologies (NYSE:BWXT) is the mature counterpoint: a $13.48 billion market-cap nuclear manufacturer generating $901.6 million in Q2 2026 revenue with raised full-year non-GAAP EPS guidance of $4.70 to $4.80. BWXT shows what nuclear cash flow looks like at scale; its premium supports the reasonableness of our Oklo target on an option-value basis.
NuScale Power (NYSE:SMR) is the closest SMR peer at $3.39 billion market cap, with Q2 2026 revenue of just $75,000 and -21.9 operating margin. Oklo trades at roughly twice NuScale’s cap despite similar pre-commercial status, but Groves criticality and $3 billion in liquidity justify the gap. Against this peer set, our $87.11 target looks reasonable.
Oklo Price Prediction 2026-2030
Our 24/7 Wall St. price target of $87.11 reflects a buy with 50% confidence. Groves is the tipping factor. Oklo has designed, built, licensed, and operated a full-scale reactor, changing the risk profile of every future project.
The setup favors investors who can absorb 2027 to 2028 execution risk on Aurora INL. Those unwilling to tolerate additional equity dilution or an NRC delay may prefer to wait. (For readers weighing broader exposure to the restart, we mapped five ways to play it, utilities and fuel included, in a free nuclear report.)
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $46.28 |
| 2027 | $87.11 |
| 2028 | $157.00 |
| 2029 | $232.33 |
| 2030 | $313.34 |
These projections assume Aurora INL delivers commercial power on the current late-2027 to 2028 timeline and that customer LOIs convert to binding PPAs. Significant upside or downside could come from HALEU fuel availability, NRC licensing pace, or the trajectory of AI data center power demand.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.