The Next Chapter of Eli Lilly Could Be Bigger Than Investors Expect
Eli Lilly is posting 48% revenue growth while its stock sits nearly flat for the year, and that disconnect points to something Wall Street may be mispricing entirely.


Eli Lilly (NYSE:LLY | LLY Price Prediction | LLY Price Prediction) is doing something unusual for a mega-cap: growing revenue at 48% year over year while shares trade only 7.8% higher year to date.
Mounjaro and Zepbound combined for $14.9 billion in Q2 revenue, and CEO David Ricks told investors “Lilly’s future, after 150 years, has never been brighter.” So here is the question I want to answer directly: can LLY shares reach $1,500 by the end of 2027?

Why LLY Shares Are Stuck Despite 48% Revenue Growth
The stock is stalling because expectations reset faster than fundamentals. Shares are down 9.95% over the past month even after climbing 3.34% in the last week.
Investors are digesting a 9% U.S. price decline (excluding rebate adjustments), heavy $2.78 billion in IPR&D charges from four Q2 acquisitions, and a 1-year gain of 52.08% that already priced in a lot of the incretin story. Beta sits at just 0.502, so this is a valuation-digestion story compounded by recent insider selling and Novo Nordisk competition anxiety.
Wall Street Sees 15% Upside. I Think They Are Underselling It
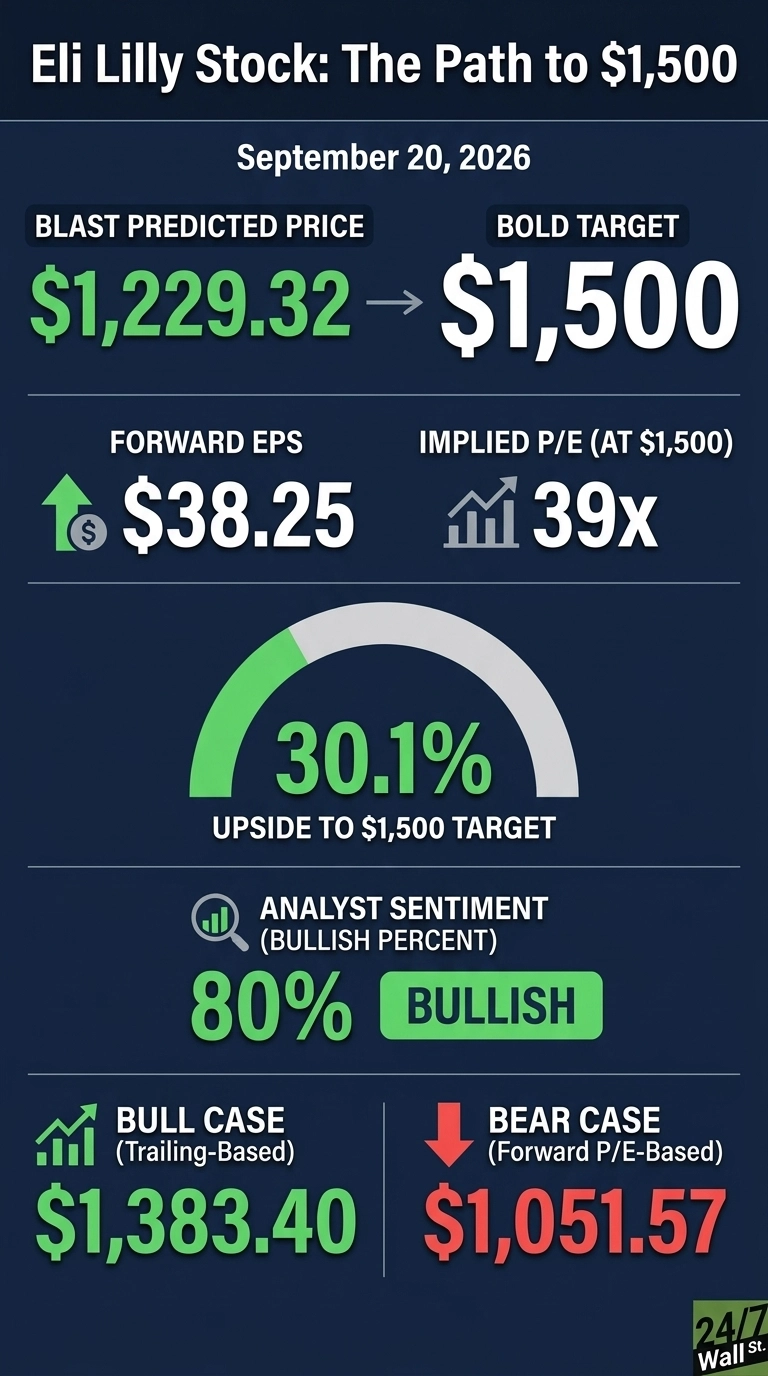
The Street’s consensus target is $1,325.39, implying roughly 15% upside from here. Coverage skews bullish: 6 strong buys, 18 buys, 4 holds, 1 sell, and 1 strong sell, with 80% bullish sentiment.
Our own model base case lands at $1,229.32 (a modest 6.63% upside) with the bull case at $1,383.40 and bear case at $1,051.57, at high confidence (0.9). Both look conservative to me.
With 19 upward EPS revisions for FY2027 in the last 30 days against just 4 downward, the analyst community is quietly repricing this business higher.

Path to $1,500 Per Share
Reaching $1,500 from today’s price of $1,152.93 would require a gain of 30.1%. With forward EPS of $38.25, a price of $1,500 implies a forward P/E of 39x. Our base case of $1,229.32 already implies 37x, meaning the bold target requires only 3x of additional multiple expansion.
That is a modest ask given the setup. The compression story is real: consensus FY2027 EPS sits at $47.32, up from $44.49 ninety days ago.
Catalysts are stacking: the August 28, 2026 FDA approval of Mounjaro for cardiovascular risk reduction, the September 18, 2026 approval of Inluriyo for ER+ breast cancer, and Ricks noting “really unprecedented efficacy with this triple acting GLP-1” ahead of the Q1 2027 retatrutide BLA submission.
The primary risk: any FDA setback on the retatrutide pathway could compress the multiple instead of expanding it.

Where LLY Trades Today vs Its Earnings Power
At $1,152.93 against forward EPS of $38.25, LLY currently trades at roughly 30x forward earnings. That is a reasonable multiple for a company growing revenue 47.67% year over year with 54.8% non-GAAP performance margins.
Shares sit near the 52-week high of $1,292.65, well off the 52-week low of $707.59. Ten-year returns of 1,587.78% tell you long-term compounders can absorb premium multiples when EPS growth keeps delivering.
Is $1,500 Realistic? My Verdict
Reaching $1,500 requires a 30.1% gain from here. I think it is realistic, provided three things happen: retatrutide clears the BLA pathway on schedule, Foundayo’s 36,000 prescriber base continues expanding, and FY2027 EPS estimates keep drifting toward the $54.94 high end.
What would derail it? A meaningful Novo Nordisk share-grab in obesity or a regulatory delay on retatrutide’s biologic classification. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Eli Lilly could reach $1,500 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.