The AI Software Story Wall Street Is Underrating
Salesforce's agentic AI business is scaling at a pace that would make most enterprise software companies envious, yet the stock keeps getting priced like a relic from the CRM era. Something in that gap looks like an opportunity Wall Street…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Salesforce (NYSE:CRM | CRM Price Prediction) has become the market’s favorite show-me story. The stock is down 9.6% year to date, yet the underlying agentic AI business is scaling faster than almost anything in enterprise software.
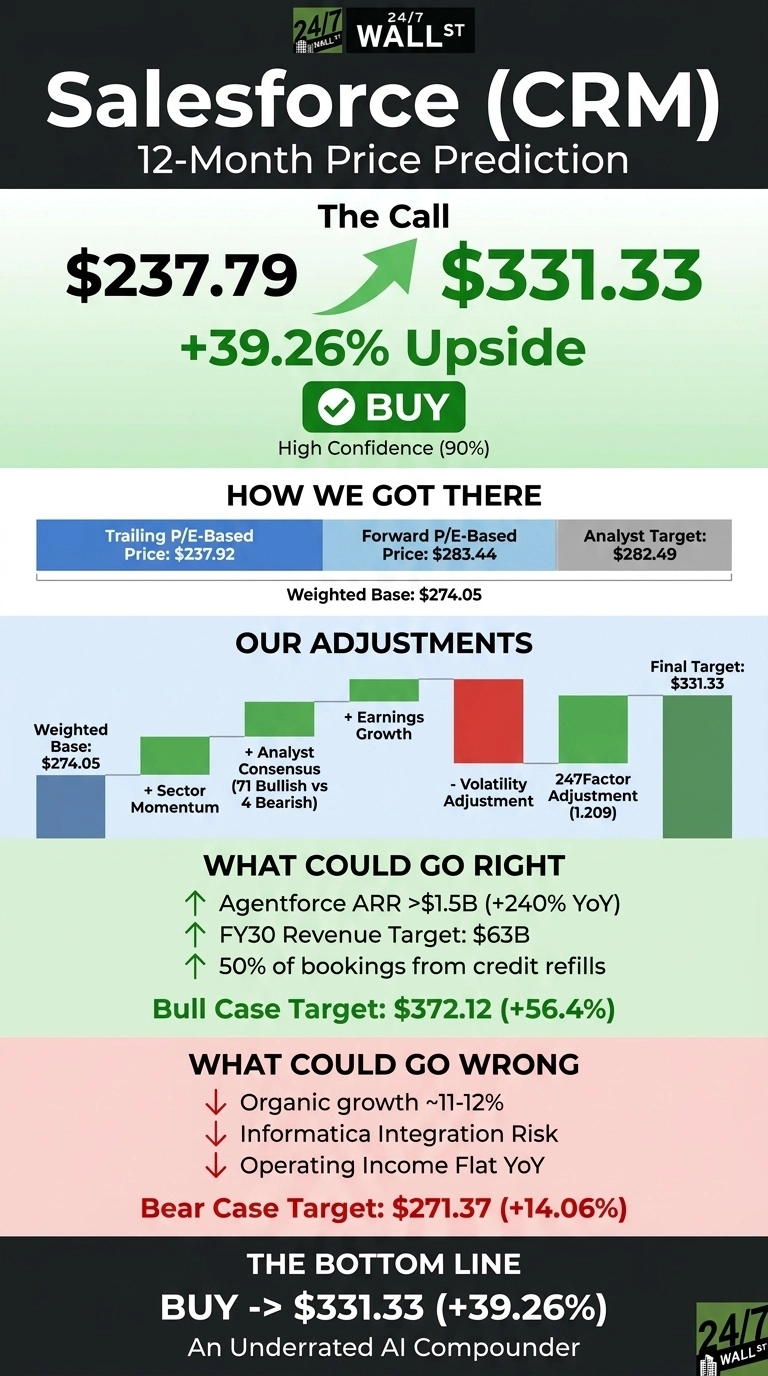
Our 24/7 Wall St. price target for Salesforce is $331.33, implying 39.26% upside from the current $237.79. We rate the shares a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $237.79 |
| 24/7 Wall St. Price Target | $331.33 |
| Upside | 39.26% |
| Recommendation | BUY |
| Confidence Level | 90% |

Agentforce Is Compounding Faster Than the Stock Reflects
Salesforce rallied 15.59% over the past month, but shares still sit well off the 52-week high of $267.80 and above the low of $146.06.
Q2 FY27 revenue landed at $11.35 billion, up 10.83%, and non-GAAP EPS of $5.90 topped the $3.2712 consensus by 80.36%. The Agentforce and Data 360 combined ARR reached nearly $3.90 billion, up over 210% year over year, while Agentforce ARR alone crossed $1.5 billion, up over 240%. Coverage from Barron’s after Dreamforce called the event a “small success” even as the stock fell.

Why Bulls See a Path to $370+
The bull case rests on monetization mechanics. Management noted 50% of Agentforce bookings came from customers refilling their credit pools, and only 5% of knowledge workers have upgraded to premium editions that carry a 60% to 80% premium. ClaudeForce, going generally available in September 2026, opens a second monetization surface.
FY30 revenue guidance of $63 billion anchors a durable double-digit trajectory. Our bull scenario points to $372.12, a 56.4% total return. As Marc Benioff put it, “AI isn’t replacing Salesforce. It’s unlocking more value across all four layers of our platform.”

What Could Go Wrong
Bears point to organic growth still tracking around 11% to 12% and heavy integration risk from Informatica, Contentful, and Fin. Restructuring charges jumped to $94 million versus $4 million a year ago, and operating income was essentially flat year over year.
Counterpoint: those pressures reflect deliberate reinvestment while free cash flow surged 81.49% and the diluted share count fell to 821 million from 962 million. Our bear scenario still lands at $271.37, a 14.06% gain.
How Salesforce Compares to Microsoft, Oracle, and ServiceNow
Microsoft (NASDAQ:MSFT) is the platform benchmark. It trades at a P/E of 27 with Azure growth of 43% and Q4 FY26 revenue of $90 billion, up 17.75%. Salesforce’s P/E of 26 is nearly identical for far less proven AI monetization at scale, making our CRM target look reasonable if Agentforce closes the perception gap.
Oracle (NYSE:ORCL) is the aggressive AI-infrastructure comp. Cloud revenue grew 62% in Q1 FY27, but free cash flow was negative $5.4 billion. Salesforce is generating cash while Oracle burns it, which argues our target is conservative on a quality-of-earnings basis.
ServiceNow (NYSE:NOW) is the growth counterpoint, with Q2 subscription growth of 24.5%, yet its stock is down 27.56% over the past year. That fade reinforces how much macro pressure has hit the group, and how much room CRM has if sentiment turns.
Salesforce Price Prediction 2026-2030
Our 24/7 Wall St. price target of $331.33 reflects an AI franchise the market is still pricing like a legacy CRM vendor.
The bull thesis holds as long as Agentforce ARR keeps compounding above 100% and premium-edition attach expands. The thesis weakens if organic subscription growth slips below 10% for two consecutive quarters.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $256 |
| 2027 | $332 |
| 2028 | $410 |
| 2029 | $482 |
| 2030 | $561 |
These projections assume Salesforce executes on its $63 billion FY30 revenue target. Significant upside or downside could come from ClaudeForce adoption or a broader software-spending slowdown.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.