Lilly’s Record Stock Price Is Hiding an Even Bigger Opportunity
Eli Lilly just delivered one of the biggest quarters in Big Pharma history, yet the stock sits well below its 52-week high. A closer look at the pipeline and valuation reveals why the real opportunity may still be ahead.


Eli Lilly (NYSE:LLY | LLY Price Prediction) just posted one of the most dominant quarters in Big Pharma history. Revenue grew 48% year over year to $22.974 billion in Q2 2026, Mounjaro alone brought in $9.943 billion, and management raised full-year EPS guidance to $35.50 to $36.50.
Shares closed at $1,156.73, up 8.16% year to date. Modest, given the numbers. So here is the question I want to answer: can Lilly reach $1,500 per share by late 2027?
Why Lilly Shares Have Stalled Despite Record Results
The chart does not match the business. LLY is down 7.23% over the last week and up only 0.83% over the past month, even after a blowout quarter. The stock sits below its 52-week high of $1,292.65, and with a beta of just 0.506, this is not a name that swings on sentiment alone.

Two things are weighing on the stock. First, U.S. realized prices fell 13% in Q2, and investors are nervous about payer pressure.
Second, Q2 included $2.78 billion in acquired IPR&D charges from a wave of deals. Reported EPS looks noisier than underlying earnings power, and the market is pausing to digest it.
Wall Street Sees Modest Upside. Our Model Sees More
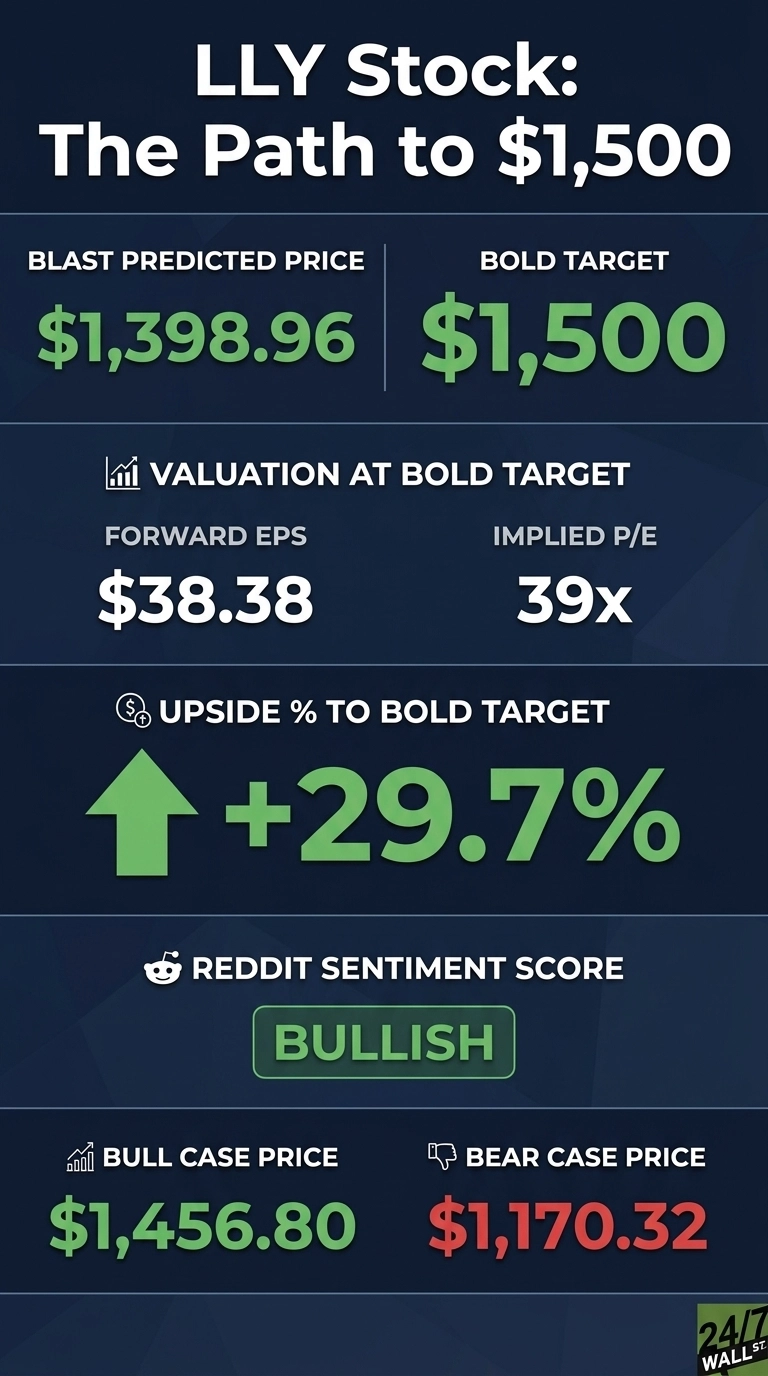
The Street consensus target is $1,315.04, split across 5 strong buys, 17 buys, 4 holds, 1 sell, and 1 strong sell. That is a bullish tilt, but the target implies only mid-teens upside from here. My valuation model lands at a base case of $1,398.96, with a bull case of $1,456.80 and a bear case of $1,170.32.

Confidence is 0.9, backed by a bullish analyst sentiment score of 79 and quarterly earnings growth of 26.2%. I think analysts are anchoring to today’s price disappointment rather than 2027 EPS power. That is the gap I want to exploit.
Path To $1,500 Per Share
Reaching $1,500 from today’s price of $1,156.73 would require a gain of 29.7%. With forward EPS of $38.38, a price of $1,500 implies a forward P/E of 39x. My base case of $1,398.96 already implies 36x, so the bold target needs roughly 2 to 3 turns of additional multiple expansion.

That is achievable if the pipeline delivers. Fresh catalysts sharpen the case: FDA approval of Mounjaro for cardiovascular risk reduction, positive Phase 3b data on Zepbound plus Taltz, and the Merida Biosciences acquisition. Retatrutide is the biggest lever.
CEO David Ricks put it plainly: “Lilly’s momentum continues, as we delivered 48% revenue growth and raised our full-year guidance.” The risk: any retatrutide setback or an accelerated payer pushback on GLP-1 pricing could stall the re-rating.
Where Lilly Trades Today Versus Its Earnings Power
At $1,156.73 against forward EPS of $38.38, Lilly trades near 30x forward earnings. That is a reasonable multiple for a company growing revenue 48% with gross margins of 85.8%.
Shares sit between a 52-week low of $707.59 and a high of $1,292.65, and the stock has returned 1,660.11% over 10 years. If 2027 EPS reaches the Street average of $47.23, the current multiple looks like a bargain.
Is $1,500 Realistic? My Verdict
Reaching $1,500 requires a 29.7% gain and roughly 39x forward earnings. Realistic, in my view, but not automatic.
Three things need to go right: retatrutide’s Q1 2027 BLA submission stays on schedule, Foundayo scales from its early inflection (36,000 prescribers already), and international incretin growth compounds on 2026’s 74% pace. A regulatory delay or a serious GLP-1 pricing shock would derail it. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Eli Lilly could reach $1,500 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.