3 Big Tech Stocks With the Most Upside Right Now
Wall Street has targets for Google, NVIDIA, and Salesforce, but one analyst thinks those numbers still leave serious money on the table heading into 2027. Here is the math behind three bold calls that could reshape how you size your…

Big tech’s 2026 has been a story of AI infrastructure spend meeting enterprise adoption. Let me walk through three names where the setup into 2027 still looks compelling: Google, NVIDIA, and Salesforce. Each gets a round-number bull target above Wall Street’s consensus, along with the math to back it up.
Google: A Path to $500 on Cloud Acceleration
Alphabet (NASDAQ:GOOG | GOOG Price Prediction) trades near $352.20, up 12.46% year to date and 39.95% over the last year. Wall Street’s average target sits at $422.34. My bold target is $500, which would put shares at roughly 34x the FY27 EPS consensus of $14.84.
That is a premium to the market’s 21x to 23x, but Q2 growth backs it up: revenue jumped 24%, Cloud accelerated to 82%, and cloud backlog hit $514 billion.
CEO Sundar Pichai said “we are in very early innings of what feels like secular shift.” With nearly 90% of Fortune 100 companies on Gemini Enterprise and TPU system sales just beginning to flow, $500 is ambitious but achievable.
NVIDIA: $350 Looks Reasonable on Vera Rubin
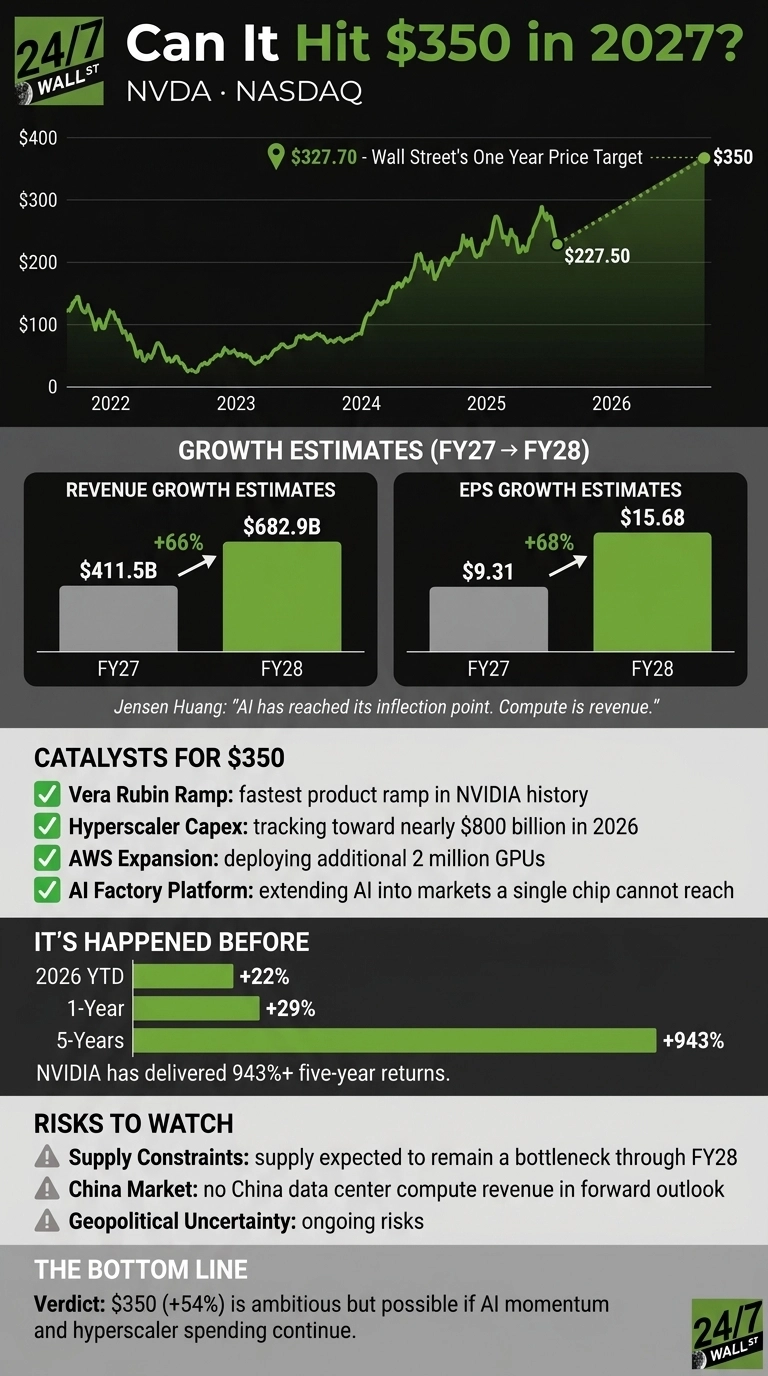
NVIDIA (NASDAQ:NVDA) sits at $227.50, up 22.27% YTD. Wall Street targets $327.70. My bold target: $350. At that price, NVIDIA would trade at roughly 22x the FY28 EPS consensus of $15.68, which has surged from $12.67 just 90 days ago on 42 upward revisions.
Q2 revenue more than doubled to $96 billion, and management guided FY28 growth of approximately 70%, calling it supply constrained. Jensen Huang put it plainly: “AI has reached its inflection point. Compute is revenue.”
AWS just committed to deploying an additional 2 million GPUs, and hyperscaler capex is tracking toward nearly $800 billion in 2026. NVIDIA has returned north of 943% over five years. A 54% run to $350 is well within its historical range.
Salesforce: $325 on Agentforce Monetization
Salesforce (NYSE:CRM) has lagged, down 9.6% YTD at $237.79. Wall Street’s average target is $282.49. My bold target is $325, which implies roughly 20x the FY28 EPS estimate of $15.99.
That is a modest multiple for a company whose Agentforce and Data 360 ARR is “about to cross $4 billion” with Agentforce alone at $1.5 billion ARR and bookings that doubled year on year. Q2 EPS of $5.90 topped the $3.27 estimate for a sixth straight beat.
CEO Marc Benioff argued “AI isn’t replacing Salesforce. It’s unlocking more value across all four layers of our platform.” With only 5% of knowledge workers on premium editions, the monetization runway is real.
Bottom Line on 2027 Upside
These targets require rallies of roughly 42% for Google, 54% for NVIDIA, and 37% for Salesforce. All three sit on rising estimates, multi-quarter beat streaks, and concrete AI catalysts already in motion.
The common thread is the infrastructure buildout behind them, and we profiled seven suppliers powering that boom, from power to cooling to networking, in a free report you can grab here. Returns of this magnitude remain rare, yet the blueprint for outsized 2027 gains is clearly on the table.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.