Salesforce Price Prediction: The Cheapest Way to Own AI Software
Salesforce trades at a fraction of what Microsoft and ServiceNow charge for AI growth, and that valuation gap is drawing serious attention. Whether it closes or widens depends on a bet most investors have not fully priced in yet.

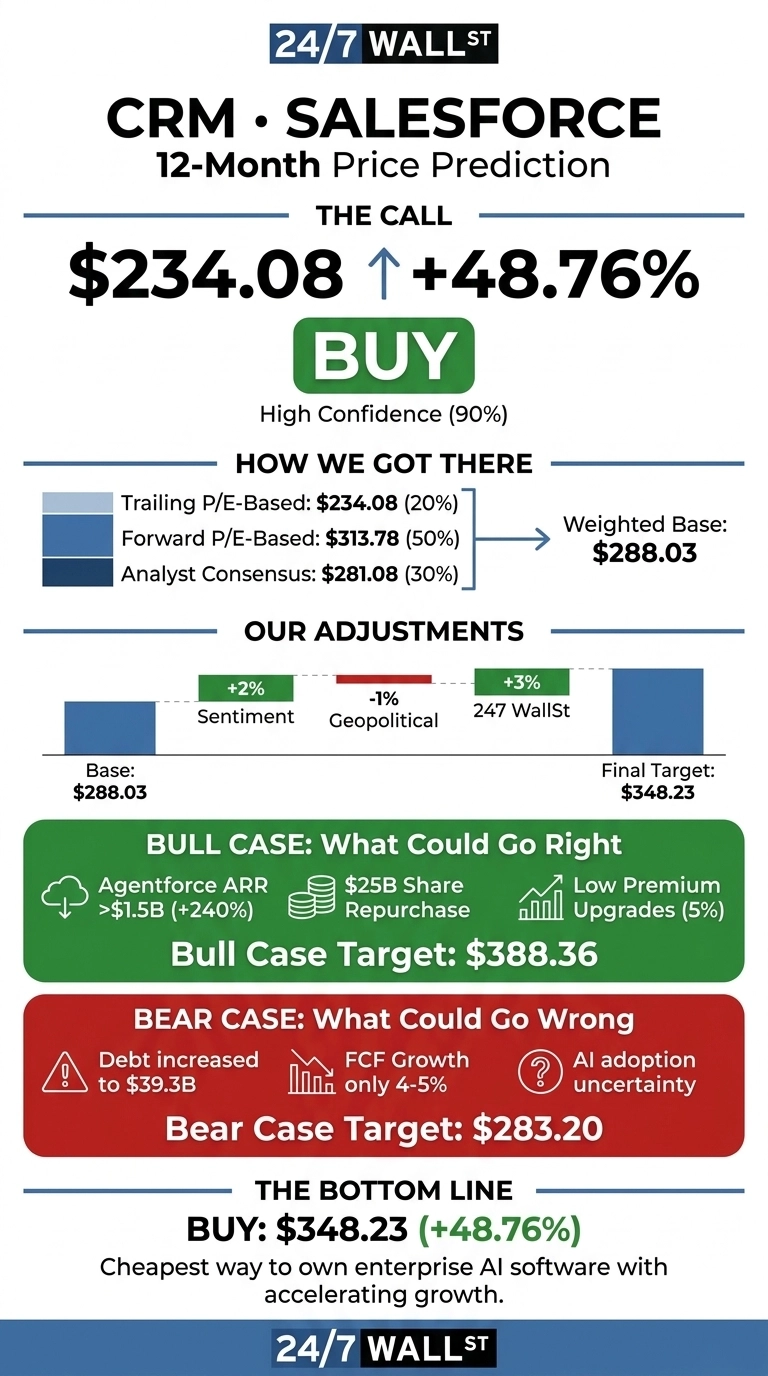
The 24/7 Wall St. price target for Salesforce (NYSE:CRM | CRM Price Prediction) is $348.23. The target implies 48.76% upside from the $234.08 close, and our model rates the stock a buy with high confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $234.08 |
| Price Target from 24/7 Wall St. | $348.23 |
| Upside/Downside | 48.76% |
| Recommendation | BUY |
| Confidence Level | 90% |
Salesforce trades at 14x forward earnings while combined Agentforce and Data 360 ARR reached nearly $3.9B, up over 210% year over year. Coupling hypergrowth AI revenue with a value multiple is why we see CRM as the cheapest way to own enterprise AI software.
A Post-Earnings Rally Still Leaves Salesforce Down for 2026
CRM gained 14.02% over the past month but slid 1.64% last week and remains down 11.04% year to date. Shares sit about 12.6% below the $267.80 52-week high and roughly 60.3% above the $146.06 low.
The Q2 FY27 earnings report on August 26 lit the trigger. Revenue of $11.345B rose 10.83%, exceeding the $11.316B consensus. Non-GAAP EPS of $5.90 beat the $3.27 estimate, although strategic investment gains added roughly $2.53 per share.
Management raised FY27 non-GAAP EPS guidance to $16.67-$16.71 from $14.06-$14.12. CEO Marc Benioff said, “We just delivered one of our best quarters ever.” At the September 16 Investor Day, Salesforce repeated its FY30 revenue target of $63B.

Why Bulls See $388 Within Reach
Agentforce ARR alone topped $1.5B, up over 240%. Only 5% of Sales and Service knowledge workers have moved to higher-end editions, which carry a 60% to 80% premium, so there is a long room for upgrades.
A $25B accelerated buyback at an average of $176 per share should cut diluted shares to about 821M from 962M. Our bull case lands at $388.36. Wall Street’s consensus target is $281.08, backed by 34 Buy and 6 Strong Buy ratings.

Debt and AI Pilots Could Cap the Upside
Noncurrent debt rose to $39.3B from $10.4B, restructuring charges reached $94M versus $4M, and FY27 free cash flow growth is guided to only 4-5%. Management also granted that many customers have only run pilot programs or failed experiments.
The counterpoint is that the debt paid for buybacks below today’s price, while net debt/EBITDA of 0.78 and 27.5x interest coverage still look healthy. The bear case of $283.20 sits above the current price.
Microsoft and ServiceNow Charge Far More for AI Growth
Microsoft (NASDAQ:MSFT) competes head-on with Salesforce, opposing Copilot against Agentforce. It trades at 25x forward earnings with 17.7% revenue growth.
ServiceNow (NYSE:NOW) is the closest pure play on agentic workflows. It grows faster at 24%, but trades at 28x forward and 85x trailing earnings.
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Salesforce | 14 | 10.8% |
| Microsoft | 25 | 17.7% |
| ServiceNow | 28 | 24% |
At our target, CRM would trade at about 23x forward EPS, which is still below both peers. The peer group makes the 24/7 Wall St. price target look reasonable.
Salesforce Price Prediction 2026-2030
Our 24/7 Wall St. price target of $348.23 carries a buy rating at 90% confidence. What tips the scale is a discounted multiple coupling with 14% cRPO growth.
The thesis gets stronger if organic revenue reaccelerates in the second half as management expects. It weakens if Agentforce deployments stall at the pilot programs stage or buyback-related leverage starts to pressure cash flow.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $348.23 |
| 2027 | $350.01 |
| 2028 | $458.81 |
| 2029 | $551.88 |
| 2030 | $621.41 |
These projections assume Salesforce keeps working toward its $63B FY30 revenue goal. Faster Agentforce adoption could push results higher, and a stumble integrating Informatica could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.