Berkshire Hathaway Now Owns Over 10% of This Beaten-Down Homebuilder
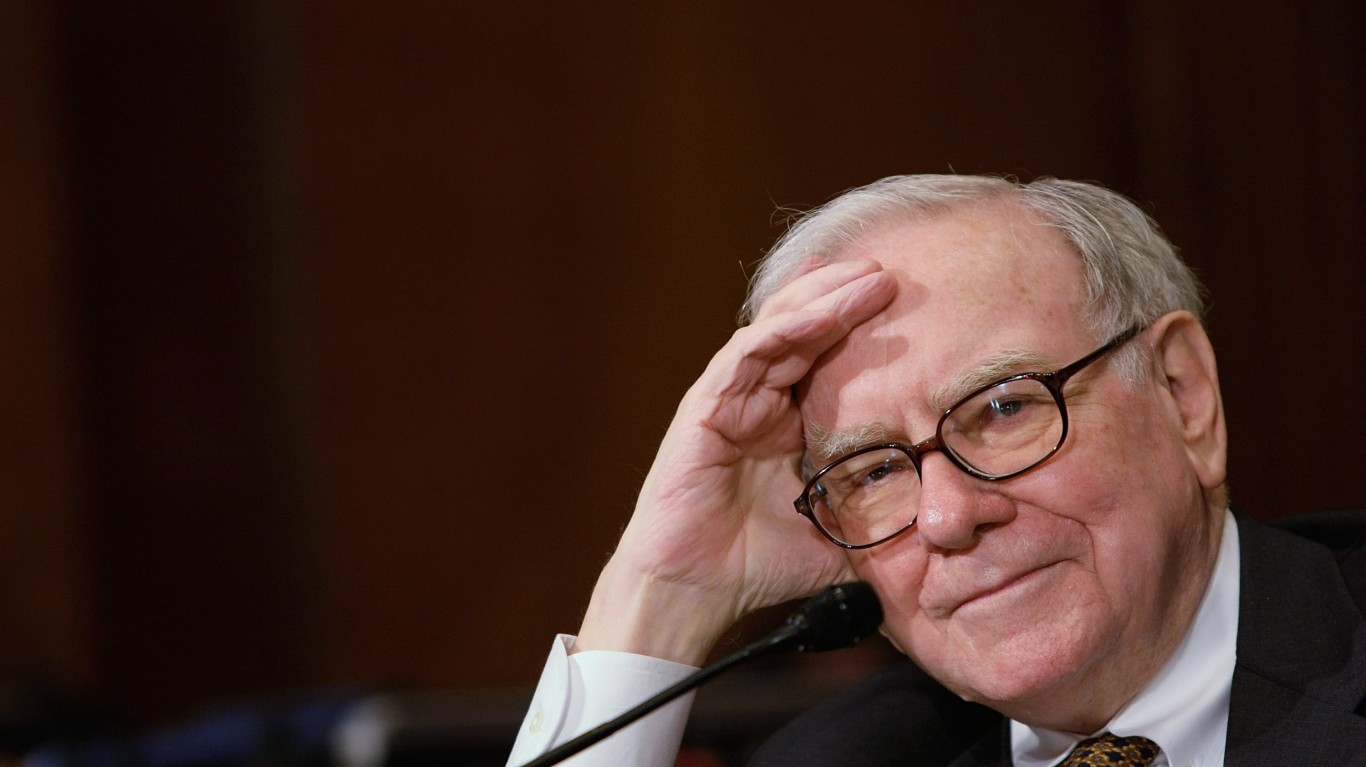
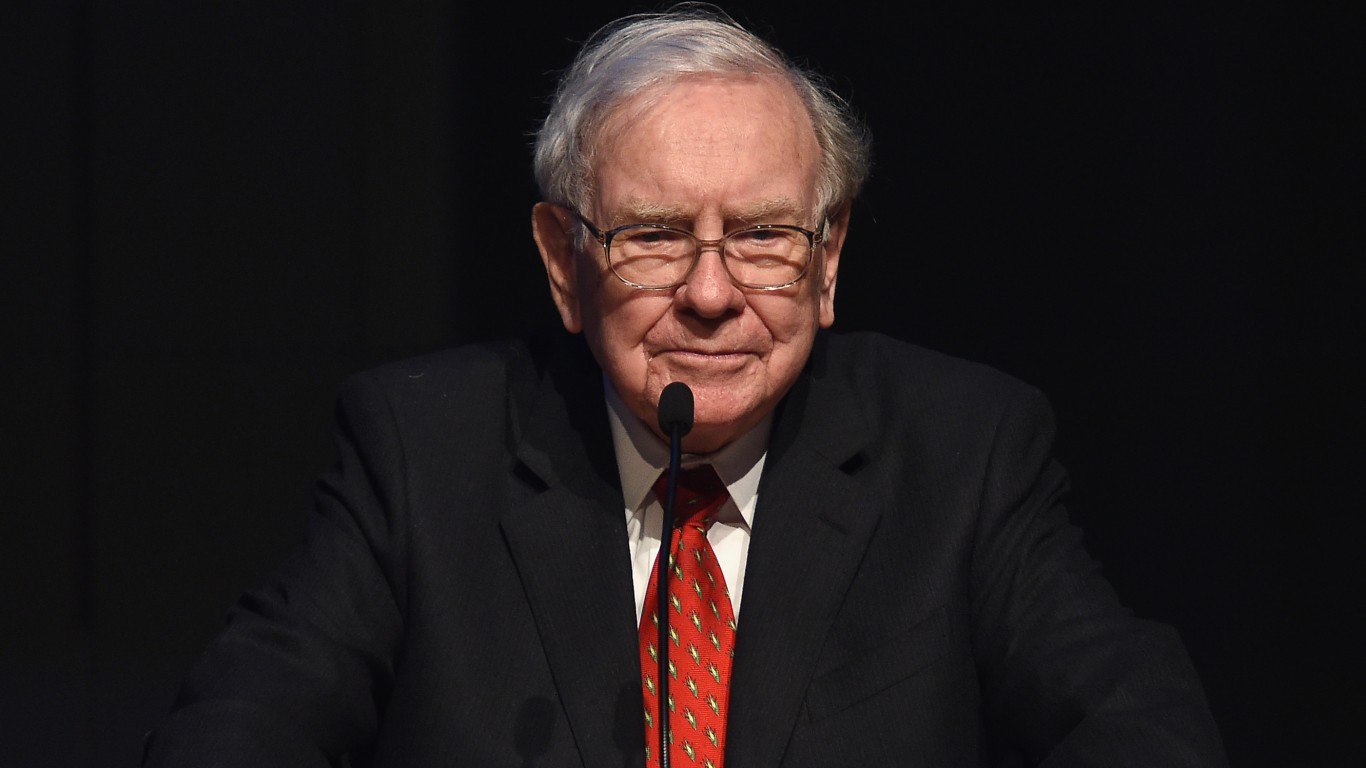
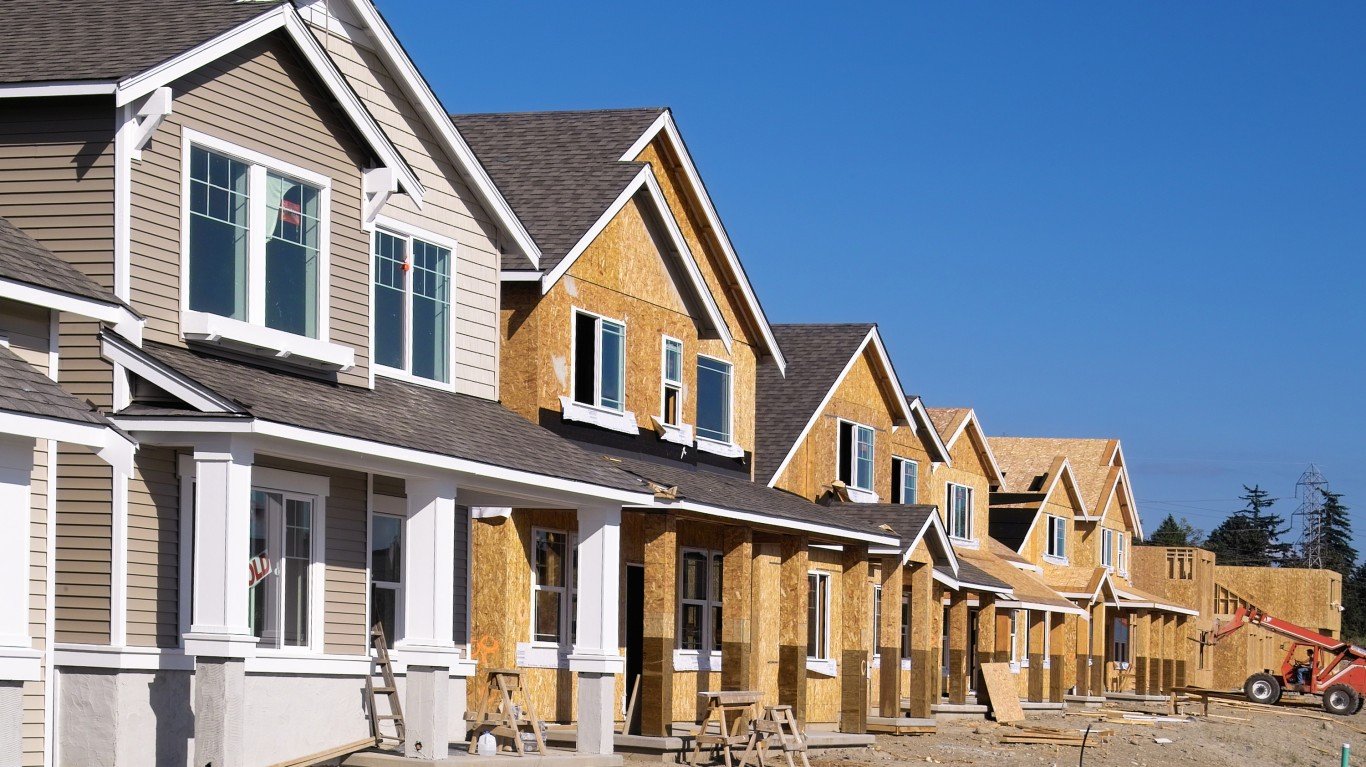
Warren Buffett just crossed a threshold in a beaten-down homebuilder that triggers mandatory insider reporting, and he did it while the company's own CEO admitted nearly half of visitors cannot qualify for a mortgage.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Berkshire Hathaway (NYSE:BRK-A | BRK-A Price Prediction, NYSE:BRK-B) crossed the ten percent ownership line in Lennar (NYSE:LEN), even though Lennar reported an earnings miss and cut its full-year delivery guidance. The stock jumped 6.35% in the September 22 session to close at $83.04 as the disclosure reached the market.
Mortgage rates are rising, consumer confidence is softening, and Lennar’s chief executive described a market that had “gotten more difficult since we last spoke in June.” Into that setup, the most patient buyer in the market crossed the 10% threshold. That valuation call may require a long wait.
What the Filing Shows

The SEC issuer roster now lists both Berkshire Hathaway and Warren Buffett as ten percent owners of Lennar. CNBC reported that Berkshire built almost a 10% stake.
Crossing 10% matters mechanically. The holder becomes an insider for reporting purposes and has to disclose subsequent transactions promptly, which is why we can see this now rather than in a delayed quarterly filing.
Q3 results were poor. Adjusted EPS came in at $1.23 vs. a $1.30 consensus; revenue was $8.05 billion, down 8.5% year over year; new orders fell 9% to 20,879 homes; and gross margin compressed to 15.8% from 17.5%. Full-year deliveries were cut to 80,000 to 81,000 from 82,000 to 83,000.

The chief executive said the 30-year rate was “approximately 6.8% at quarter end and even higher since” and, on the call, that “Almost 50% of our visitors cannot immediately qualify.” He also said Lennar was “not holding our breath or waiting for” rate cuts.
Operating Picture Under the Headline
Gross margin at 15.8%, up from 15.6% the prior quarter, with incentives running near 12%, shows price discipline rather than inventory dumping in a downturn.
Incentives at that level are the hidden discount propping up reported prices, so the pricing story is softer than headline margin suggests. The 6% move from September 16 through September 22 reflected the filing news rather than the underlying quarter.
The consensus analyst target sits at $80.08, below the current $83.04 price, with 8 Hold, 3 Sell, and 5 Strong Sell ratings against just 2 buys. The sell side thinks the current price is stretched.
Set that against the stock’s 17.94% year-to-date decline and 30.51% one-year drop. Berkshire is buying an asset a majority of analysts think is fully valued, and readers who like borrowing Buffett’s homework can see the cheapest dividend payers already inside the Berkshire portfolio in our free report. That is patient capital making a valuation call while the cycle is still deteriorating.

Bull and Bear Case for LEN Stock
Bull: A land-light builder with homebuilding debt to total capital of 16.6%, trading at a forward earnings multiple of 12 and 0.85 times book, bought in size by the most patient capital in the market. Housing shortages remain real, and the rate cycle will eventually turn.
Bear: Rates are rising, orders and deliveries are falling, and incentives remain elevated. The sell side thinks the stock is expensive while earnings continue to compress, and net income was down 51.96% year over year.
The deciding variable is the 30-year mortgage rate, and nothing management can do will move it. If rates roll back toward 6% before year-end, this position looks prescient. If they hold near 7% into 2027, Berkshire has the balance sheet to wait it out while most retail holders do not.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.