Jim Cramer Says Don’t Own a Single Bond Until Your 40s
Jim Cramer is telling younger investors to skip bonds entirely, and his reasoning has nothing to do with stock returns. The risk he says most people are ignoring could drain a retirement account long before the market gets a chance…

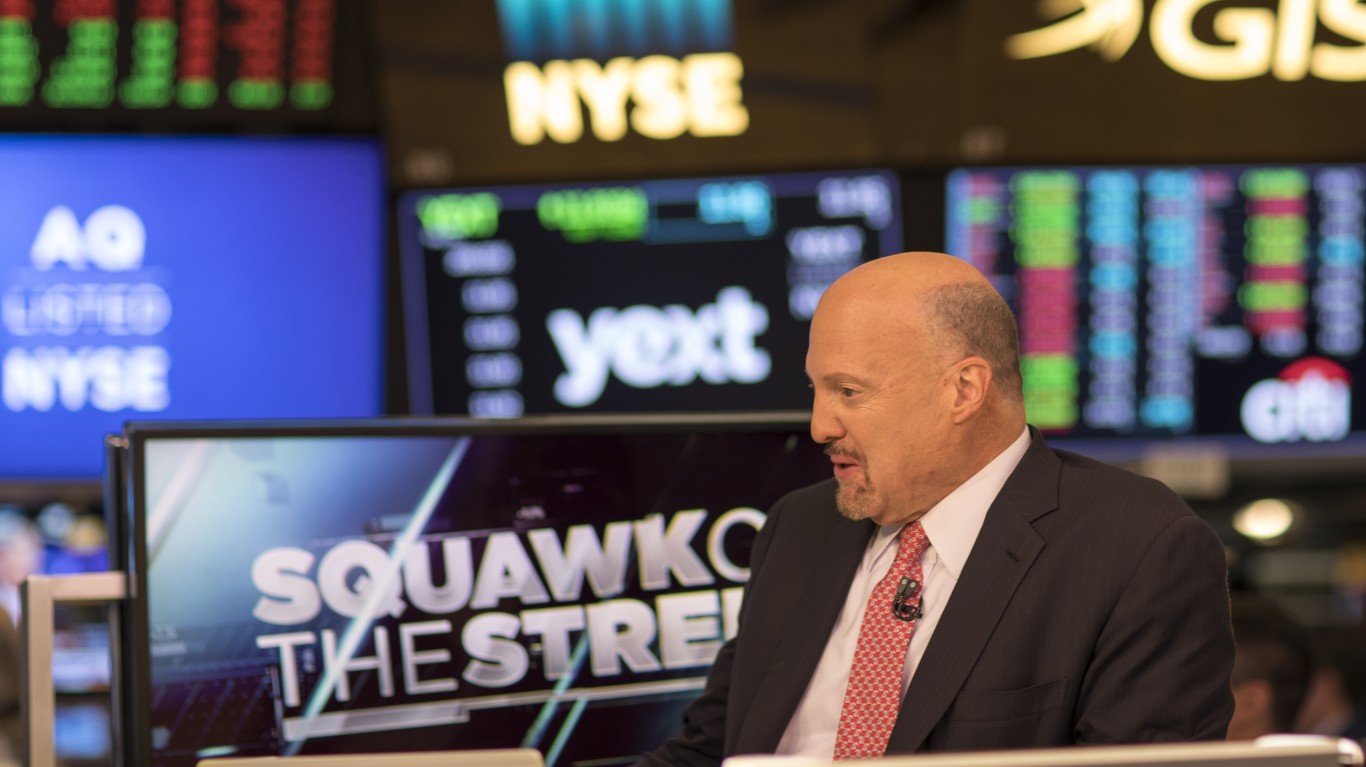
On Monday night’s Mad Money, Jim Cramer told viewers to avoid fixed income until midlife, framing the reasoning around a risk most allocation debates skip: the cost of eventual long-term care. Cramer said, “Only in your 40s do I want to introduce bonds to your portfolio. … If you have to go into a long-term care facility and you owned bonds for the previous 20 years, you’re not going to have enough money.”
For younger savers, the instruction was more aggressive. “Until you get to the late 20s at the earliest, I want you to take tons of risk, maybe more than you think you can handle, because you’ve got your whole life to make that money back if something goes wrong.”
Cramer argues that the risk savers spend decades hedging (market volatility) is smaller than the risk they ignore (running out of money because care costs drain the account). Cramer has said before that safe bond funds can quietly lose money over long stretches.
Why the Conventional Glide Path Exists
Traditional target-date design steps equity down and bonds up as retirement approaches. The point is to shrink the range of outcomes right when a saver loses the ability to work through a bad year. Sequence-of-returns risk is the technical name: a 30% drawdown in the first year of withdrawals damages a portfolio far more than the same drawdown ten years in. Bonds and cash exist in that mix to fund near-term spending so equities are not sold at a low. With the 10-Year Treasury yielding 4.96% as of September 21, 2026, the opportunity cost of that ballast is lower than it has been in years. The FDIC national average 12-month CD APY of 1.73% is a weaker comparison, though top online banks pay multiples of that.
What Savers Actually Hold
Vanguard’s How America Saves 2026 report shows how far most participants sit from Cramer’s stance. The average participant-weighted equity allocation was 79% in 2025, with a median of 89%. Participants under 25 held a median 91% in equities, ages 25 to 34 held 91%, ages 35 to 44 held 91%, ages 45 to 54 held 79%, ages 55 to 64 held 67%, and participants 65 or older held 50%.
Extreme allocations cluster among older do-it-yourself savers. Twenty-four percent of do-it-yourself investors held extreme portfolios (7% with no equities, 17% with 100% equities), and 27% of participants age 55 or older had equity exposure of either 30% or less or greater than 80%. Target-date funds have narrowed income differences: all participants, regardless of income level, had slightly more than three-quarters of their average account balance allocated to equities in 2025.
Where the Argument Holds, and Where It Breaks
Cramer’s point holds for two groups. Savers in their twenties who buy bonds because a plan menu nudged them there are almost certainly leaving compounding on the table. Savers with long time horizons and outside income who will not touch the account for decades can carry equity risk that a glide path would trim.
The framing breaks down for a saver whose withdrawal window starts inside the next five to ten years. That person cannot average out a drawdown. A retiree drawing 4% from a 90% equity portfolio in a down market locks in losses that a long-term care argument does not undo. (We walked through why those first few years of withdrawals set the tone for the whole plan in a free guide on defending them.) Long-duration Treasuries at current yields also pay real income while waiting, something bonds could not do in the last cycle.
Who This Framework Actually Suits
Cramer’s framework suits a 25-year-old with a paycheck and 40 years of contributions ahead. It is harder for a 62-year-old within striking distance of retirement, where the risk of a bad first decade of withdrawals is concrete. The care-cost concern warrants explicit planning with insurance or a dedicated bucket. Using it as the reason to hold no bonds for two decades before retirement asks one dollar to solve two problems, and one will get short-changed.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.