SpaceX Breaches $150 Again: Will the ‘Golden Dome’ Announcements Be Enough to Keep Prices Above IPO Levels?
SpaceX shares have punched through $150 twice now, fueled by billion-dollar defense contracts and a constellation no rival can match, but the balance sheet tells a story Wall Street may not be ready to hear.

At $154.72, SpaceX (NASDAQ:SPCX | SPCX Price Prediction) is a Hold, because the Golden Dome tailwind is real but the price has already run hard into it. Shares have reclaimed $150 for the second time since the IPO, and the question is whether defense catalysts can anchor the stock there.
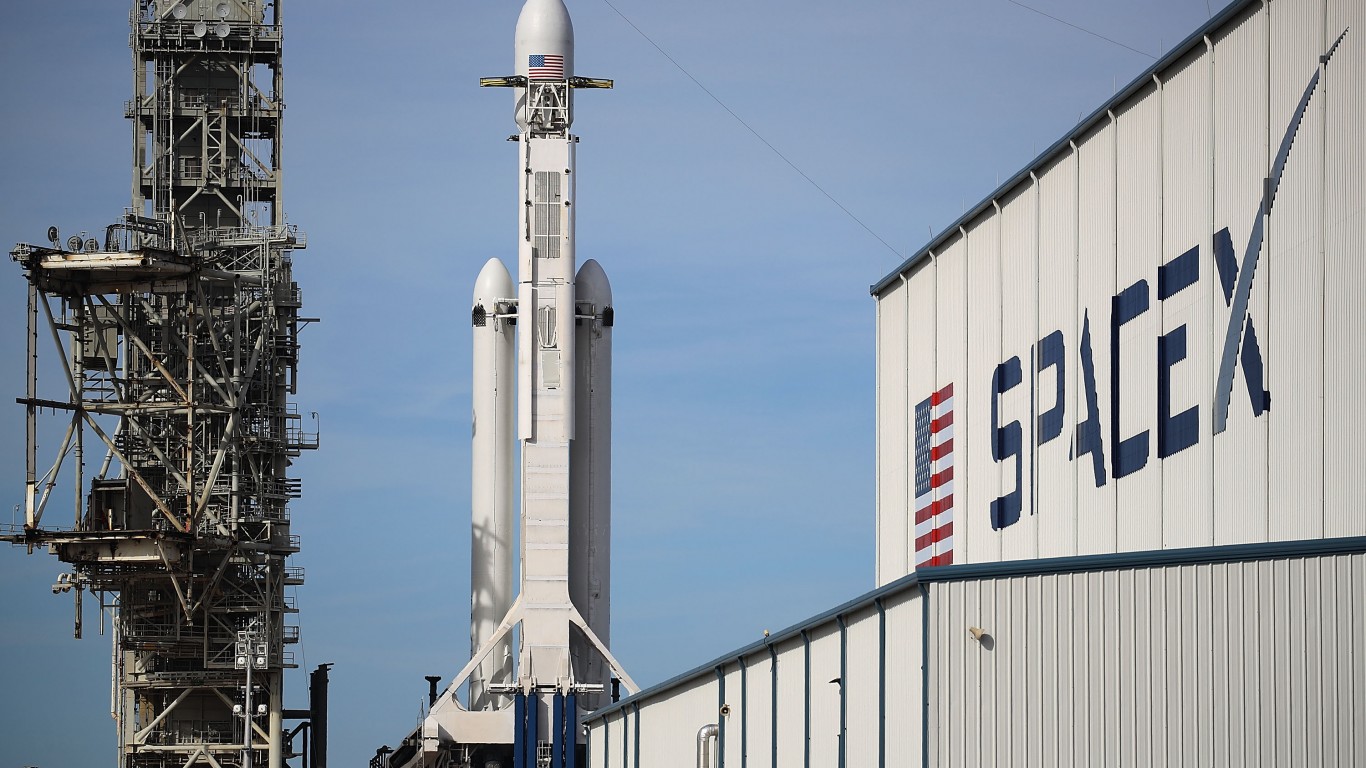
SpaceX operates three interlocking businesses: launch and Starship development, Starlink and Starshield connectivity, and AI anchored by Grok and the pending $60 billion Cursor acquisition. Total revenue grew 92% year over year in Q2 2026, with Connectivity at $4.29 billion and AI at $2.56 billion.
Golden Dome, funded at $17.9 billion in the FY 2027 defense budget, is the specific catalyst driving the re-rating. Starshield already holds over $6 billion in multi-year U.S. Space Force contracts for LEO communications and sensing.
Why Bulls See $150 Holding as a Durable Floor
The bull case rests on backlog and balance sheet. SpaceX carries a $47.5 billion contracted backlog and $93.52 billion in cash, with Adjusted EBITDA rising 191% year over year to $3.54 billion.
Golden Dome dollars run across space-based sensors, kinetic interceptors, and command-and-control, all areas where SpaceX’s launch cadence and constellation footprint create a structural edge. Add Starlink subscribers doubling to 12 million, new airline deals with American, Southwest, and Virgin Atlantic, and FCC approval of the EchoStar 65 MHz spectrum transfer, and the growth surface widens. Shares are up 7.83% over the past week and 12.96% over the past month.
Cash-Burn Concerns Behind the Trillion-Dollar Story
Bottom-line figures tell a harsher story. Operating income was negative $143 million and net income negative $541 million, with quarterly capex of $18.37 billion, of which $15.83 billion went to AI compute. That is defense-prime revenue with hyperscaler-level burn.
Starlink ARPU fell from $85 to $66 on international mix shift. The $60 billion Cursor deal layers integration risk on top of Starship losses, and procurement timelines rarely match a $1.19 trillion market cap that’s already fully priced. Over the past year, SPCX has fallen 3.87% while the S&P 500 rose 15.99%.
Why Patience Beats Conviction Ahead of Appropriations
Golden Dome dollars will flow, but the $17.9 billion FY27 request must survive appropriations and is spread across multiple primes. SpaceX’s Starshield share beyond the existing $6 billion book remains unquantified.
The next two quarters offer clarifying tests: the Cursor close, Starship V3 flight cadence, and Starlink ARPU stabilization. Any one going wrong justifies waiting; all three going right justifies chasing.
What Prediction Markets and Momentum Actually Show
SPCX currently trades at $154.72, up 1.89% on the session, against an S&P 500 that finished essentially flat at 773.44. Over the past month, SPCX has advanced 12.96% versus 1.01% for the benchmark.
Polymarket’s September contract puts the $160 outcome at 0.635 probability, while the weekly close market leans toward the $150 to $155 range. Composite sentiment reads 53.58, neutral with medium confidence.
Verdict on SpaceX at $154.72
At $154.72, SpaceX is a Hold. Here is why.
The stock cleared $150 on legitimate news flow, but it is doing so with a $1.19 trillion market cap that already assumes Golden Dome dollars, Starship success, and Cursor accretion. The bull case is simply early. The bear case is simply impatient.
Conditions that would flip this to a Buy: a signed follow-on Starshield award, Starlink ARPU stabilization, and a clean Cursor close in Q3 2026. Conditions that would flip it to a Sell: a Starship V3 setback, Cursor repricing, or a Golden Dome appropriations cut. Track Space Force contract announcements, Starship test cadence, and Q3 ARPU and free cash flow.
Patience is defensible here because SPCX is fully valued for catalysts already announced, and the next real information event is still one quarter away.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.