Amazon Stock Could Have Another Big Run Ahead. Here’s My 2027 Price Prediction
AWS is booming, custom silicon is fully subscribed, and Wall Street has loaded up on buy ratings, but the real question is whether Amazon can clear a target that even the bulls have not fully priced in.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Amazon (NASDAQ:AMZN | AMZN Price Prediction) has emerged as one of 2026’s steadier mega-cap performers. Shares are up 10.24% year to date, trading around $254.46, after AWS reaccelerated to its fastest growth in 18 quarters and both the AI and custom chips businesses eclipsed $25 billion annualized run rates.
CEO Andy Jassy told investors AWS is “booming right now” and could eventually become a trillion dollar annual revenue business. I want to walk through what it would take for Amazon to reach $350 per share in 2027.

Wall Street Sees Meaningful Upside Into 2027
The Street is firmly bullish. The consensus analyst target sits at $329.20, with 15 strong buys, 44 buys, 2 holds and zero sell ratings. Analysts model 2027 revenue of roughly $946.8 billion and EPS of $10.47 from 52 contributing analysts, with the high end reaching $15.04.
The 2027 EPS average has climbed from $9.96 ninety days ago, with 8 upward revisions against just 1 cut in the last 30 days. Amazon has beaten EPS expectations by 60.69% in Q1 and 26.62% in Q3 FY25, so 2027 results have a real shot at landing above consensus.
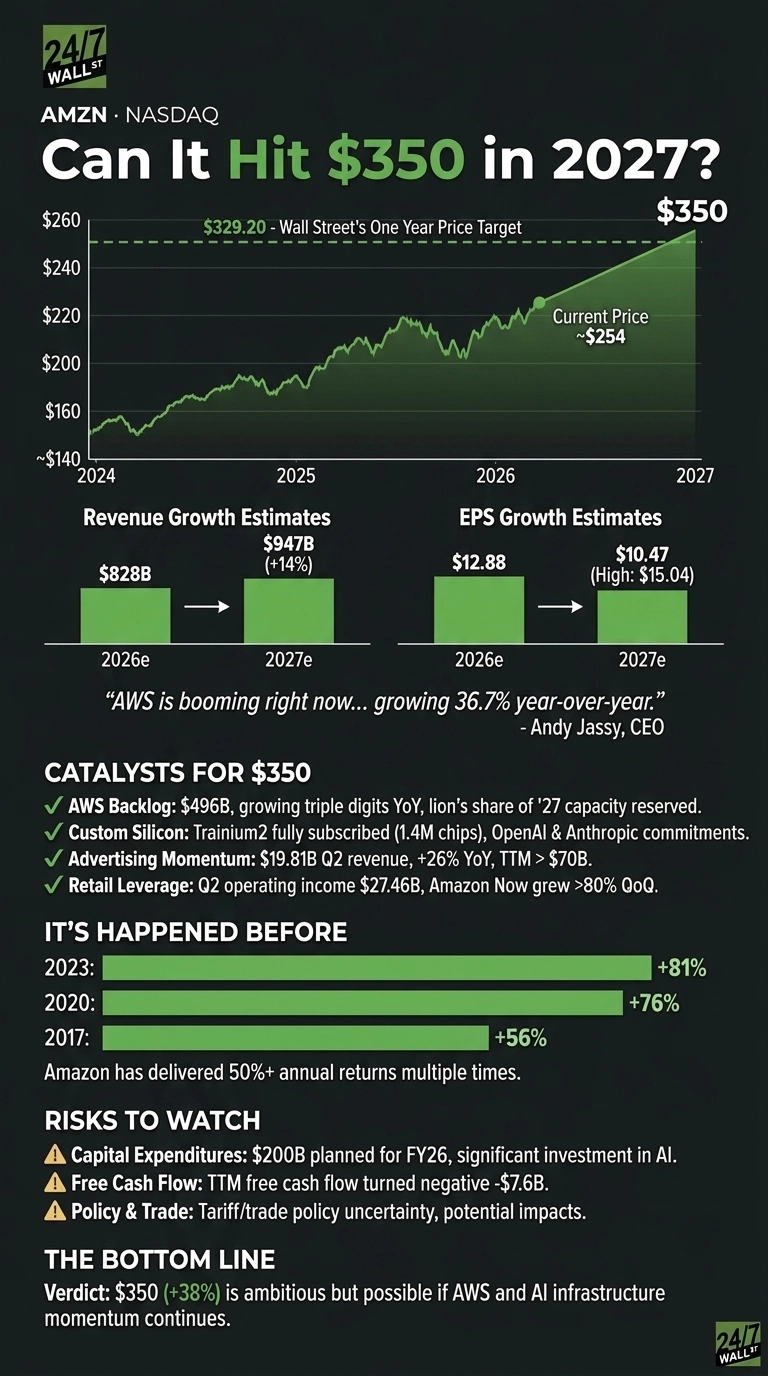
Path to $350 Per Share
At $254.46, Amazon trades at roughly 24x forward earnings. If shares hit $350 against the current 2027 EPS estimate of $10.47, that would be about 33x.
At the high-end analyst EPS of $15.04, $350 is only 23x, in line with the S&P 500’s forward multiple. That is a reasonable multiple for a business compounding operating income at 43.2% year over year last quarter.

What could push Amazon to $350?
- AWS backlog conversion. Backlog stands at $496 billion, growing triple digits year over year, with “the lion’s share of capacity in 27” already reserved.
- Custom silicon. Trainium2 is fully subscribed at 1.4 million chips. Trainium4 launches in 2027 with 6x FP4 performance versus Trainium3. OpenAI has committed to roughly 2 GW of Trainium capacity starting 2027, and Anthropic is securing up to 5 GW.
- Advertising momentum. Ads hit $19.81 billion in Q2, up 26%, with a trailing base above $70 billion at far higher margins than retail.
- Retail leverage. Q2 operating income of $27.46 billion shows the cost curve bending as Amazon Now grew over 80% quarter over quarter.
- Rising estimates. The 2026 EPS average has jumped from $8.68 ninety days ago to $12.88, a pace that historically drags share prices along.

Amazon Has Made Runs Like This Before
Getting from $254 to $350 is roughly a 38% move. Over the last decade, Amazon has returned 531.61%, with 50%-plus gains in 2015, 2017, 2020 and 2023 as AWS and advertising ramped.
The five-year window shows a 50.57% total return. A 38% year is well within Amazon’s range when AWS is accelerating.
My Take on $350
Reaching $350 in 2027 would require roughly 38% upside from today.
The setup is credible: Wall Street targets $329.20, 2027 estimates are climbing, AWS backlog is at a record $496 billion, and Trainium4 arrives as hyperscale AI budgets shift into monetization mode.
All of that capacity still has to be powered, cooled, and networked by somebody, and we profiled seven of those suppliers in a free report on the AI infrastructure buildout. Offsets include $200 billion of planned 2026 capex and near-term free cash flow pressure. I’ve outlined the blueprint for how Amazon could deliver an outsized 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.