This Magnificent Seven Stock Could Reach a New All-Time High
AWS just posted its fastest growth in 18 quarters and CEO Andy Jassy is talking about a trillion-dollar revenue business, yet the stock sits well below where our model says it should be trading.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
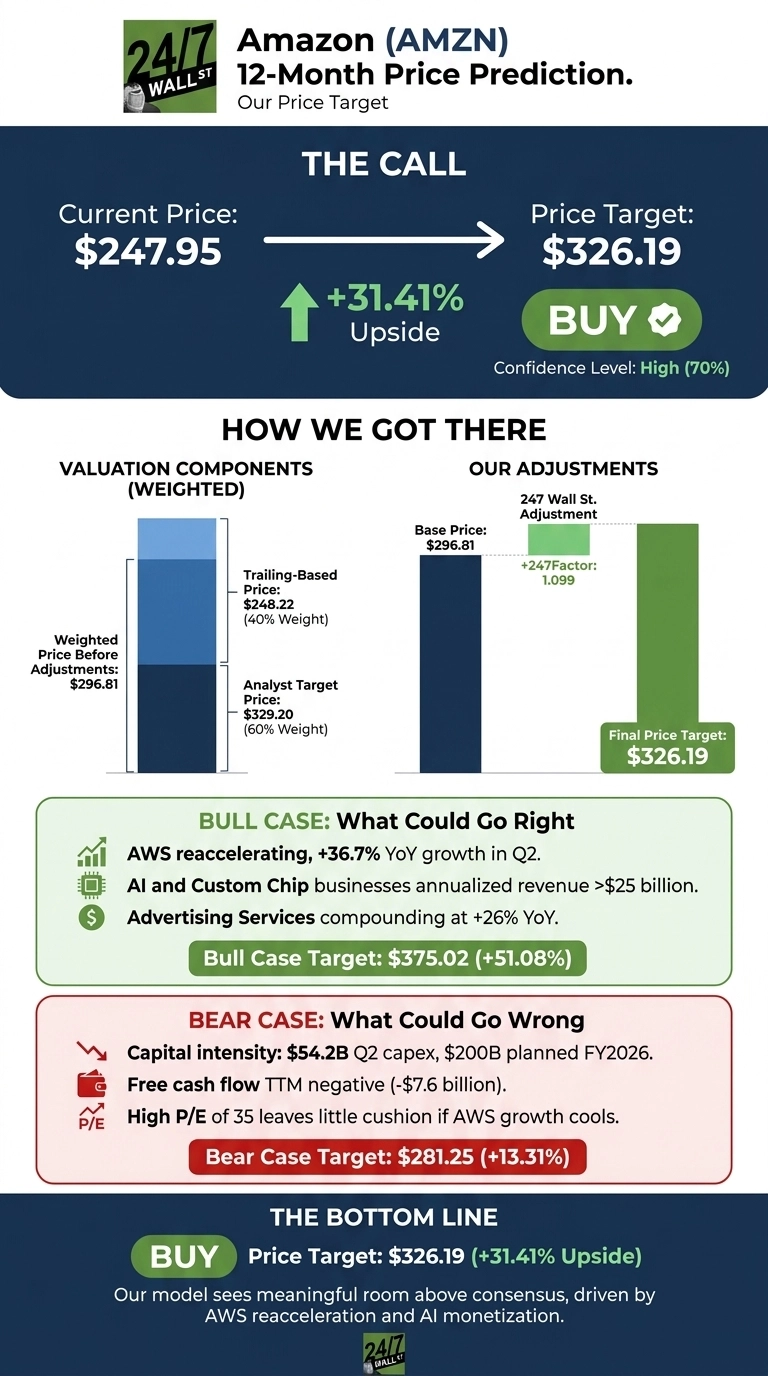
Amazon (NASDAQ: AMZN | AMZN Price Prediction) trades at $247.95. Our 24/7 Wall St. price target is $326.19 over 12 months, implying 31.41% upside and fresh all-time-high territory. Recommendation: Buy with 70% confidence. AWS is reaccelerating, advertising is compounding, and the model sees meaningful room above consensus.
| Metric | Value |
|---|---|
| Current Price | $247.95 |
| 24/7 Wall St. Price Target | $326.19 |
| Upside | 31.41% |
| Recommendation | BUY |
| Confidence Level | 70% |

AWS Reacceleration Is Rewriting the Narrative
Shares are up 7.42% year to date and 12.34% over the past year, though they have slipped 5.39% over the last month.
The catalyst behind the underlying strength was Q2 FY2026, reported July 30, 2026. Revenue of $200.6 billion grew 19.62% year over year, AWS jumped 36.7% (its fastest growth in 18 quarters), and advertising climbed 26% to $19.8 billion. CEO Andy Jassy said “AWS is booming right now,” and the AWS backlog now sits at $496 billion.
Why Bulls See a Breakout Above $375
The bull case centers on AI monetization. AWS AI revenue and Amazon’s custom chip business each cleared $25 billion annualized run rates with triple-digit growth.
Jassy said AWS could “very possibly be a trillion dollar annual revenue business for us in time.” The bull scenario points to $375.02, a 51.08% gain. Wall Street consensus is $329.20 with 59 buy or strong-buy ratings versus 2 holds.

What Could Go Wrong
Capital intensity is the counterweight. Amazon spent $54.2 billion on capex in one quarter and guided to roughly $200 billion for 2026. Trailing free cash flow is -$7.6 billion.
Bears cite a trailing P/E of 35 as leaving little cushion if AWS growth cools. Jassy countered that servers break even in less than three years and data centers monetize for 30-plus years. The bear case still projects $281.25, a 13.31% gain.

How Amazon Compares to Microsoft, Alphabet, and Walmart
Microsoft (NASDAQ: MSFT) is the closest cloud comparable. Azure grew 43% last quarter and trades at a P/E of 28.
Alphabet (NASDAQ: GOOGL) posted the highest cloud growth of the group at 82%, yet trades at just 15 times earnings.
Walmart (NYSE: WMT) is the retail counterweight, growing eCommerce 23% but priced at a P/E of 40.
What to Watch Next
The $326.19 target with a buy recommendation and 70% confidence reflects real conviction. The bullish thesis strengthens if AWS growth holds at 35% or better through Q3 and Bedrock spend climbs. It weakens if free cash flow deteriorates without visible AI capex monetization. The AWS reacceleration is the primary factor supporting the model’s constructive stance.
The buildout behind that AWS backlog has to be powered, cooled, and networked by someone, and we profiled seven companies riding that infrastructure wave in a free report you can grab here.
Amazon Price Prediction 2026-2030
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $259.80 |
| 2027 | $325.94 |
| 2028 | $403.48 |
| 2029 | $444.45 |
| 2030 | $500.74 |
These projections assume Amazon continues executing on AWS and AI monetization. Significant upside or downside could result from the pace of AI infrastructure returns and consumer-spending trends in the core Stores business.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.