Analysts Warn the Entire Space Trade Is Sitting in Neutral Waiting on One Rocket
Every space supplier building lunar modules, satellite hardware, and heavy components is betting its revenue timeline on a rocket it does not own, and the gap between two stocks tells you exactly how the market is scoring that bet.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
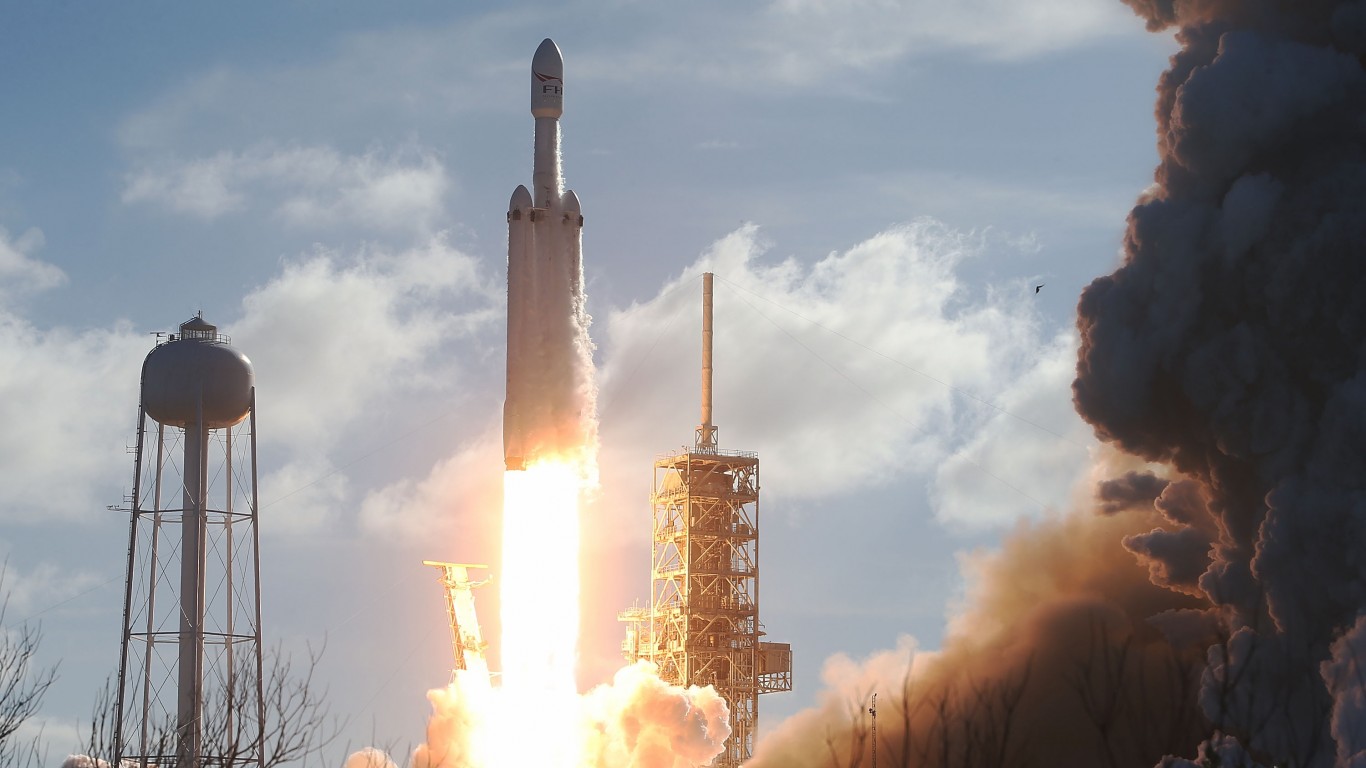
The space complex has spent 2026 waiting on SpaceX’s (NASDAQ:SPCX | SPCX Price Prediction) Starship to become operationally reliable. Companies building lunar modules, satellite hardware, and heavy space components are “sitting in neutral” until that happens, a dependency that runs through NASA and Department of Defense roadmaps.
Two publicly investable names in that supply chain, Redwire (NYSE:RDW) and Karman Holdings (NYSE:KRMN), reported strong quarters and are trading in opposite directions. Redwire is up 48.16% year-to-date at $11.26. Karman is down 54.8% year to date at $33.07, including a 35.62% drop over the past month. The market is pricing these as separate trades.
Why a Rocket Delay Becomes a Revenue Delay
When the only vehicle sized for a class of missions is still qualifying, downstream contracts slip.
Redwire made this dependency explicit in its Q2 call. Its SpaceMD venture agreed to purchase an entire SpaceX Starfall spacecraft, with the first mission slated for launch in 2028 carrying up to 32 pillboxes.
CEO Peter Cannito called the platform “a game changer” for microgravity manufacturing, but revenue timing depends on SpaceX’s launch manifest.
Karman’s space and launch segment grew only 6% year over year in Q2 to $42 million, which management attributed to “customer order timing associated with shifting launch schedules.”
Who Actually Captures the Scarcity Premium
When orbital capacity is tighter than demand, the launch owner sets the price. A component supplier signed contracts against different assumptions and cannot easily reprice its customers.
Redwire and Karman both sell into a market where whoever owns the rocket collects the scarcity rent, and the payload builder absorbs the margin compression, because neither operates a heavy-lift vehicle.
Redwire’s Q2 gross margin of 27.8% shows how thin the payload side can run.
Aggressive Timelines Are a Shareholder Problem
The Motley Fool Money guest observed that “Elon Musk likes to set aggressive deadlines and then not hit them,” citing the Tesla Roadster promised for 2017 that still has not shipped.
If your investment thesis assumes a working heavy-lift vehicle by a given fiscal year, you are underwriting somebody else’s cadence.
NASA and Defense Department programs tied to Starship raise political urgency to fix delays, though procurement decisions outside these suppliers’ control can rewrite the same customer roadmaps.
Karman and Redwire Diverge Sharply
Karman is defense-weighted. Tactical Missiles and IDS grew 55.4% in Q2, Hypersonics and Strategic Missile Defense grew 24.2%, and backlog hit $1.30 billion, providing 95% visibility to full-year guidance.
CEO Jon Rambeau cited “more than $90 billion in recent prime contractor awards for THAAD and PAC-3 interceptors and over $76 billion for new Columbia and Virginia class submarines” as the demand backdrop.
Redwire’s Defense Tech segment contributed $61.88M in Q2, with Space at $55.19 million. Its record contracted backlog of $542.13 million is smaller than Karman’s, and its Space segment is more directly tethered to commercial orbital access. Filing details are in the company’s Q2 2026 earnings exhibit.
Bull and Bear Case for RDW Stock
The bull case rests on a diversified space and defense platform with government-funded backlog independent of any single launch vehicle. The $1.8 billion Andromeda IDIQ spacecraft award and $44 million DARPA Otter Phase 2 contract anchor multi-year Space revenue independent of Starship’s schedule.
Liquidity of $607.80 million against debt of $48.9 million gives Cannito room to acquire, invest, and absorb the execution volatility the company itself flagged.
The bear case is a supplier whose growth is gated by transport it does not own, into a market where the launch owner captures pricing power. TTM diluted EPS is -$1.22, and the analyst target of $14.69 sits above the current price without pricing in another Starship slip.
The deciding variable is a reliable heavy-lift cadence. Until that exists, the downstream contracts that justify Redwire’s Space multiple cannot convert on schedule.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.