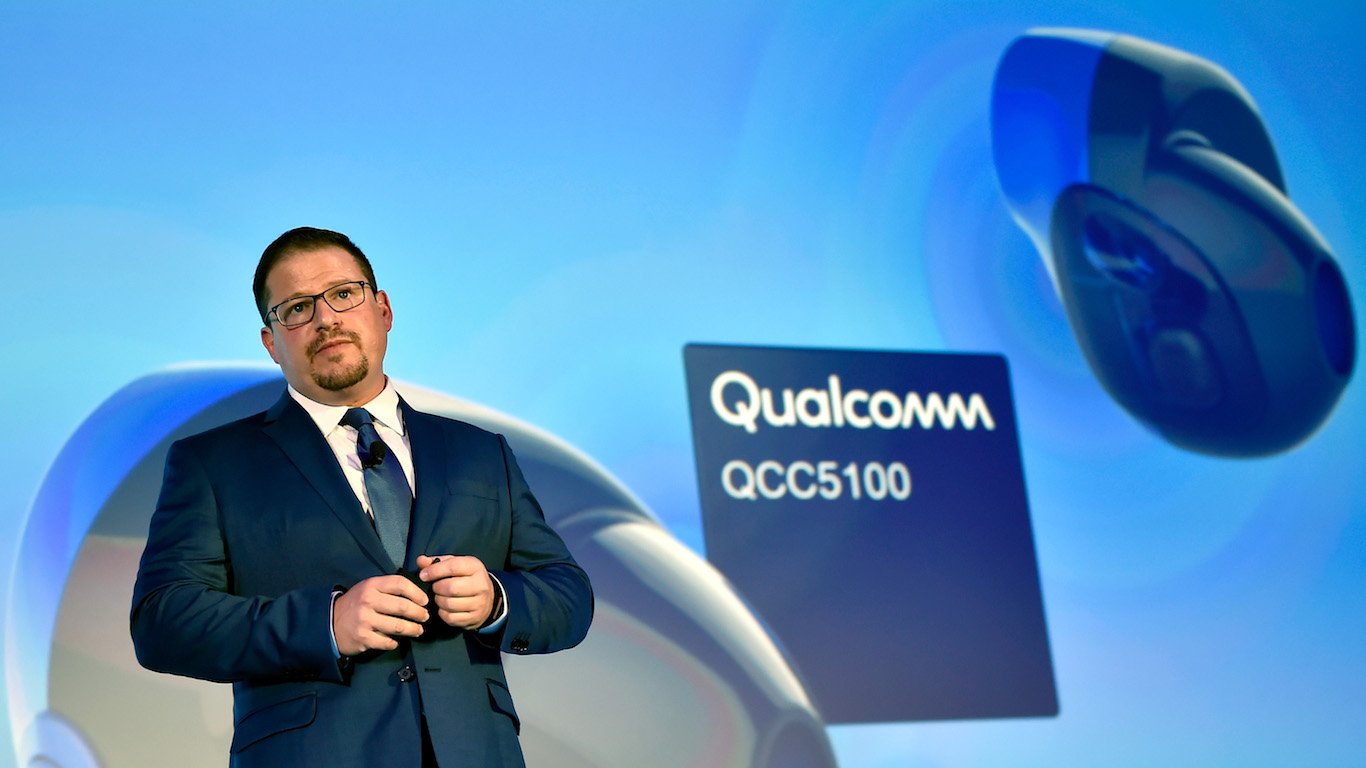
Qualcomm or Cisco: One Dividend Will Outpace the Other From Here
Qualcomm and Cisco both raise their dividends every year and both are racing into AI infrastructure, but their capital allocation priorities point in completely different directions for a retiree who needs the income to be reliable.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
If a retirement-focused investor has room for exactly one mature tech dividend, does Qualcomm (NASDAQ:QCOM | QCOM Price Prediction) or Cisco Systems (NASDAQ:CSCO) belong in the account? Both pay quarterly, both raise regularly, and both are pivoting hard into AI infrastructure. But the income profiles are less similar than the surface suggests, and one of these dividends is structurally better suited to funding retirement cash flow.
Yield and Payout Coverage
Qualcomm offers the fatter headline number. The stock yields 1.85% at a share price of $195.54, paying $0.92 per share quarterly with a forward annualized payout of $3.68. Cisco yields 1.49% at $105.79, paying $0.42 quarterly, or $1.68 annualized.


Coverage tells a fuller story. Qualcomm produced FY25 free cash flow of $12.82 billion against $3.8 billion in dividends paid. Cisco returned $12.7 billion to shareholders in FY26, representing 99% of free cash flow, of which $6.6 billion went to dividends. Qualcomm has more cushion on paper. Winner: QCOM.
Dividend Growth Track Record and Future Path
Cisco just recorded its 15th consecutive year of dividend increases, moving from $0.41 to $0.42 in early FY26. Qualcomm has raised annually as well, taking the quarterly payout from $0.85 to $0.89 in March 2025, then $0.89 to $0.92 in March 2026, with a long-term progression from $0.05 in 2003 to $0.92 in 2026.
Qualcomm’s recent raises have been larger in percentage terms, but the forward path is where Cisco pulls ahead. Cisco is guiding FY27 revenue of $72.2 billion to $73.4 billion and non-GAAP EPS of $5.05 to $5.11, with AI infrastructure revenue expected to roughly double to $7.5 billion. Qualcomm, meanwhile, is absorbing a 20% year-over-year handset decline, with Apple product revenue expected to fall approximately 50% from September to December quarter. The data-center pivot is real, but management admits the segment will run 1.5% to 2% below baseline gross margin. Cisco’s dividend base is compounding off a growing business today; Qualcomm’s is compounding off one under active repair. Winner: CSCO.


Capital Return Priorities
Look at where the cash actually goes. Qualcomm’s FY25 capital return of $12.6 billion split $3.8 billion in dividends against $8.8 billion in buybacks, roughly a 30/70 ratio favoring repurchases. That skew continued in Q3 FY26: $937 million in dividends versus $1.4 billion in repurchases. Cisco’s FY26 split was $6.6 billion dividends versus $6.1 billion buybacks, nearly even, with $8.1 billion remaining on the buyback authorization.
For a retirement account funded by dividend income, the priority signal matters. Cisco’s capital plan treats the dividend as a co-equal obligation. Qualcomm treats it as one of two levers and pulls the buyback harder when management sees value. Winner: CSCO.


Verdict
Cisco is the better retirement income holding, and it is not particularly close on the criteria that matter most to a retiree. A documented 15-year raise streak, a capital allocation policy that actually prioritizes the dividend, and forward guidance calling for 15% revenue growth and 17% EPS growth at the midpoint off a $63 billion base give the payout a durable runway. The specific risk: gross margin compression from AI product mix, which dropped non-GAAP gross margin to 66.3%, down 210 basis points, and hyperscaler concentration if AI orders cool.
Qualcomm still suits a different investor: one who wants higher current yield, faster raise percentages, and is willing to underwrite a cyclical handset business through the Apple share loss and memory-cost squeeze in exchange for optionality on the $40 billion non-handset revenue target by fiscal 2029. The specific risk there is blunt: Apple product revenue for FY27 will fall below the prior $2 billion guide, and QCT margins are guided to just 23% to 25% EBT next quarter. That is a growth-tilted dividend, not a retirement anchor. For a retiree writing checks off the portfolio, CSCO wins (and if the goal is building a ladder that funds those checks without ever touching principal, we walked through the full structure in a free guide here).
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.