SoFi Built a Bank, a Card Program, and a Stablecoin, but the Stock Struggles to Budge
SoFi launched a bank, a credit card empire, and a stablecoin on Mastercard's network, yet the stock sits nearly where it started five years ago. One operating metric suggests the everything-app thesis is actually working, so what keeps the chart…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) was last seen trading near $16.30 per share. The stock is down 37.8% year to date, including 10.7% in the past month. Five years ago, the share price was less than 8% higher than it is now.
Five Years, Three New Businesses, a Flat Chart
SoFi now operates under a national bank charter with deposits of $45.5 billion at the end of Q2 2026. It runs a credit-card program that Simply Wall St’s Bailey Pemberton sized at $25 billion, and it introduced SoFiUSD as the settlement asset for that program on Mastercard’s network on September 22, 2026. Total annualized spend across SoFi Money and the card reached more than $28 billion last quarter.
Cross-Buy Rate: The Operating Metric That Tells the Real Story
Look past revenue and one number captures the transformation: the share of new products opened by existing members. That cross-buy rate reached 51% in Q2 2026, up from 35% in Q2 2025. Products per member hit an all-time high of 1.54, and for the first time SoFi added twice as many products (2.2 million, +42% YoY) as new members. CEO Anthony Noto called it “a major milestone that underscores the trust members place in SoFi and the power of our everything app.” Cross-bought products, he added on the call, carry “basically zero” incremental acquisition cost.

Why the Chart Ignored All of It
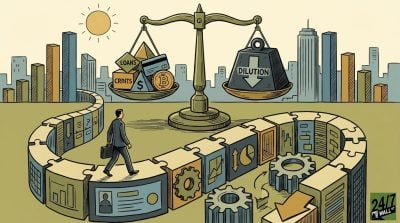
The data actually supports two forces. First, dilution. Common shares outstanding rose from 526.73 million at year-end 2021 to 1.29 billion at June 30, 2026. Per-share value has to run uphill against that count. Second, the valuation reset. SoFi now trades at a forward price-to-earnings multiple of 21, based on $0.47 trailing EPS, a compressed number relative to the blank-check-era premium the stock once carried. Rate context matters too: the federal funds upper bound is 4.00% as of September 23, 2026, and consumer-lender multiples have compressed across the cycle even as card delinquencies eased to 2.69%.
What Would Have to Change
Bullish for the next stretch: cross-buy climbing above 51%, products per member advancing past 1.54, and the SoFiUSD rails moving beyond SoFi’s own card book to third-party issuers or acquirers on the network. The bearish read: cross-buy stalling, which would signal that members have stopped consuming past the entry product, alongside continued share issuance that dilutes each of those product wins.

Verdict
The everything-app thesis is measurable, and the cross-buy rate says it is working. But a doubled share count and a normalized fintech multiple explain why building a bank, a card program, and a stablecoin has, so far, produced a flat stock. The chart moves when per-share economics compound faster than the float does.


Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.