SoFi Could Be Building Something Wall Street Hasn’t Fully Priced In
SoFi just posted a record quarter and raised guidance while its stock sits near a 52-week low, and the gap between what the business is doing and what the market is pricing in may be wider than most investors realize.

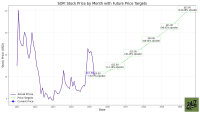
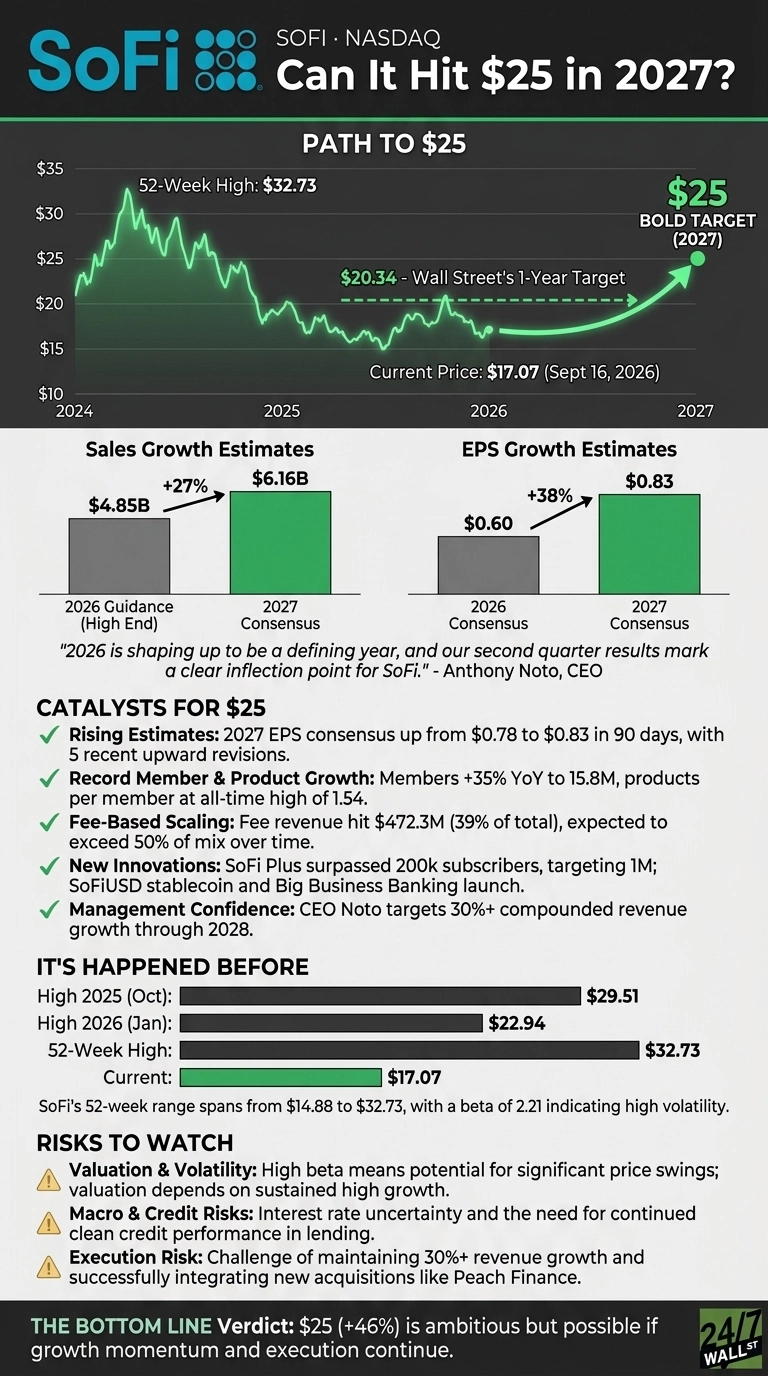
SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) has had a punishing 2026 in the market, but a very different story is unfolding inside the business. Shares are down 34.8% year-to-date and off 38.31% over the past year, closing at $17.07 on September 15, 2026.
Yet the digital finance platform just posted a record quarter, raised full-year guidance, and CEO Anthony Noto called Q2 “a clear inflection point for SoFi.” Let me walk through what it would take for SoFi shares to reach $25 in 2027.

Why Wall Street Is Cautious, and Why That Could Be the Opportunity
The consensus 12-month target sits at $20.34, with analyst ratings split across 3 strong buy, 5 buy, 12 hold, 2 sell, and 2 strong sell. That’s a lukewarm consensus for a company growing quarterly revenue 42.6% year-over-year. But the direction of estimates matters more than the level.
The 2027 consensus EPS has climbed from $0.7802 ninety days ago to $0.8276 today, with 5 upward revisions in the trailing 30 days. On the top line, 2027 revenue estimates now span from $5.54 billion at the low to $8.66 billion at the high, a spread that hints at how wide the bull case runs.

Math to $25 Per Share
At $17.07, SOFI trades at a forward P/E of 22x, essentially in line with the S&P 500. At $25, using the 2027 consensus EPS of $0.8276, shares would trade around 30x forward earnings. For a company guiding to 32% to 35% revenue growth in 2026 and a medium-term adjusted EPS CAGR of 38% to 42%, that’s a reasonable multiple.
What could push SOFI to $25?
- An earnings beat streak that keeps compounding. SoFi has beaten or met consensus in 5 of the last 6 quarters, including a 9.89% beat in Q2 2026 and a 33.5% beat in Q3 2025. Actual 2027 EPS could land above the $0.8276 consensus.
- Record originations and member growth. Q2 loan originations hit a record $14.8 billion, up 69% YoY, while members grew 35% YoY and products per member reached an all-time high of 1.54.
- Capital-light fee revenue scaling fast. Fee-based revenue reached $472.3 million, 39% of total. Management expects financial services and technology platform revenue to eventually exceed 50% of the mix.
- New product optionality. SoFi Plus surpassed 200,000 paid subscribers with Noto targeting 1 million members generating $120 million annually. The SoFiUSD stablecoin, Big Business Banking, and the Peach Finance acquisition open new revenue lanes.
Noto framed it plainly: “We are building a financial services company with a business model that we believe is increasingly differentiated, increasingly profitable, and increasingly difficult to replicate.”
SOFI’s History Says $25 Is Within Reach
Getting to $25 requires roughly a 46% gain, and SOFI has the volatility profile to make that happen. Its beta is 2.21, and the 52-week range spans from $14.88 to $32.73, meaning $25 sits comfortably inside a level shares traded at less than a year ago.
As recently as January 30, 2026, shares closed at $22.94, and at $29.51 in October 2025. Reclaiming those levels doesn’t require a miracle, just a re-rating toward the growth SoFi is actually delivering.

Bottom Line on $25
Hitting $25 would require a roughly 46% gain from $17.07, above the Street’s $20.34 consensus.
The setup is there: rising 2027 estimates, a five-quarter beat streak, 19 consecutive quarters above the Rule of 40, and management guiding to 30%+ compounded revenue growth through 2028.
If credit stays clean, deposits keep flowing, and the fee-based flywheel keeps turning, $25 is reachable. Returns like that shouldn’t be expected every year, but we’ve outlined the blueprint for how SoFi could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.