Price Prediction: SoFi’s Price Target For 2027 May Surprise Investors
SoFi shares have shed nearly a third of their value in 2026 even as the fintech keeps posting record numbers, and that gap between price and fundamentals points to a scenario Wall Street has not fully priced in yet.

SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) has had a rough 2026. Shares are down 31.7% year to date, giving back a large chunk of last year’s rally as investors digested a rate outlook that flipped from cuts to potential hikes. Yet the fintech’s fundamentals keep improving.
CEO Anthony Noto told investors that “2026 is shaping up to be a defining year” after the company posted record loan originations of $14.80 billion and its 11th consecutive profitable quarter. Let’s map out how SOFI could climb from $17.88 to $25 by the end of 2027.

Wall Street Sees Upside, But Bulls Want More
The Street’s consensus 12-month price target sits at $20.02, spread across 2 Strong Buys, 5 Buys, 12 Holds, 2 Sells, and 2 Strong Sells. That target implies mild upside from today’s price and reflects a cautious posture after a sharp drawdown. Estimates, however, are moving the other way.
The FY2027 EPS consensus has climbed from $0.775 ninety days ago to $0.822 today, with 5 upward revisions in the past 30 days against 2 downward. Analysts also model FY2027 revenue of roughly $6.16 billion, extending SoFi’s growth arc. With five consecutive EPS beats, actual results have a habit of running ahead of the model.

Path to $25 Per Share by 2027
At $17.88, SOFI trades at a forward P/E near 32. Applying the FY2027 EPS estimate of $0.822, a $25 stock would trade at roughly 30x forward earnings, actually a lower multiple than today. That is a reasonable ask for a business that management guides to a 2025 to 2028 adjusted EPS CAGR of 38% to 42%.
What could push SOFI to $25?
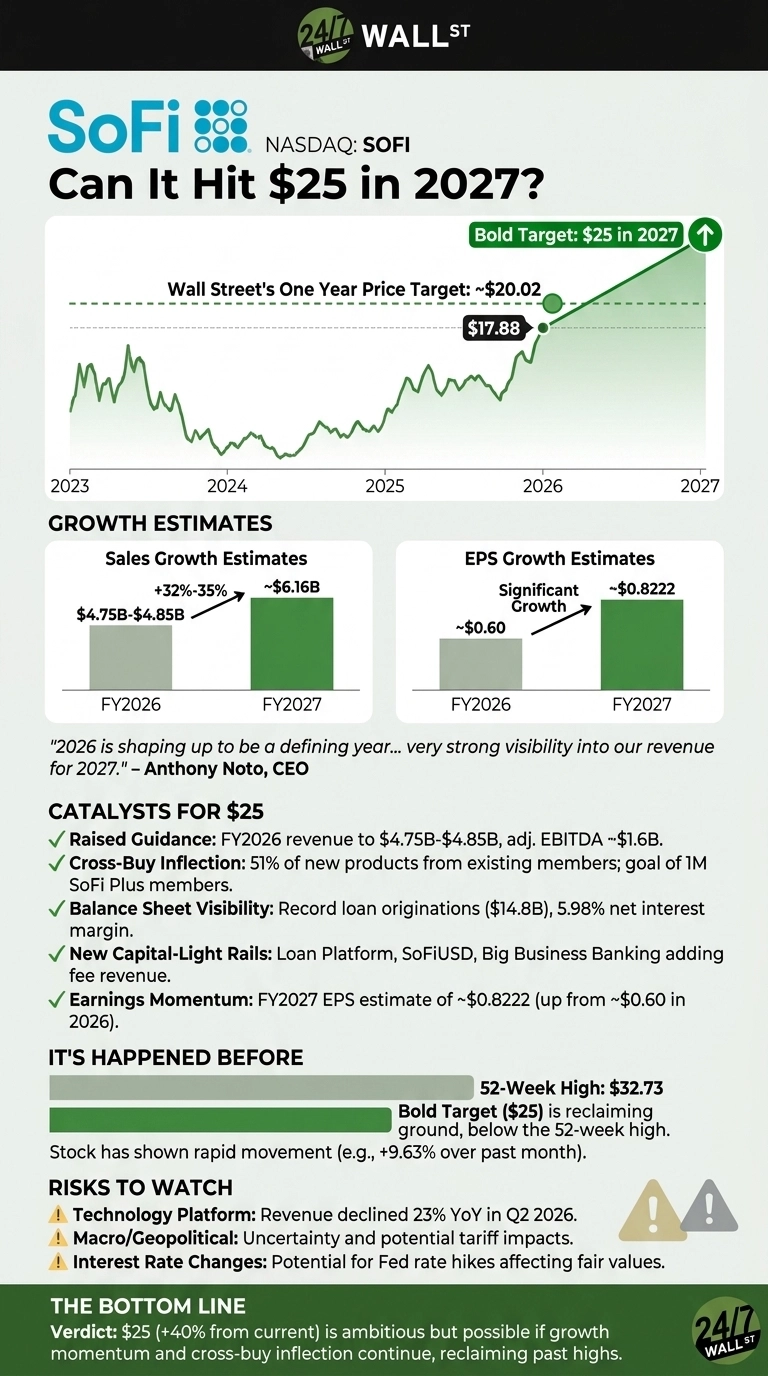
- Guidance already raised. Management lifted FY2026 adjusted net revenue to $4.75 billion to $4.85 billion, or 32% to 35% growth, with adjusted EBITDA near $1.6 billion.
- Cross-buy inflection. 51% of new products came from existing members, and Noto wants 1 million SoFi Plus members generating $120 million annually.
- Balance-sheet visibility. Noto said Q1 and Q2 lending growth gives “very strong visibility into our revenue for 2027”, backed by a 5.98% net interest margin and $45.5 billion in deposits.
- New capital-light rails. Loan Platform Business partnerships, SoFiUSD stablecoin settlement, and Big Business Banking add fee revenue on top of net interest income.
History Says a 40% Rebound Is On the Table
Reaching $25 requires roughly a 40% gain from here. SOFI has shown it can move that fast. Shares are already up 9.63% over the past month, and the stock’s beta of 2.204 means it tends to overshoot the market both ways.
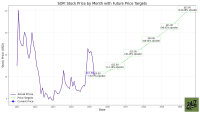
The 52-week high of $32.73 sits well above our target, so $25 would simply reclaim ground held earlier this cycle rather than break new records. Our own base-case model projects $21.50 by September 2027, with a bull case at $25.91.

Bottom Line on $25
Hitting $25 by late 2027 would require SOFI to gain about 40% while its forward multiple actually compresses to roughly 30x. With FY2027 EPS estimates rising 4 times in the past week alone, a five-quarter beat streak, and a long-term ROTCE target of 20% to 30%, the setup is there.
Macro risk and the 23% decline in Technology Platform revenue are real hurdles. Returns like this should not be assumed every year, but we have laid out a credible blueprint for how SOFI could reach $25 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.