Rocket Lab Crashed Back Toward Earth for 3 Months: This Analyst Says It’s About to Double
One Wall Street analyst has broken ranks with a target that would nearly double Rocket Lab's battered stock, but execution on a single make-or-break milestone stands between bulls and that payoff.

Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction) trades at $73.61 while the consensus Wall Street price target sits at $109.37, an implied upside of roughly 49%.
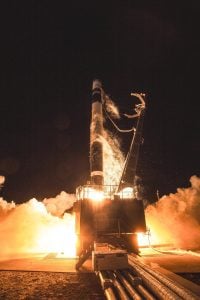
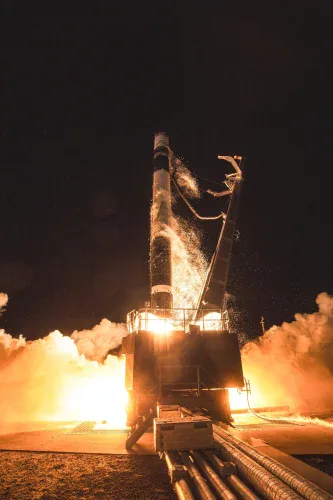
Rocket Lab is the second-most-recognized name in Western launch behind SpaceX, running the Electron small-lift rocket, building a growing Space Systems business, and preparing to debut the medium-lift Neutron. Its $2.36 billion backlog, pending acquisition of Iridium Communications, and expanding U.S. defense book have made it a favorite of space bulls.
One analyst now targets near-doubling upside while the median sees meaningful room to run. Yet the stock has slid from its highs, creating a disconnect worth examining.
Why the Rocket Rolled Over
The drawdown from Rocket Lab’s 52-week high of $151 has been severe, wiping out more than 51% of peak value before a recent bounce. Over the trailing three months alone, the stock is down 8.77%, sliding from $80.69 to the current level even as broader indexes advanced.
The catalyst is Neutron. Management said the window for an end-of-year launch is narrowing, with delivery to the pad targeted for Q4 2026 after a stage-1 tank test failure earlier this year. Bulls need Neutron to fly to justify the multiple.
Dilution has compounded concern. Rocket Lab pulled $1.08 billion through its ATM program in Q2, with Q3 guidance calling for roughly 641 million basic weighted shares. A Q2 non-GAAP free-cash-flow use of $110.1 million and price-to-sales ratio of 58 gave profit-takers reason to trim.
New Street Sees a Path Back to $150
The bull case is anchored by Pierre Ferragu of New Street Research, whose $150 Street-high 12-month target sits above a target range of $64 to $150 with a median hovering near $110. That $150 target implies roughly 104% upside from here, a near-doubling.
The thesis rests on Neutron commercialization at $50 to $55 million per flight, expanding government wins including a $397 million Flatellite award for the Space Force SB-AMTI program, and vertical integration through the Iridium deal, which serves more than 2.5 million subscribers and generated over $870 million in annual revenue last year.
Of 18 analysts covering the name, 3 rate it Strong Buy, 11 Buy, 4 Hold, and none Sell. Iridium shareholders approved the acquisition. The catalyst clock now runs on Neutron’s first flight and the mid-2027 Iridium close.
Analysts are watching execution: Q3 revenue guidance of $250 million to $265 million, more than $1 billion in new Q3 contracts already signed, and a backlog that grew 137% year-over-year. Miss on Neutron and the multiple compresses; hit and the model reprices.
How the Small-Cap Space Peers Stack Up
The pure-play space complex has not sold off uniformly. Rocket Lab and AST have declined while Redwire has advanced.
AST SpaceMobile (NASDAQ:ASTS) trades at $61.06 versus a consensus target of $79.61, implying 30% upside. Shares are down 15.93% year to date. Of 13 analysts covering, 4 rate it Buy or better, 7 Hold, and 2 Sell or worse, a more cautious posture than Rocket Lab.
Intuitive Machines (NASDAQ:LUNR) sits at $15.70 against a $29.50 target, an implied 88% upside. The stock is down 3.27% YTD with 7 Buy, 1 Hold, 1 Strong Sell, closest to RKLB in bullish tilt.
Redwire (NYSE:RDW) trades at $11.60 versus a $14.69 target, roughly 27% upside, with shares up 52.63% YTD. Coverage skews 6 Buy, 2 Hold, 1 Strong Sell.
Intuitive Machines shows the largest analyst-implied upside, but Rocket Lab is the only name where a mainstream shop publicly models a full double. Relative to peers, RKLB appears the higher-conviction bull case.
What the Data Actually Shows on RKLB
Rocket Lab trades at $73.61 with an average price target of $109.37 from 18 covering analysts, implying roughly 49% upside. The Street-high target from New Street Research at $150 would nearly double the stock.
Performance-wise, RKLB is up 5.52% year to date while the S&P 500 (via SPY) is up 12.52%, a notable underperformance versus the index. Rocket Lab is off 8.77% over three months but has rebounded 10.01% in the past month and 8.54% in the past week.
Analyst ratings breakdown:
- Strong Buy: 3
- Buy: 11
- Hold: 4
- Sell/Strong Sell: 0
Price targets are opinions, not guarantees, and Rocket Lab’s beta of 2.6 means the ride to either scenario will not be linear.
Weighing Rocket Lab at $73
The bull scenario requires Neutron reaching the pad on the Q4 2026 timeline, the Iridium acquisition closing in mid-2027 as planned, and the Space Systems backlog converting at current cadence. That path supports the consensus $109 and keeps New Street’s $150 in play. The bear scenario materializes if Neutron slips into 2027, dilution erodes per-share value, or Iridium integration proves messier than expected.
Cautiously constructive. The bull case is differentiated because no other Western pure-play combines launch, spacecraft, and a global comms constellation. The bear case is straightforward execution risk on a company still losing money. At roughly half the Street-high target and 49% below consensus, the risk/reward tilts positive for investors who can stomach the beta.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.