Rocket Lab Fell Hard Over The Last 3 Months: Wall Street Pro Predicts It Doubles From Today
Rocket Lab sits more than 50% below its 52-week high after a brutal stretch of dilution and missed earnings, yet one Wall Street analyst just reiterated a target that implies the stock doubles from here. The question is whether a…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction) currently trades at $71.92. Wall Street’s average price target is $109.15, which implies 51.8% upside.
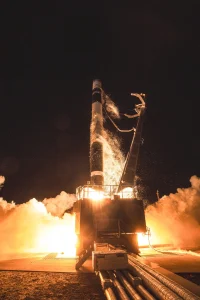
Rocket Lab flies the Electron rocket. It runs HASTE hypersonic test missions, builds spacecraft and components, and is finishing its Neutron medium-lift reusable rocket. Defense spending is the main draw. The Space Force budget requests $7.8 billion for space access. Rocket Lab is listed as a prime contractor on both national security launch programs.
The high end of the target range is even further away. Stifel’s Erik Rasmussen has a Street-high $150 target and a reiterated Buy rating. That target implies 108.6% upside, so he expects the stock to more than double.
Dilution and the Iridium Deal Pulled Rocket Lab Off Its Highs
Dilution did the most damage. Rocket Lab sold $1.08 billion of stock through its at-the-market program in the second quarter alone. Part of that money is for the Iridium Communications (NASDAQ:IRDM) acquisition, which is a cash and stock transaction. Management also guided the basic share count to about 641 million. Shares fell 13.78% over three months and now sit 52.4% below the 52-week high of $151.
The earnings report added pressure. Revenue of $234.07M rose 62.0% and beat estimates. The GAAP loss of $0.08 per share missed the -$0.0767 estimate, partly due to $8.58M in deal costs. Guidance calls for adjusted EBITDA loss of $17M to $23M, larger than the quarter’s $8.8 million. Management said the Neutron launch window this year is narrowing. A beta of 2.938 means swings tend to be larger than the market’s.
Analysts Are Banking on Neutron and a $2.36 Billion Backlog
Analysts remain bullish. Four rate the stock Strong Buy, 12 rate it Buy, four rate it Hold, and none rate it Sell. Stifel’s thesis rests on three points. Neutron could compete with SpaceX’s Falcon 9; Space Systems brings in more than two-thirds of revenue; defense contracts provide long-term backlog visibility.
Backlog grew 137% to a record $2.36 billion, with about 45.5% converting to revenue within 12 months. Recent wins include a $397M Space Force Flatellite contract and a $266 million award for up to 18 missile-defense launches. Neutron targets $50 to $55 million per launch. The CEO said, “We have absolutely zero issues in selling full price Neutrons pre-test flights.”
The timeline is weak. Management linked positive free cash flow to Neutron’s first successful launch, and Neutron’s debut already slipped to Q4 2026. Iridium brings more than $870 million in annual revenue but closes mid-2027. The stock trades at 62.4 times sales.
Space Peers Fell Too, and Planet Labs Shows the Bigger Gap
Shares of AST SpaceMobile (NASDAQ:ASTS) trade at $60.65, down 8.27% over the past month and 16.49% year to date. Its $77.94 target implies 28.5% upside. Ratings are conservative with one Strong Buy, four Buy, seven Hold, one Sell and one Strong Sell.
Planet Labs (NYSE:PL) trades at $17.75 and is down 9.99% year to date. Its $33.40 target implies 88.2% upside. Ratings include one Strong Buy, six Buy, three Hold and one Sell. Its gap is larger than Rocket Lab’s.
Planet Labs has the biggest consensus upside in the group, while Rocket Lab sits in the middle, and only Stifel’s target puts it in doubling territory. Price targets are opinions and come with no guarantee for any of these stocks.
Rocket Lab Beats Its Peers but Lags the S&P 500
At $71.92, Rocket Lab has 51.8% upside to the $109.15 consensus target. The stock bounced 11.92% over the past month but dropped 4.18% in its most recent trading day.
Rocket Lab has gained 3.1% so far this year, and the S&P 500 is up 13.98%. The $69.94 50-day average sits below the $81.50 200-day average, so the longer-term trend still points down.
Neutron’s First Flight Decides Whether $150 Is Realistic
The bull case strengthens if Neutron reaches the pad on schedule, flies smoothly and converts that 90+ mission backlog into higher-priced revenue. Positive cash flow comes into view and Iridium adds recurring revenue. If Neutron slips again, the downside case strengthens. Rocket Lab would then be funding Neutron, three acquisitions and ongoing burn, likely through more share issuance.
I are bullish. The backlog and defense demand back up the consensus target, but until Neutron flies, $109.15 is a more realistic marker than $150.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.