The Opportunity Behind AST SpaceMobile Stock Is Hard to Ignore
AST SpaceMobile is burning through capital at a staggering pace while racing to blanket the globe with satellites, and whether that gamble pays off depends on a narrow window of execution that could either vindicate the bulls or punish patient…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

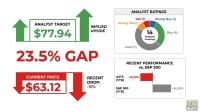
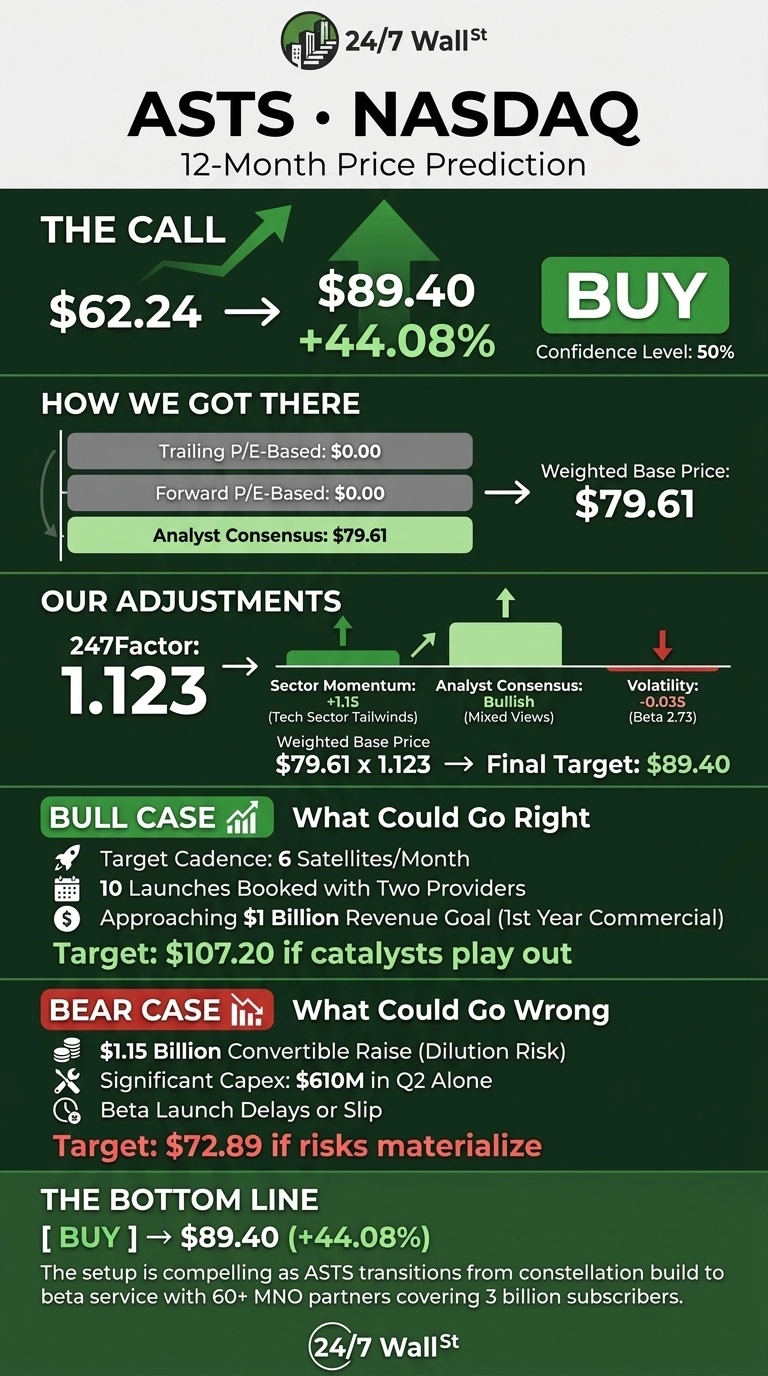
My AST SpaceMobile (NASDAQ:ASTS) call is straightforward: the stock trades at $62.24, and the 24/7 Wall St. price target sits at $89.40, implying 44.08% upside over the next 12 months.
That is a buy, with roughly 50% model confidence given the pre-commercial risk profile. The setup is compelling because a company with 60-plus MNO partners covering 3 billion subscribers is transitioning from constellation build to beta service.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $62.24 |
| 24/7 Wall St. Price Target | $89.40 |
| Upside | 44.08% |
| Recommendation | BUY |
| Confidence Level | 50% |
A Choppy Year Sets Up a Constellation Inflection
ASTS has been volatile. Shares are down 14.31% year to date but up 13.58% over the past year and 432.88% over five years. The stock sits well below its 52-week high of $133.86 and above the 52-week low of $47.50.
Q2 revenue of $31.52 million came in below the $34.40 million consensus, missing expectations by 8.36%, and GAAP EPS of -$0.77 was weighed down by a $125.9 million loss on involuntary conversion tied to the BB7 launch incident.
The offset: 13 spacecraft in orbit, a $1.30 billion contracted backlog, and reaffirmed $150 million to $200 million FY2026 revenue guidance. Management is targeting approximately 45 Bluebird satellites in orbit by early 2027.
Why Bulls See a Breakout Ahead
The bull case rests on scale economics. Management is guiding toward a target cadence of six fully assembled satellites per month, has 10 launches booked with two providers, and reiterated a goal of approaching $1 billion in revenue in its first full year of commercial service.
Add the Rakuten/AST J-LEO selection worth up to $1 billion and a planned JV with the top three U.S. MNOs, and the runway is real. Our bull-case scenario points to $107.20 within 12 months.
What Could Go Wrong
The bear case is dilution and delay. ASTS raised $1.15 billion in July 2026 convertible notes, capex hit approximately $610 million in Q2 alone, and stock-based comp ran $118.8 million for the first six months.
Bulls counter that these outlays are financing the constellation and that effective dilution from the convert is less than 2%. Still, if MNO MOUs stall or beta slips, the bear-case path lands near $72.89.
How ASTS Compares to Iridium, Globalstar, and Viasat
Iridium Communications (NASDAQ:IRDM | IRDM Price Prediction) is the profitable-incumbent counterpoint, generating $225.2 million in Q2 2026 revenue and awaiting an $8 billion all-stock acquisition by Rocket Lab. At a $5.2 billion market cap, Iridium trades at a fraction of ASTS’s $18.59 billion valuation despite far higher current revenue, which frames ASTS as a growth-optionality play.
Globalstar (NASDAQ:GSAT) is the direct D2D peer, with a pending Amazon merger at $90 per share and $10.7 billion market cap. GSAT’s Apple wholesale relationship validates the D2D thesis powering ASTS’s target.
Viasat (NASDAQ:VSAT) generated $1.16 billion in Q1 FY2027 revenue at a $10.4 billion market cap. That established base makes ASTS’s premium multiple look aggressive on today’s numbers but reasonable if beta hits in 2027.
AST SpaceMobile Price Prediction 2026-2030
My 24/7 Wall St. price target of $89.40 reflects a buy at 50% confidence. The setup looks constructive if beta launches on schedule and the U.S. MNO JV closes. The thesis weakens if BB14-16 slip past year-end or another launch anomaly forces a raise.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $66.51 |
| 2027 | $90.38 |
| 2028 | $120.67 |
| 2029 | $131.48 |
| 2030 | $151.89 |
These projections assume ASTS executes on the 45-satellite deployment, converts MOUs to definitive contracts, and scales beta into commercial revenue. Major upside or downside would come from launch cadence, spectrum outcomes, and government contract velocity.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.