AST SpaceMobile Is Building Something Wall Street Can’t Ignore
AST SpaceMobile has shed nearly a third of its value this year, drawn lawsuits, and sparked a debate about whether a SpaceX headline tanked the stock for no good reason. The answer depends on milestones that have not happened yet.

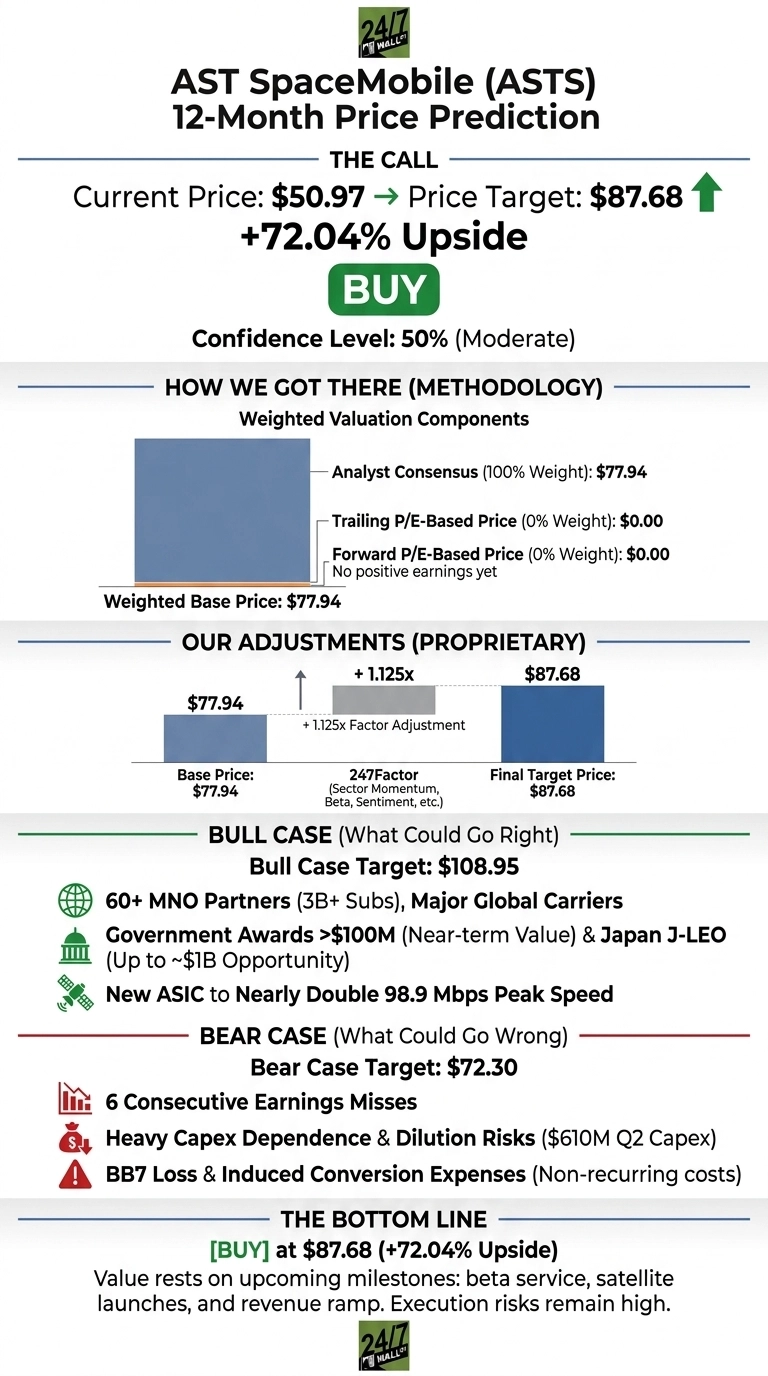
The 24/7 Wall St. price target for AST SpaceMobile (NASDAQ:ASTS) is $87.68 over the next 12 months, well above the recent $50.97 share price.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $50.97 |
| Price Target (24/7 Wall St.) | $87.68 |
| Upside/Downside | 72.04% |
| Recommendation | BUY |
| Confidence Level | 50% |
That 50% confidence reading is moderate. It reflects how much of AST SpaceMobile’s value rests on milestones still ahead: beta service with carrier partners in 2026, roughly 45 satellites in orbit by early 2027, and a revenue ramp toward confirmed 2026 guidance of $150M-$200M. The stock has fallen sharply this year, and that decline explains the wide gap to our target.
A 30% Slide, a Lawsuit Wave and a SpaceX Scare
Shares fell 13.11% over the past week and 18.63% over the past month. They are down 30.07% year to date, sitting close to the 52-week low of $47.57 and far below the $133.86 high.
Barron’s argued that the latest drop on SpaceX news was unwarranted, and law firms have announced class action filings against the company and certain officers.
In second-quarter results reported August 10, revenue jumped 2,626.6% to $31.52M but missed the $34.40M consensus. GAAP EPS of -$0.77 missed the -$0.29 estimate. Backlog rose to about $1.30B, and pro forma liquidity exceeded $3.70B after a $1.150B convertible notes offering.

Why Bulls See $108.95 Within Reach
In our bull scenario, the stock reaches $108.95. AST SpaceMobile counts over 60 MNO partners covering over 3 billion subscribers, including major global carriers.
Three new government awards carry over $100 million of funded near-term value, and Japan’s J-LEO project could be worth up to approximately $1 billion in non-dilutive capital.
A new ASIC should nearly double the 98.9 Mbps peak speed set by Block 1 satellites. The president repeated the goal of “approaching a billion of revenue in our first year of commercial service.”
What Could Derail the Constellation
The bear case target sits at $72.30. AST SpaceMobile has posted 6 consecutive misses. Second-quarter capex reached about $610 million, which keeps the business dependent on capital raises and exposes shareholders to dilution.
Launch timing also hinges on third-party providers. The six-month losses include a $125.9 million BB7 involuntary conversion loss and $88.7 million in induced conversion expense, both of which bulls treat as non-recurring.
How AST SpaceMobile Compares to Iridium and Globalstar
Iridium Communications (NASDAQ:IRDM | IRDM Price Prediction) is the mature contrast: a profitable global satellite operator that is pursuing direct-to-device service through NTN Direct. It earned $0.09 per share on 3.84% revenue growth, yet its market cap is only about $5.03 billion.
Globalstar (NASDAQ:GSAT) shares AST SpaceMobile’s exposure to smartphone satellite connectivity and has agreed to a takeover at $90 per share.
| Company | Market Cap | Q2 2026 Revenue | YoY Revenue Growth |
|---|---|---|---|
| AST SpaceMobile | $15.28B | $31.52M | 2,626.6% |
| Iridium | $5.03B | $225.24M | 3.84% |
| Globalstar | $10.86B | $64.77M | -3.54% |
Measured on today’s revenue, the peer group makes our target look aggressive. Measured against the backlog and the planned commercial ramp, it looks reasonable. A buyer is also paying a strategic premium for Globalstar’s spectrum, which offers a real-world benchmark for this kind of asset.
Key Milestones to Track Through the Beta Launch
The 24/7 Wall St. price target of $87.68 supports a buy at 50% confidence. The model’s case rests on liquidity of more than $3.7 billion coupled with a signed backlog.
The bull case improves if launches keep a monthly-to-bimonthly pace and beta service starts on schedule. The thesis weakens if launch delays push the 45-satellite target past early 2027. At these levels, the model’s upside reflects those execution risks.
AST SpaceMobile Price Prediction 2026-2030
Looking further out, here is where the price target model from 24/7 Wall St. projects AST SpaceMobile could trade, assuming current growth trends and market conditions hold.
| Year | Price Target (24/7 Wall St.) |
|---|---|
| 2026 | $58.67 |
| 2027 | $89.78 |
| 2028 | $128.85 |
| 2029 | $159.86 |
| 2030 | $193.09 |
AST SpaceMobile would need to keep executing on its constellation expansion for these projections to hold. Significant upside could come from government demand and sovereign network deals, while launch failures or heavy dilution could produce significant downside.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.