Synopsys Could Be One of the Biggest AI Picks Nobody Talks About
Synopsys software sits inside nearly every advanced AI chip on the market, yet the stock trades at a fraction of its closest rival's multiple. Here is why analysts and our model see a significant gap between where shares are and…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Synopsys (NASDAQ:SNPS | SNPS Price Prediction) has a hand in nearly every advanced AI chip, because its software designs and tests them. Even so, it gets far less attention than the chipmakers it serves.
Shares closed at $425.76. The price target from 24/7 Wall St. is $549.97, which implies 29.17% upside over the next 12 months. SNPS wins a buy rating from our model with high confidence.
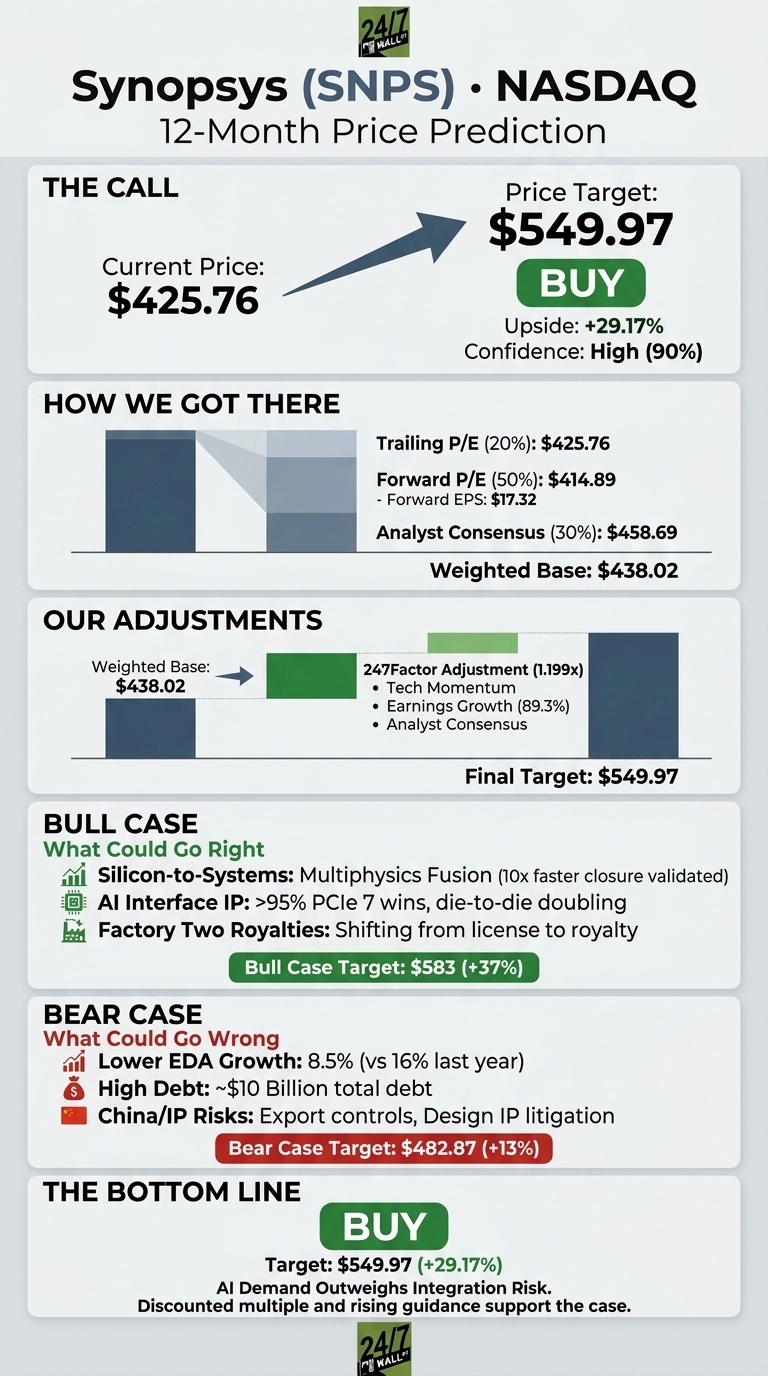
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $425.76 |
| Price Target from 24/7 Wall St. | $549.97 |
| Upside/Downside | 29.17% |
| Recommendation | BUY |
| Confidence Level | 90% |
The high confidence reflects steady earnings beats, a raised outlook, and 76% bullish analyst coverage. Investor Day on September 30 is the next catalyst.

A 10.6% Weekly Jump Puts the 2026 Slide in Question
Shares rose 10.6% over the past week and 3.84% over the past month, though they remain down 9.36% year to date and about 21% below the 52-week high of $539.48.
Two catalysts drove the rally: an agentic AI partnership with TSMC (NYSE:TSM) announced on September 23, and an analyst upgrade reported two days later.
In fiscal Q3, revenue came in at $2.48B, up 42.4% year over year and ahead of the $2.44B consensus. Non-GAAP EPS of $3.91 beat the $3.67 estimate. Management then raised full-year non-GAAP EPS guidance to $15.04 to $15.10.
Why Bulls See $583 Within Reach
- Silicon-to-systems: Multiphysics Fusion uses Synopsys and Ansys technology. Customers validated up to 10x faster design closure, and the product should start adding to EDA growth in 2027.
- AI interface IP: Synopsys won more than 95% of PCIe 7 opportunities, and its die-to-die business is on pace to double.
- Royalties: The Factory Two effort aims to move custom silicon deals from license fees alone to license plus royalty.
Of the analysts covering the stock, 16 rate it a buy and 3 a strong buy. Their consensus target is $553.77. The bull case has the stock reaching $583.

What Could Drag Shares Toward $482.87
EDA revenue grew just 8.5% in Q3 versus 16% last year, though management expects double-digit Q4 growth. Total debt is near $10 billion with $2.6 billion in projected free cash flow.
On a GAAP basis, the stock trades at 74x earnings, expanded by Ansys amortization. China export controls and Design IP litigation add risk. The bear case of $482.87 still is above today’s price.
Synopsys Trades Cheaper Than Its Closest Rival
| Company | Forward P/E | Quarterly Revenue Growth YoY |
|---|---|---|
| Synopsys | 23x | 42.4% |
| Cadence | 32x | 24.2% |
| Keysight | 22x | 36.5% |
Cadence (NASDAQ:CDNS) is the other half of the EDA duopoly. The stock changes hands at 32x forward earnings and runs a TTM operating margin of 28.6%. Synopsys would reach our target at a multiple still below Cadence’s.
Keysight (NYSE:KEYS) is a useful comparison because it also sells design and test tools into AI hardware. At 22x forward earnings, it trades in line with Synopsys. Measured against these two peers, the 24/7 Wall St. price target looks reasonable and possibly conservative.
Our Verdict: AI Demand Outweighs Integration Risk
Our $549.97 target carries a buy rating and high confidence. A discounted multiple coupled with rising guidance supports the case.
Investor Day confirmation of double-digit EDA growth and royalty-based Factory Two deals would strengthen it. Synopsys remains one of the most overlooked ways to own the AI expansion.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $463.28 |
| 2027 | $583.76 |
| 2028 | $670.67 |
| 2029 | $774.39 |
| 2030 | $832.24 |
These estimates assume continued execution of the silicon-to-systems strategy. Ansys synergies and agentic AI licensing could drive results higher; a slowdown in AI design starts could pull them lower.
Synopsys is one path into the AI expansion that skips the chipmakers entirely, and we identified seven more of those overlooked suppliers in a free report on the companies powering the AI boom.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.