Dell Is Quietly Riding One of the Biggest Tech Trends
Dell's AI server business has exploded, its backlog dwarfs what most companies earn in a year, and the stock has already staged one of tech's most dramatic runs. The question now is whether supply constraints and a cash flow slide…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Dell (NYSE:DELL | DELL Price Prediction) has become a major AI infrastructure company. Last quarter, AI servers alone generated $16.40 billion in revenue. The stock trades at $537.48. Our 24/7 Wall St. price target is $594.78, meaning 10.66% upside over 12 months, with a buy rating and 90% confidence.
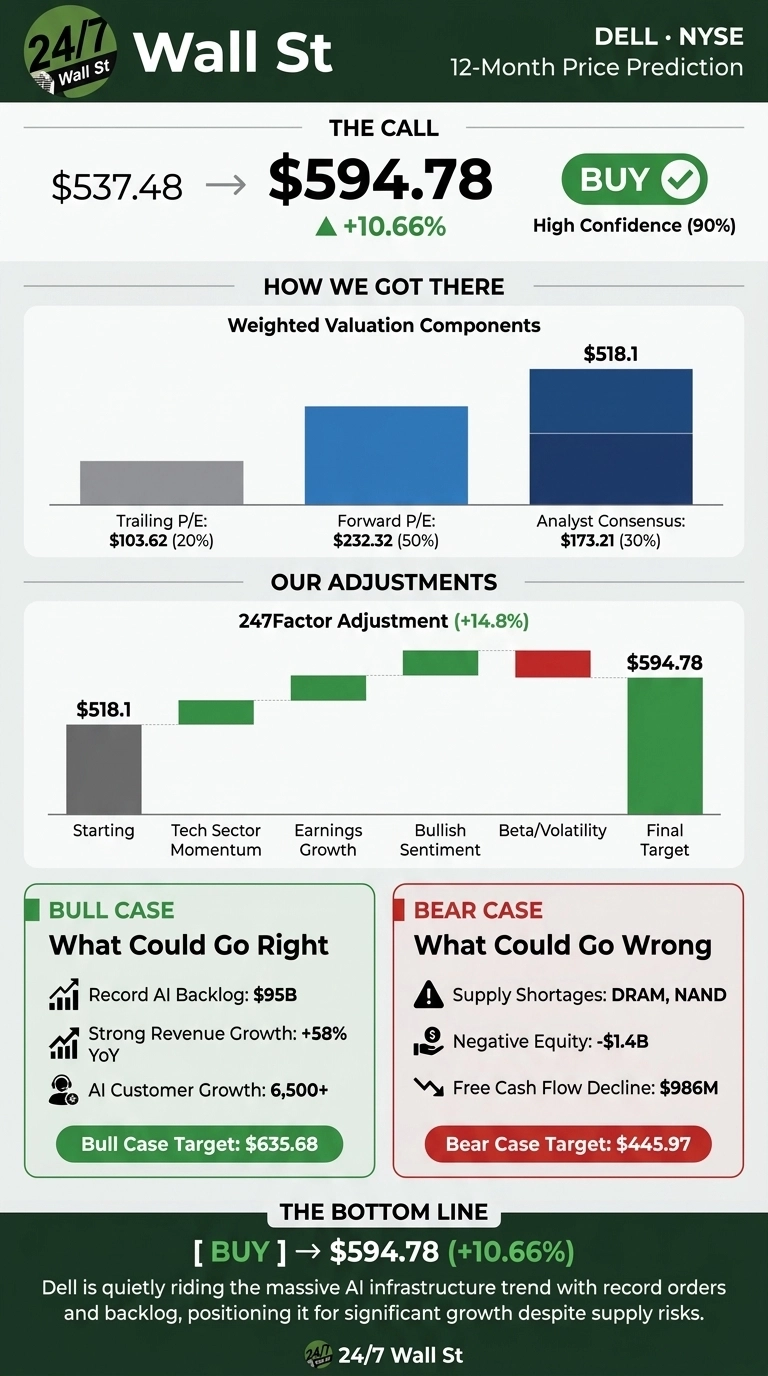
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $537.48 |
| Price Target from 24/7 Wall St. | $594.78 |
| Upside | 10.66% |
| Recommendation | BUY |
| Confidence Level | 90% |
The target sits just below the 52-week high of $595.51, meaning the thesis depends on Dell turning its backlog into earnings.

A $95 Billion Backlog Fueled a 330% Run
Dell is up 330.94% year to date and 15.88% over the past month. It has fallen 5.38% over the past week and sits 9.74% below its high. The 52-week low was $109.7.
Dell reported fiscal second-quarter results on September 1. Revenue rose 57.75% to $46.97 billion, beating the $44.44 billion estimate. Non-GAAP EPS came in at $7.04, well ahead of the $4.90 consensus.
AI orders hit a record $60.9 billion, and backlog reached $95 billion. Management raised full-year revenue guidance to $192 billion and non-GAAP EPS guidance to $25.50.

Why Bulls See $635 and Beyond
The bull case is $635.68. Demand goes beyond AI: traditional server revenue jumped 122% and storage grew 26%. Dell serves over 6,500 AI customers. Management expects operating expenses near 8% of revenue, the lowest in its 42-year history.
Analyst ratings: 5 Strong Buy, 14 Buy, 9 Hold, zero Sell. Fiscal 2028 EPS consensus rose to $24.6637, up from $18.3525 60 days ago.

Supply Shortages and Cash Flow Could Stall the Rally
Supply is the biggest risk. CEO Jeff Clarke stated: “DRAM, DRAM, DRAM, followed by NAND, NAND, NAND.” Free cash flow fell 47.22% to $986 million, and shareholders’ equity is negative at -$1.427 billion.
Context matters: capital spending rose 83.56% as Dell added capacity. Adjusted free cash flow was $8.1 billion and core leverage 0.8x.
Dell Trades at a Premium to HPE and Super Micro
| Company | Forward P/E | PEG Ratio |
|---|---|---|
| Dell | 21 | 0.646 |
| HPE | 14 | 0.498 |
| Super Micro | 10 | 0.913 |
Hewlett Packard Enterprise (NYSE:HPE) sells servers, storage and networking to the same enterprise buyers. At 14x forward earnings with a lower PEG, it screens cheaper on growth-adjusted valuation.
Super Micro (NASDAQ:SMCI) competes directly on AI rack systems at 10x forward earnings. Only 5 analysts rate it Buy or better versus 3 Sell ratings, suggesting investors reward Dell’s execution record. Our target looks reasonable relative to these peers.
Record Backlog Tips the Scale Toward Upside
My 24/7 Wall St. price target is $594.78, with a buy rating and 90% confidence. The $95 billion backlog provides over a year of revenue visibility.
I would turn more constructive if Dell holds supply and converts backlog on schedule, and conservative if memory shortages squeeze margins or free cash flow continues falling.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (December) | $557.39 |
| 2027 (September) | $588.17 |
| 2028 (September) | $642.38 |
| 2029 (September) | $667.29 |
| 2030 (September) | $694.61 |
The projections rest on Dell continuing to execute its strategy. A faster enterprise AI expansion could drove results higher (we covered seven of the infrastructure suppliers riding that same wave, power and cooling included, in a free report), while a pullback in hyperscaler spending would weigh on performance.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.