HPE Networking Outlook Gets Boost as Barclays, Citi and Wells Fargo Raise Price Targets
Citi, Barclays, and Wells Fargo all lifted their HPE price targets after Networking Investor Day, yet the three firms land in very different places on whether the stock's explosive run has already consumed the upside.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
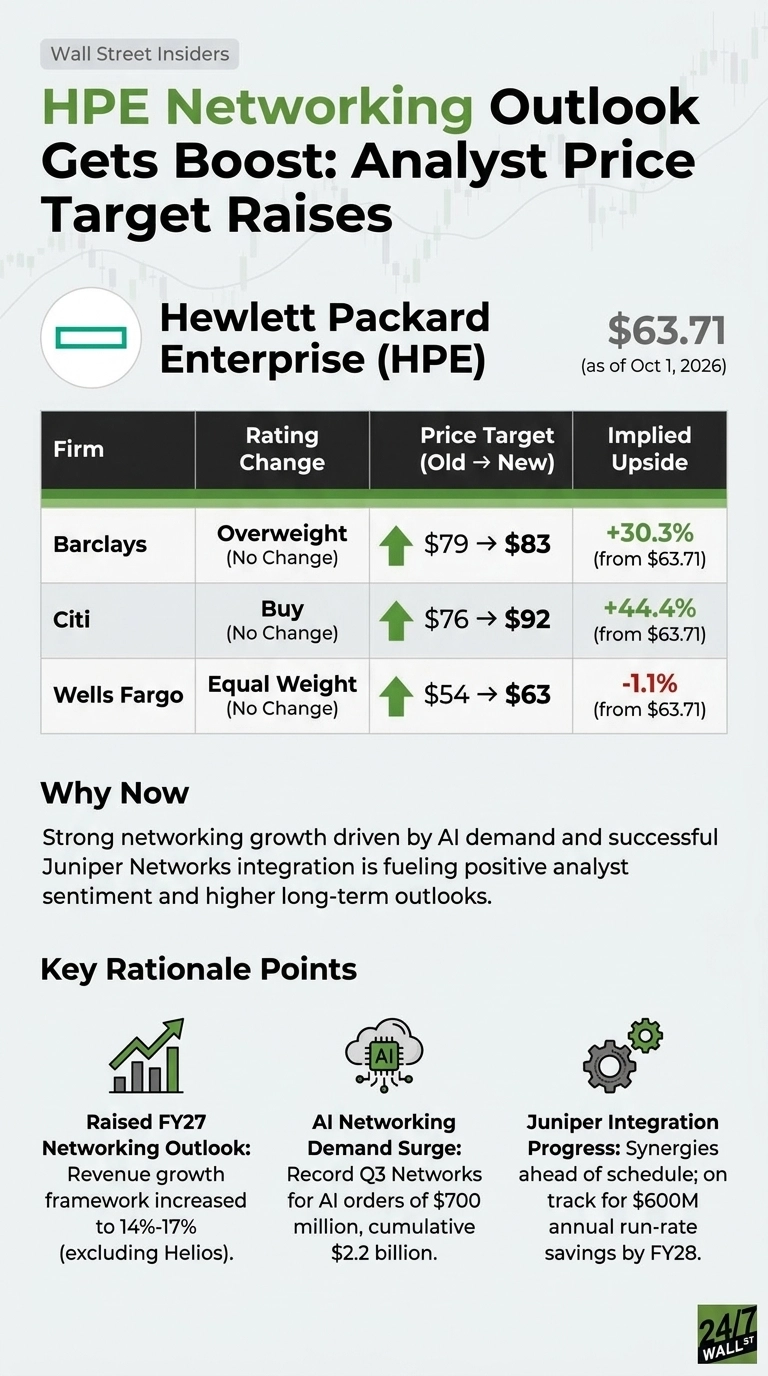
Three Wall Street firms raised their price targets on Hewlett Packard Enterprise (NYSE:HPE | HPE Price Prediction) after its Networking Investor Day.
Citi moved its target to $92 from $76, Barclays to $83 from $79, and Wells Fargo to $63 from $54. None of the three changed its rating.
All three point to networking as HPE’s main growth engine, but they still disagree on how much of that upside the stock already prices in.

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| HPE | Hewlett Packard Enterprise | Citi | Price Target Raised | Buy | Buy | $76 | $92 |
| HPE | Hewlett Packard Enterprise | Barclays | Price Target Raised | Overweight | Overweight | $79 | $83 |
| HPE | Hewlett Packard Enterprise | Wells Fargo | Price Target Raised | Equal Weight | Equal Weight | $54 | $63 |
Analysts Agree Networking Now Drives the Story
Barclays said HPE raised its fiscal 2027 networking outlook to high-teens to low-20s percent growth. At its September earnings call, the company had guided to 14% to 17%, and that figure left out the Helios platform from Advanced Micro Devices (NASDAQ:AMD). Barclays now says HPE sees Helios as an over $1B networking opportunity over the next two years.
Citi said the near-term financial update surprised investors and showed “strong” confidence in sustained growth over the longer term. The firm called the company’s messaging “incrementally bullish” for the shares.
Wells Fargo, taking a more measured view, cited a positive strategy overview and a higher FY27 outlook, and it found the Juniper integration better than expected. It added that performance on winning market share will be the focus.

HPE Snapshot: A Record Quarter Set the Stage
Third-quarter fiscal 2026 revenue reached $12.21B, up 32.7% from a year earlier. Non-GAAP EPS of $1.11 beat the $0.93 consensus, making it the fifth straight quarterly EPS beat. Networking revenue rose 74.9% to $2.89B, and routing climbed 270%.
Orders for HPE’s networks for AI hit a quarterly record of $700 million. Juniper synergies remain on track for $600 million in annual run-rate savings by the end of FY28.

Why These Target Hikes Matter Now
Hewlett Packard Enterprise stock trades at $63.71. That is up 168.23% year to date and 22.24% over the past month. The price already sits just above Wells Fargo’s new target, which helps explain why that firm still rates the shares Equal Weight.
Earnings estimates are rising along with the price. Consensus FY27 EPS now stands at $4.5974, compared with $4.1063 30 days ago. Analysts made 15 up revisions in that period and zero down ones.
What It Means for Your Portfolio
A stronger networking outlook supports HPE’s growth case for long-term investors, though the stock’s sharp run-up raises the bar for performance. Shortages of DDR5 memory and NAND flash continued to restrict the conversion of demand into revenue. The company also lists trade policy and Juniper integration as risks.
All that AI-driven networking demand has to be powered and cooled by someone, and the suppliers behind the data-center expansion rarely get the attention the chipmakers do. We featured seven of them in a free report you can grab here.
Income-focused investors get a modest dividend yield of 0.94%. HPE also plans to return at least 75% of fourth-quarter free cash flow to shareholders.
The next checkpoint is the fiscal fourth-quarter report. HPE has guided for revenue of $13.9B to $14.8B and non-GAAP EPS of $1.20 to $1.30. Investors should also keep an eye on Helios ordering, which management expects to open later in the calendar year.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.