Rates Are Hammering REITs. These 5 Dividends Are Built to Hold Up
The 10-year Treasury yield just hit a year-long high and dragged every one of these net lease REITs down with it, but falling share prices and failing dividends are not the same thing, and the difference matters more right now…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
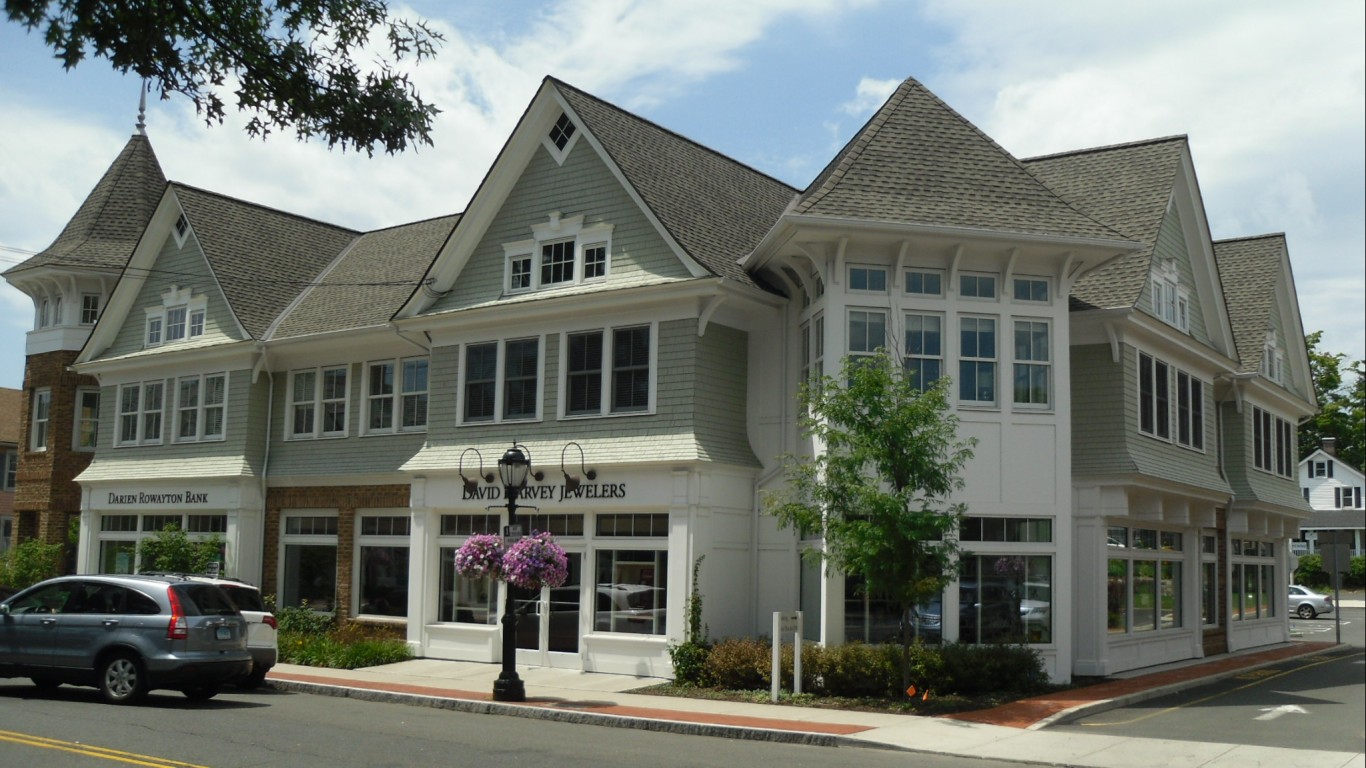
The 10-year Treasury yield hit 5.26% on September 29, 2026, the high of its past-year range, and every stock here fell over the past month. Rates are pressuring net lease and retail REITs, which own buildings rented to a single tenant who pays the property taxes, insurance and maintenance on top of rent. That leaves the landlord collecting a long, predictable check with few operating costs. The demand driver is sale-leaseback financing, where businesses sell their real estate to raise capital and lease it right back, and the five landlords below bought at initial cash cap rates from 7.0% to 7.8% in the second quarter. All five are property-owning equity REITs. There are no mortgage REITs on this list, which matters because mortgage REITs own loans and carry interest rate and credit risk that landlords collecting rent from physical buildings do not.
NNN REIT Has Raised Its Dividend 37 Years Running
NNN REIT (NYSE:NNN) owns 3,774 freestanding single-tenant properties, with recent buying concentrated in auto service, discount retail and early childhood education. Occupancy reached 99.1%, up 110 bps year over year, with a weighted average remaining lease term of 10.1 years. Annualized base rent rose to $959.1M, up 7.3%.
Demand background: NNN invested $291.0M in the second quarter at a 7.3% initial cash cap rate with a 17.9-year lease term, and raised 2026 acquisition guidance to $700M to $800M.
Yield: The quarterly dividend is $0.62, or $2.48 annualized, for a yield of 5.8%. Shares sit at $41.60, down 7.97% over the past month.
Coverage: The right metric for every REIT here is AFFO per share (adjusted funds from operations). GAAP earnings take off depreciation, a large non-cash charge on buildings that often hold or gain value, so an earnings payout ratio makes REIT dividends look far riskier than they are. NNN shows the gap: second-quarter EPS was $0.52 while AFFO was $0.90 per share. The payout was 67% of AFFO in the quarter, and the chief financial officer put it at a “healthy 69% AFFO payout ratio” at the new rate. Raised 2026 AFFO guidance of $3.55 to $3.59 sits well above the $2.48 annualized dividend.
Bull case: Credit is improving. Full-year bad-debt guidance fell to roughly 40 basis points from 60 basis points, and management called it “the best shape that the portfolio has been since I’ve been here.” The 37th consecutive annual dividend increase backs that up.
Risk: Financing costs are rising. Interest expense reached $53.5M versus $49.3M a year earlier, and management cited a potential 10-year debt cost in the mid-5% to 5.6% range for new issue.
Essential Properties Realty Trust Pays Out Just 64% of AFFO
Essential Properties Realty Trust (NYSE:EPRT) leases 2,493 properties to middle-market service businesses: car washes, medical and dental offices, early childhood education, quick-service restaurants, auto service and convenience stores. Occupancy is 99.6% with only nine vacant properties, the weighted average lease term is 14.3 years, and tenants generate rent coverage of 3.5x. Same-store rent growth was 1.5%.
Demand background: Essential Properties deployed $332.4M across 103 properties at a 7.8% cash cap rate, with 84% structured as sale-leasebacks and 72% sourced from existing tenants. Investment guidance rose to $1.2B to $1.5B.
Yield: The dividend is $0.32 quarterly, or $1.28 annualized, with the next payment on October 14, 2026. The stock trades at $26.27, down 11.35% in a month, the largest drop in this group.
Coverage: AFFO per share rose 9% to $0.50, and the payout ratio was 64% of AFFO. That leaves roughly $170M of annualized retained free cash flow. Raised AFFO guidance of $2.01 to $2.05 covers the $1.28 annualized dividend with a wide margin.
Bull case: The balance sheet is ready for more deals, with pro forma leverage of 3.5 times, $1.7B of liquidity and about $575M of unsettled forward equity. The quarterly payout has rose from $0.23 in 2020 to $0.32.
Risk: Middle-market tenants carry thinner credit than national chains. The share of rent with coverage below 1x rose from 3.4% to 3.9%, and the company reserved a $2.6M credit loss provision in the quarter.
Agree Realty Pairs Blue-Chip Retail Tenants With a Monthly Check
Agree Realty (NYSE:ADC) owns 2,825 properties across all 50 states and DC, leased mostly to large investment grade retailers. Investment grade exposure stands at nearly two-thirds of the portfolio, and 268 ground leases make up over 10% of annualized base rents. Occupancy is 99.8%, and same-store rent growth was 0.9%.
Demand background: Agree Realty put a record $501.7M to work across 102 properties at a 7.0% cap rate and an 11.2-year lease term. Investment-grade retailers accounted for over 73% of the rent it acquired. Full-year investment guidance rose to $1.6B to $1.8B.
Yield: Agree Realty pays monthly. The current $0.267 per share works out to $3.204 annualized, a 4.3% year-over-year raise. Shares trade at $66.81, down 7.16% over the past month.
Coverage: AFFO per share rose 7.4% to $1.14, and the payout ratio was 70% of AFFO. Raised guidance of $4.57 to $4.59 stands against a $3.204 annualized dividend, and free cash flow after the dividend is expected to exceed $140 million this year.
Bull case: Credit losses barely register. Second-quarter credit and occupancy loss was 0.06%, the recapture rate on re-leased space was 105%, and there are no material debt maturities until 2028. Management said “Our consistent and reliable earnings growth continues to support a growing and well-covered dividend.”
Risk: Short-term borrowing exposure is meaningful in a rising-rate market. Agree Realty carries $497M of floating-rate commercial paper, and interest expense rose to $40.3M from $32.3M.
Realty Income Has Raised Its Payout 115 Quarters in a Row
Realty Income (NYSE:O) is the giant here, with a market cap of about $51.38B. It owns a diversified net lease portfolio led by retail, with growing industrial, gaming and new data center exposure. Occupancy is 98.8%, same-store rental revenue grew 1.2%, and re-leased space came in at a 102.7% rent recapture rate.
Demand background: Realty Income committed about $2.6B in the quarter at a 7.3% initial cash yield, with 65% going to industrial. It raised 2026 investment guidance to $10.0B from $9.5B and announced a $6B hyperscale data center joint venture.
Yield: The monthly dividend stands at $0.2715, declared September 8, 2026, for an annualized forward rate of $3.258. The quoted dividend yield is 5.68%, which keeps it in high-yield territory, and shares trade at $54.44 after a 10.72% monthly decline.
Coverage: GAAP EPS of $0.37 missed the $0.4227 consensus after $54.2M of impairments, a textbook case of why earnings mislead on REIT dividends. AFFO per share rose 3.8% to $1.09, and raised full-year AFFO guidance of $4.44 to $4.45 tops the $3.258 annualized dividend well.
Bull case: Scale and cheap capital. Fitch rates Realty Income “A”, pro forma liquidity tops $5.7 billion, and the record now stands at 670 consecutive monthly dividends and the 115th consecutive quarterly dividend increase.
Risk: Tenant credit mix. About 65.7% of annualized base rent comes from non-investment grade tenants, and the watch list remains “in the high 5% area,” led by home furnishings and casual dining.
W. P. Carey Ties Nearly Half Its Rent to Inflation
W. P. Carey (NYSE:WPC) owns a diversified net lease portfolio dominated by industrial and warehouse properties, plus retail, across the U.S. and Europe. Occupancy is 98.5%, 47.8% of annualized base rent is linked to CPI escalators, and >99% carries contractual rent increases. Same-store rent growth was 2.6% in constant currency.
Demand background: Second-quarter investments amounted $706.5M, anchored by a $400.2M GardenCore sale-leaseback covering 43 properties on a 20-year master lease. Year-to-date volume reached $1.3 billion at a 7.4% initial cash cap rate, and guidance rose to $1.7B to $2.1B.
Yield: W. P. Carey declared a $0.95 quarterly dividend on September 18, 2026, payable October 15, 2026, for $3.80 annualized and a yield of 5.69%. Shares trade at $64.15. Income investors should know the history: the quarterly payout dropped from $1.071 to $0.86 after the late 2023 office spinoff, and it has risen every quarter since.
Coverage: AFFO per share of $1.34 beat the $1.24 estimate, and management put the payout ratio at just over 70%. Raised AFFO guidance of $5.19 to $5.27 sits well above the $3.80 annualized dividend, and the company keeps roughly $300 million of cash flow a year.
Bull case: Inflation helps here. With 95% of debt fixed at a weighted average 3.2%, CPI-linked rent bumps flow straight through. The CEO said the company is “uniquely positioned to benefit from the inflationary pressure stemming from higher energy prices.”
Risk: Europe is soft. Same-store rental income there declined 2.6% in constant currency, and second-quarter real estate impairments amounted $79.4M, with tenant Hellweg still working through insolvency.
Rate Spike Hits Prices While AFFO Keeps Climbing
All five of these landlords raised AFFO guidance this summer while their share prices fell with a 5.26% 10-year yield. Essential Properties at 64% and NNN at 67% of AFFO carry the widest dividend margin, Agree Realty brings the strongest tenant credit, and W. P. Carey brings the most inflation protection. Rising rates are pressuring the stock prices, and the rent checks are still growing. Keep an eye on third-quarter AFFO coverage and fresh cap rates to confirm that spread holds.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.