Palantir’s Growth Could Justify a Much Higher Stock Price
Palantir just posted its ninth consecutive earnings beat and revenue growth that left Wall Street scrambling to revise its models upward, yet the stock still sits 9% below its peak. Whether that gap is an opportunity or a warning depends…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
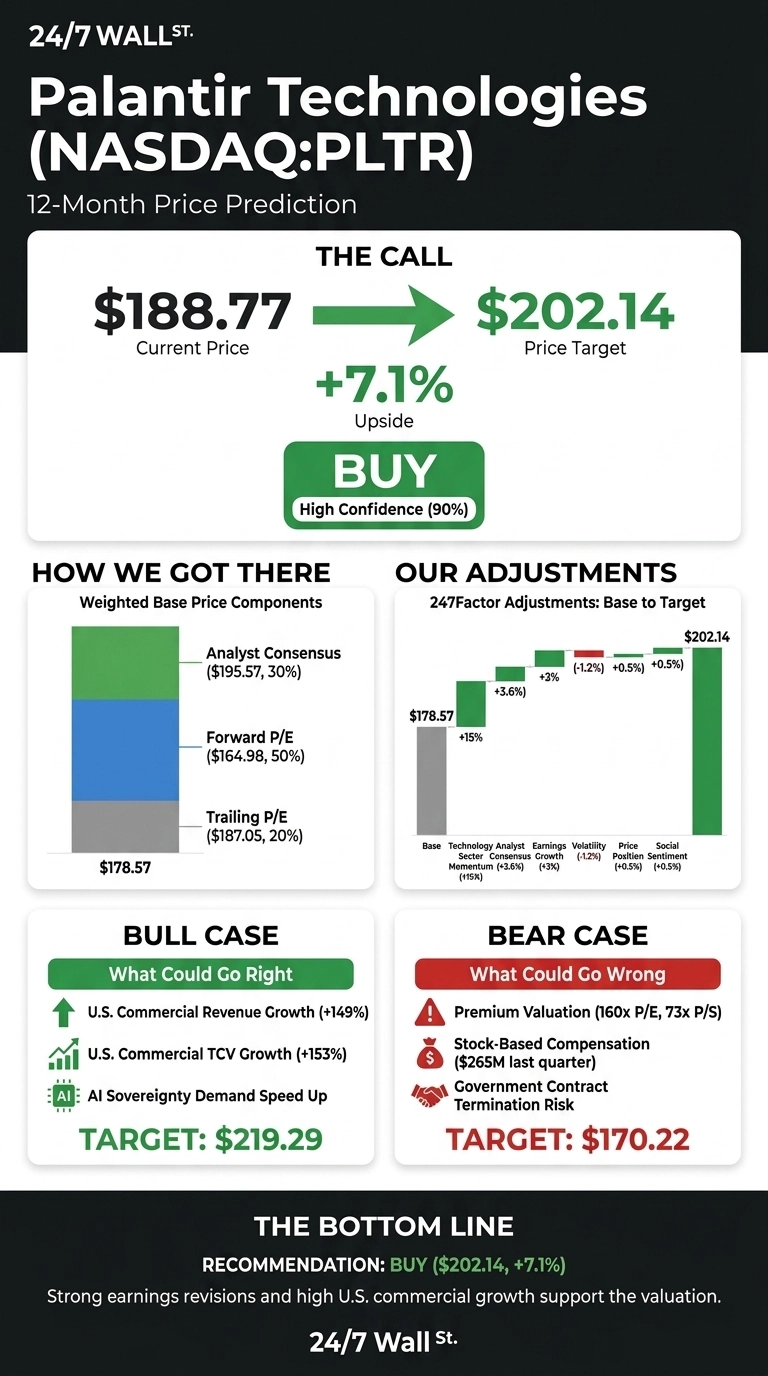
Our 24/7 Wall St. price target for Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) is $202.14 over the next 12 months. With shares at $188.77, that means 7.1% upside. Our model rates Palantir a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $188.77 |
| Price Target from 24/7 Wall St. | $202.14 |
| Upside | 7.1% |
| Recommendation | BUY |
| Confidence Level | 90% |
That target sits above the Wall Street consensus of $195.57. Management raised full-year revenue guidance to $8.150 billion to $8.158 billion, representing 82% growth. The question is whether growth can outrun a valuation that already prices in significant upside.

A Second-Quarter Earnings Beat Sparked a Sharp Rebound
Palantir traded near $123.06 on August 1. A week later it was at $172.01, after the August 3 earnings report. Shares are up 6.2% year to date and 1.28% over the past month, but down 1.57% this week. The stock sits 9% below its 52-week high of $207.52 and 77% higher than its low of $106.37.
Second-quarter EPS of $0.41 exceeded the $0.28 estimate, Palantir’s ninth consecutive beat. Revenue reached $1.935 billion, up 92.83%. U.S. commercial revenue grew 149% to $764 million. CEO Alex Karp called the quarter “otherworldly,” pointing to a Rule of 40 score of 155%.

Why Bulls See $219 and Beyond
In the forward pipeline, U.S. commercial total contract value rose 153% to $2.132 billion, and remaining deal value climbed 124% to $6.238 billion.
The 2027 EPS consensus has risen to $2.3267 from $2.0821 90 days ago, with 26 upward revisions and zero cuts in 30 days. If AI sovereignty demand speeds up, the bull case reaches $219.29.

A Premium Valuation Leaves Little Room for a Stumble
Palantir trades at 160x trailing earnings and 73x sales. Its government contracts can be ended for convenience, and stock-based compensation reached $265 million last quarter. Our bear case is $170.22. Even so, GAAP operating margin reached 47% after those compensation costs, so profitability already covers the dilution.

Palantir Outgrows CrowdStrike, Snowflake and ServiceNow
CrowdStrike (NASDAQ:CRWD) is in the same software-infrastructure industry and also carries a premium for AI exposure. The stock changes hands at 208x forward earnings on 25.8% revenue growth.
Also competing with Palantir for enterprise data and AI workloads is Snowflake (NYSE:SNOW), yet its 169x forward multiple comes with 35.1% growth.
ServiceNow (NYSE:NOW) is the value contrast, trading at 28x forward earnings on 24% growth.
| Company | Forward P/E | Quarterly Revenue Growth YoY |
|---|---|---|
| Palantir | 85x | 92.8% |
| CrowdStrike | 208x | 25.8% |
| Snowflake | 169x | 35.1% |
| ServiceNow | 28x | 24% |
Palantir is growing several times faster than its high-multiple peers and trades at a lower forward multiple than both. Measured against that group, our 24/7 Wall St. price target looks reasonable and even conservative.
Palantir Earns Its Premium, and the Upside Is Still Building
The 24/7 Wall St. price target of $202.14 comes with a buy rating and 90% confidence. What tips the scale is the steady stream of upward earnings revisions.
The case gets stronger if U.S. commercial growth stays above 100% and the third quarter beats the $2.160 billion to $2.164 billion revenue guide. It weakens if deal momentum slows while the multiple stays extended. For now, growth is exceeding the valuation.
Palantir Price Prediction 2026-2030
Looking further ahead, here is where our model projects Palantir could trade at each year’s end, assuming current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $190.18 |
| 2027 | $204.33 |
| 2028 | $212.81 |
| 2029 | $236.20 |
| 2030 | $251.97 |
Palantir’s continued execution on its AIP-led commercial expansion supports these projections. Sovereign AI demand could drove results well above this path, while a drop in government spending could pull them below it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.