The Most Aggressive Price Target in AI Right Now Belongs to CoreWeave
CoreWeave carries a backlog that dwarfs its closest rival and revenue growth that towers over legacy cloud giants, yet the stock still trades far below its 52-week high. Here is why the tension between a soaring opportunity and ballooning debt…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
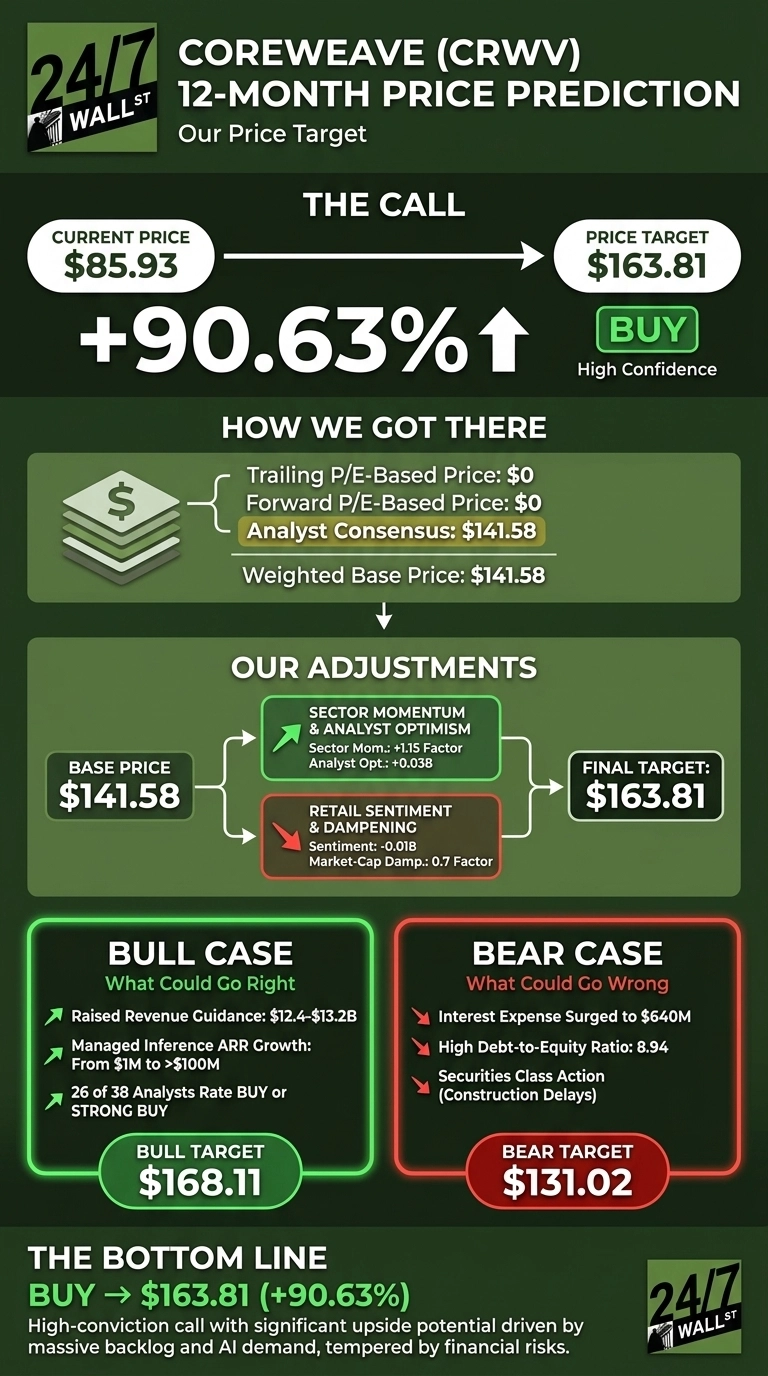
Our 24/7 Wall St. price target for CoreWeave (NASDAQ:CRWV) is $163.81 over the next 12 months. That means 90.63% upside from a reference price of $85.93.
| Metric | Value |
|---|---|
| Current Price | $85.93 |
| Price Target from 24/7 Wall St. | $163.81 |
| Upside/Downside | 90.63% |
| Model Rating | BUY |
| Confidence Level | 50% |
No AI name we cover has a bigger price target. The model leans on revenue growing over 100% per year and a signed backlog of $104 billion. Against that sit GAAP losses, heavy debt, and negative free cash flow. Confidence is moderate because of that tension.
Record Revenue and a Swelling Backlog Have Shares Climbing Again
CoreWeave shares traded at $88.51 early Wednesday, up 3%. The stock is up 2.02% for the week, 5.08% for the month and 23.6% year to date. It is still down 27.76% over the past year and sits well below its 52-week high of $153.2. The 52-week low is $60.55.
Q2 revenue came in at $2.575 billion, up 112.32%, slightly above the $2.555 billion estimate. GAAP EPS of -$1.14 beat expectations of -$1.447.
The backlog does not yet count more than $25 billion in new commitments signed early in Q3. CoreWeave was selected for the Nasdaq-100, and Barron’s this week compared CoreWeave against Nebius.
Why Bulls See $168 and Beyond
In the bull case, the stock reaches $168.11. Full-year guidance was raised to $12.4 to $13.2 billion and an approximately 25% increase across SKUs was pushed through in July.
Managed inference ARR grew from $1 million to more than $100 million. Of 38 analysts covering the stock, 26 rate it Buy or Strong Buy.
Surging Interest Costs Are the Risk to Watch
The bear case sits at $131.02. Interest expense hit $640 million, up from $267 million a year earlier. Q3 guidance calls for $860 to $940 million. Debt-to-equity stands at 8.94. CoreWeave faces a securities class action saying data center construction delays.
Bulls have a counterargument. Operating cash flow turned positive at $679 million, and adjusted EBITDA reached $1.51 billion. Management also cut its borrowing costs by almost 300 basis points.
How CoreWeave Compares to Nebius and Oracle
Nebius (NASDAQ:NBIS | NBIS Price Prediction) is CoreWeave’s closest pure-play rival. Its Q2 revenue grew 454.04%, yet its remaining performance obligations total just $37.5 billion. Nebius has the larger market cap despite the much smaller backlog, which makes our target look reasonable.
Oracle (NYSE:ORCL) gives a sense of what AI cloud looks like at scale. Its cloud infrastructure revenue rose 121%. Oracle’s free cash flow was still -$5.4 billion, so heavy spending is common across the group.
| Company | Market Cap | Latest Revenue Growth | Backlog/RPO |
|---|---|---|---|
| CoreWeave | $40.22B | 112.32% | $104B |
| Nebius | $58.53B | 454.04% | $37.5B |
| Oracle | $414.8B | 29.61% | $664B |
CoreWeave Price Prediction 2026-2030
Our 24/7 Wall St. price target of $163.81 has a buy rating at 50% confidence. What tips the scale is a backlog that should turn into revenue as new power comes online.
I’d view shares as attractive if adjusted operating margins reach the “low teens in Q4” as management guided. I’d grow cautious if interest costs keep outpacing margin increases.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $99.78 |
| 2027 | $186.25 |
| 2028 | $277.57 |
| 2029 | $368.84 |
| 2030 | $453.56 |
These projections assume CoreWeave keeps executing toward at least 8 gigawatts by 2030. Tighter credit markets or a slowdown in AI spending could send the stock well away from this path, in either direction.
The expansion also depends on the companies providing power, cooling, and networking behind the racks, a group we profiled in a free report on seven AI infrastructure suppliers that aren’t chipmakers.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.