CoreWeave Has the Ingredients for a Monster Rally. Here’s Our Price Target
CoreWeave is posting triple-digit revenue growth while its stock sits nearly 29% below year-ago levels, and that disconnect between momentum and price may not last much longer.

Few stocks capture the AI infrastructure gold rush like CoreWeave (NASDAQ:CRWV). The stock has pulled back from earlier highs while revenue more than doubles quarter after quarter.
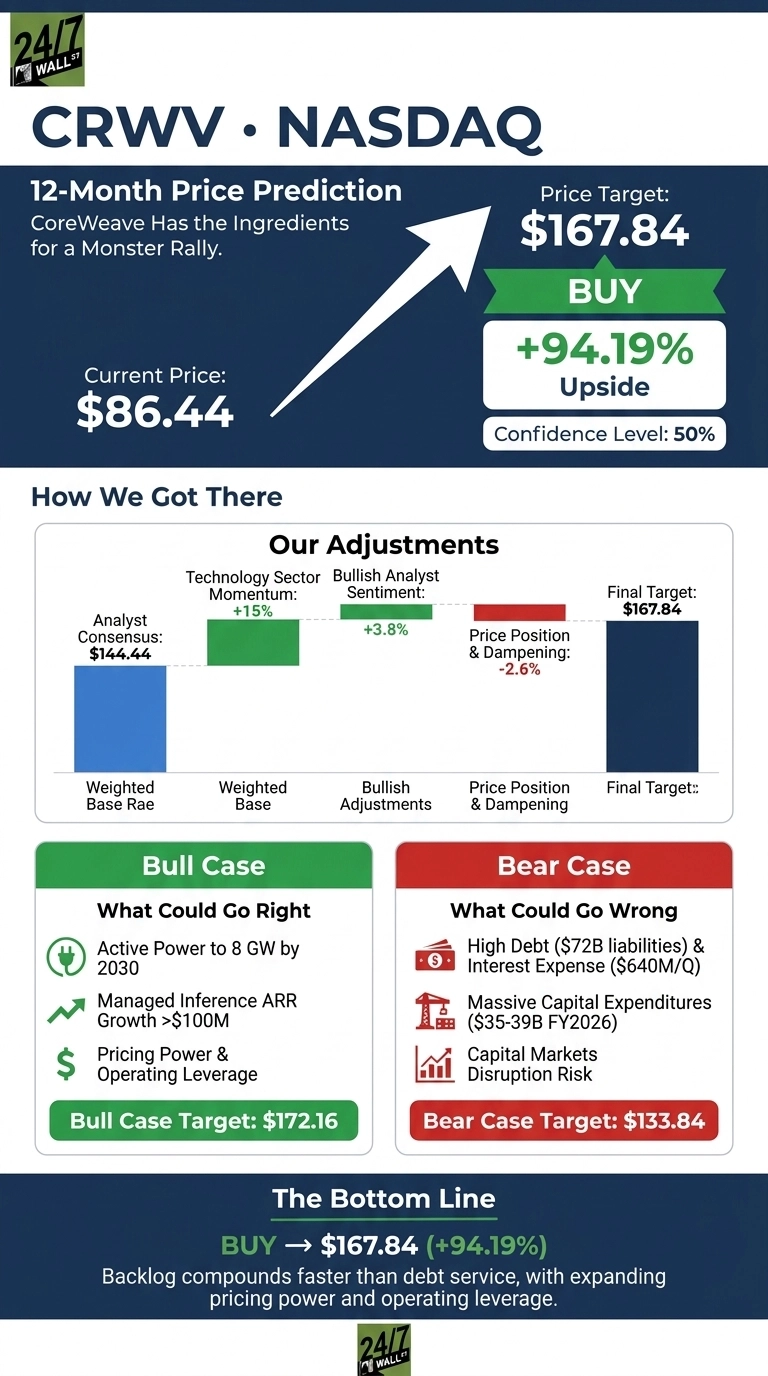
Our 24/7 Wall St. price target is $167.84, implying 94.19% upside from the current $86.44 share price. Our recommendation is buy, with a moderate 50% confidence level given the extreme leverage and capex intensity underlying the story.
| Metric | Value |
|---|---|
| Current Price | $86.44 |
| 24/7 Wall St. Price Target | $167.84 |
| Upside | 94.19% |
| Recommendation | BUY |
| Confidence | 50% |
A Volatile Year With a Breakout Quarter
CRWV is down 28.79% over the past year but up 20.71% year to date.
Q2 2026 was the pivot. Revenue hit $2.6 billion, up 112% year over year, with adjusted EBITDA of $1.5 billion at a 59% margin. Revenue backlog reached $104 billion, and management added more than $25 billion of new customer commitments in early Q3. Nasdaq-100 inclusion and a July pricing hike of roughly 25% across SKUs signal operating leverage ahead.
Why Bulls See a Breakout Ahead
CoreWeave is a scarce, AI-native GPU cloud in a supply-constrained market. Active power expanded to 1.5 gigawatts in Q2 with contracted power at 4.2 gigawatts, targeting at least 8 gigawatts by 2030. Recent contracts carried contribution margins 5 to 10 percentage points above earlier vintages.
Managed inference ARR rocketed from $1 million to over $100 million in months. Full-year 2026 revenue guidance was raised to $12.4 to $13.2 billion. Our bull-case scenario points to $172.16 over the next year.
What Could Go Wrong
The bear case centers on the balance sheet. Total liabilities of $72.05 billion, debt-to-equity of 8.94, and quarterly interest expense of $640 million mean capital markets disruption hits hard. Full-year 2026 capex guidance of $35 to $39 billion keeps free cash flow deeply negative.
A pending securities class action alleging concealed data center construction delays adds legal overhang. Management has reduced weighted average debt cost by nearly 300 basis points, saving roughly $1.1 billion annualized. Our bear-case landing spot is $133.84, still above today.
How CoreWeave Compares to Nebius and Oracle
Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) is the closest pure-play analog. Q2 2026 revenue of $582.30 million grew 454% year over year with remaining performance obligations of $37.49 billion.
At a $55.8 billion market cap, NBIS trades at a richer sales multiple than CRWV’s $39.67 billion market cap against a $104 billion backlog. That gap makes our CRWV target look conservative.
CoreWeave Price Prediction 2026-2030
The 24/7 Wall St. price target of $167.84 with a buy rating reflects one clear tilt: backlog is compounding faster than debt service, and pricing power is expanding.
The bull case rewards investors who can stomach the leverage and believe management hits the 8 gigawatts by 2030 milestone. For me, the operating leverage inflection tips the scale.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $90.12 |
| 2027 | $167.84 |
| 2028 | $261.50 |
| 2029 | $364.34 |
| 2030 | $452.45 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.