AppLovin Stock is Soaring 6.5% — Will It Break a 9-Day Losing Streak?
AppLovin just posted its first gain after nine straight losing sessions, but three separate problems dragged the stock down nearly 19% in under two weeks, and not all of them are solved yet.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

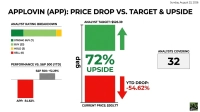
AppLovin (NASDAQ:APP | APP Price Prediction) rose 6.5% to $284.48 in morning trading on Oct. 5. The move is an attempt to end a nine-session losing streak. Daily closing prices confirm that streak: shares fell every session from September 22 through October 2, slipping from a $330.17 close on Sept.21 to $268.22 on Oct. 2. That is a drop of 18.76% in under two weeks. The stock is now down 57.78% year to date and 58.39% over the past year. The question is whether the business supports a recovery or whether this is a relief bounce in a stock that still carries heavy issues.

AppLovin (APP): Three Separate Overhangs Sank a Profit Machine
What Actually Went Wrong
The selloff comes from three separate problems, and each needs to be judged on its own.
1. The August revenue miss. Second-quarter revenue came in at $1.92 billion, missing the $1.94 billion consensus by 0.94%. EPS of $3.76 was roughly in line with the $3.7549 estimate. On the call, management blamed the timing of its AI model upgrades. Adam Foroughi said “our pace of meaningful model improvement was lighter than normal during the quarter, and the next step up in model performance landed just after quarter end.” The market did not accept that explanation. Shares went from $433.71 at filing to $346.80 one day later and $312.67 a week after. A securities fraud class action tied to the miss now adds legal pressure, with a lead plaintiff deadline of November 16.

2. The Unity lawsuit blow. AppLovin had asked a court to stop Unity Software (NYSE:U) from using its ad auction data to train or improve competing AI tools (according to coverage of the filing). On Friday, October 2, the court denied AppLovin’s request for a temporary restraining order. Wedbush said the ruling signals a competitive shift that could pressure MAX take rates. MAX is AppLovin’s mediation platform for app publishers, and this is a structural concern separate from the earnings miss.
3. Doubts about the consumer ad push. A note from Wells Fargo (NYSE:WFC) called a spike in Pixel downloads a “false start”. That cast doubt on how fast AppLovin’s e-commerce advertiser base is really growing. HSBC (NYSE:HSBC) cut its price target to $409 from $450 but kept a Buy rating. The Street mean target sits near $497.

Named Catalyst: A Model Upgrade Already Live for Q3
The recovery case rests on one specific event: the model improvement that went live just after the second quarter ended. Management said it was already helping growth pick up again and that “Q3 is off to a strong start.” According to Foroughi, after the release, advertisers reported that “install rates went up, CPIs went down, performance has improved.”
Third-quarter guidance puts numbers on that claim:
- Revenue of $2.055 billion to $2.085 billion, up 46% to 48% year over year and 7% to 8% from Q2
- Adjusted EBITDA of $1.71 billion to $1.74 billion, at an adjusted EBITDA margin of about 83%
- Guidance includes model improvements already running but leaves out any new model releases not yet deployed
A second, slower-moving catalyst is the public launch of AppLovin Ads Manager, which is aimed first at mid-market e-commerce advertisers. Consumer advertiser spending ended Q2 28% above Q4 2025 levels. That gain came even though Q4 is the seasonal peak for those advertisers.
Valuation Has Reset From 69x to 24x Earnings
The stock has fallen much faster than earnings. At the end of 2025, shares closed at $673.82 against full-year 2025 EPS of $9.75, roughly 69x trailing earnings. Today the trailing P/E is about 24. Over the same period, quarterly EPS rose from $3.24 in Q4 2025 to $3.76 in Q2 2026. The price-to-free-cash-flow ratio stands at 20.71, a free cash flow yield of 4.83%.

Profitability is still strong. Q2 revenue grew 52.82% year over year. Net income reached $1.27 billion, and adjusted EBITDA margin rose to 84% from 81%. Buybacks continued: $551.3 million in Q2, following about $1.0 billion in Q1.
What Has to Go Right
- Q3 revenue at or above the guided range. A result inside $2.055 billion to $2.085 billion would support management’s view that the Q2 miss was a timing issue.
- Stable MAX share despite Unity. In August, management said its “share of publisher waterfalls remained consistent.” That needs to hold after the court ruling.
- Computing spending that pays for itself. Management said about 10 cents of each new revenue dollar goes to compute, and it is aiming for a long-term adjusted EBITDA margin in the low 80% range.
- More consumer advertisers. Management admitted the consumer business currently relies on “few advertisers contributing more today.” It needs to show that base rose.
What Would Break the Comeback Case
The case fails if Q3 revenue comes in below $2.055 billion. That would mean a model upgrade already in the guidance could not deliver, which would turn the “timing” explanation into a fundamental problem. Margin guidance falling below the low 80s would point to rising computing costs without matching revenue. Evidence that Unity is winning publisher mediation share would confirm Wedbush’s take-rate warning. Management also acknowledged that Android is more competitive because “there’s a very big competitor out there doing well there.”
Options and Retail Positioning on the Bounce
The full-chain put/call ratio is 0.55, which points toward calls. Calls expiring October 9 at strikes from $257.50 to $322.50 show volume above open interest, a sign of fresh trading activity. That data alone does not show whether traders were buying or selling. Reddit opinion improved to 77.52 from 60, though activity remains low. One recent post framed the debate as “AppLovin mispriced opportunity or value trap?” The rebound is also happening on below-average volume, which fits a bounce from oversold levels more than a lasting reversal.
The fundamentals support the recovery case better than the chart does: revenue growth above 45%, margins in the 80s, and a multiple that has fallen from about 69x to 24x earnings. One rebound session does not clear the Unity ruling, the class action, or the doubts about consumer ads. The Q3 earnings report is the real test. Revenue inside the guided range supports a re-rating. A result below $2.055 billion would show this bounce was a dead-cat rally, so keep an eye on the stock through that report.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.