Ondas Is Priced Like a Defense Contractor. AeroVironment Actually Is One.
Ondas Holdings carries a valuation that rivals an established defense prime, yet its financials tell a very different story. Before retirement investors treat these two drone stocks as comparable bets, the gap between their revenue, profitability, and risk profiles deserves…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
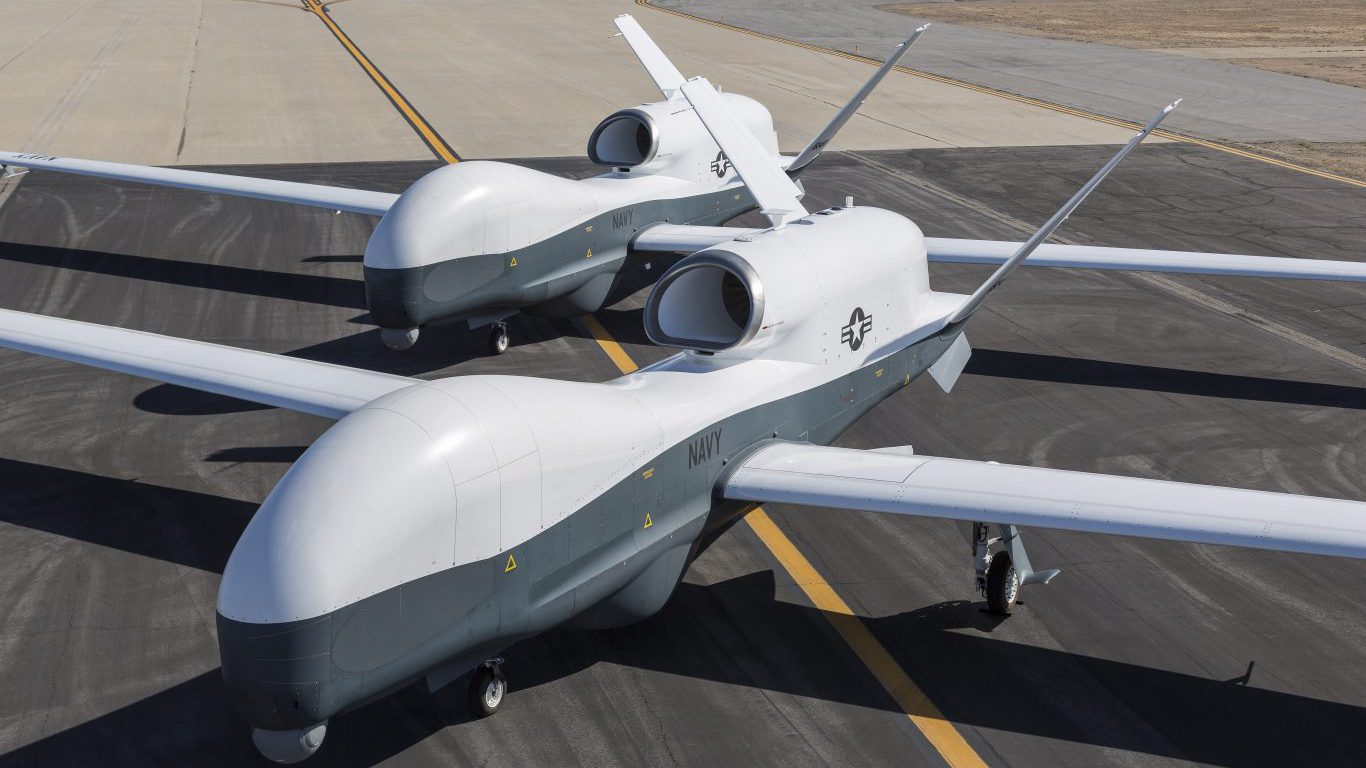
For a retirement-focused investor, is Ondas Holdings (NASDAQ:ONDS) or AeroVironment (NASDAQ:AVAV | AVAV Price Prediction) the better holding as of October 2026? Both trade as drone stocks, but only AeroVironment sells into established U.S. Army programs at scale. Its trailing revenue of $2.0 billion is roughly 11.5 times Ondas’ $174.1 million. Even so, Ondas carries a market value of about $4.2 billion, or 58% of AeroVironment’s $7.2 billion.
AeroVironment Produces Program Revenue While Ondas Builds Its Base
On September 9, 2026, AeroVironment reported fiscal first-quarter 2027 revenue of $480.5 million, up 6% year over year. Adjusted EPS came in at $0.59, beating the $0.25 estimate. The revenue comes from named, recurring franchises: Switchblade, Puma, P550, Titan, and the LOCUST laser, which won a $464 million Army production contract. Funded backlog reached a record $1.5 billion, up 37%, and management said it had 86% revenue visibility to the center of fiscal 2027 guidance. Backlog is contracted future work that has not yet been recognized as revenue. With a 1.4x book-to-bill, new orders are coming in faster than revenue is being booked.

Ondas posted revenue of $83.8 million for the quarter ended June 30, 2026, along with a net loss of $89.7 million. Its growth comes from acquisitions: it closed five in the first quarter of 2026 alone. First-quarter net income of $361.25 million came from a $389.55 million non-cash warrant gain. Adjusted EBITDA for that quarter was still a $10.88 million loss, and operating cash flow was negative $51.3 million. Its $457 million pro forma backlog has yet to convert into recognized revenue.

AeroVironment wins this round easily.
Ondas Costs 24 Times Sales, AeroVironment About 3.6
Ondas trades at about 24 times trailing sales. Using its own raised target of at least $390 million in fiscal 2026 revenue, the multiple is still about 11 times. AeroVironment trades at 3.6 times trailing sales. It trades at about 3.3 times the center of its $2.13 billion to $2.23 billion revenue guidance. Ondas’ multiple pays for revenue it has not yet booked, from acquisitions it is still integrating. It also prices in profitability that management does not expect until Q1 2028. AeroVironment guides to non-GAAP EPS of $3.02 to $3.34.
AeroVironment wins on valuation.
AeroVironment’s Drawdown Comes With a Record Ondas Lacks
From October 2, 2025, to October 5, 2026, AeroVironment fell 60.6% to $141.88. That is steeper than Ondas’ 19.7% decline over the same period. Fiscal 2026 hurt AeroVironment. Termination of the SCAR program removed $1.5 billion from unfunded backlog and led to a $240.7 million goodwill impairment and a GAAP net loss of $265.1 million.
Over longer periods, AeroVironment gained 482.9% from October 4, 2016, to October 5, 2026. Ondas lost 18.7% from October 1, 2021, to October 5, 2026, and posted negative operating income in every year from 2020 through 2025. Ondas has about $1.03 billion in cash, but that runway came from equity raises. It also carries a $1.06 billion warrant liability that drives earnings swings, plus $19.7 million per quarter in stock-based compensation.
AeroVironment wins on risk. Its drawdown repriced a profitable franchise, while Ondas’ risk is built into how it funds and grows the business.
Verdict: AeroVironment Offers the Steadier Profile for Retirement-Focused Investors
AeroVironment is the better fit for an investor at or near retirement. It has adjusted profitability and $675 million in cash and investments, against $747.5 million of zero-coupon convertible notes. Its execution risks, from budget timing to the LOCUST production ramp, are the usual risks a defense prime carries. Ondas’ profile lines up more closely with investors who have long time horizons and can absorb dilution and integration risk. These two stocks carry very different risk profiles, and Ondas carries risk well above what a retirement-focused investor typically seeks.
To change this assessment, Ondas would need to report fiscal 2026 revenue of at least $390 million, then post positive company-wide adjusted EBITDA without raising more equity. Until its reported results show both, AeroVironment is the actual defense contractor and Ondas is only priced like one.


Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.