The Cost to Ship Oil Just Exploded 3,900% — and Americans Could End Up Paying for It
A tanker rate that barely registered in January just sent shockwaves through global energy markets, and the ripple effects could reach your gas tank, your grocery bill, and your investment portfolio before most Americans see it coming.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
America’s energy advantage offers less protection from overseas turmoil than investors might expect. Domestic drilling helps, but the price of filling your tank still reflects competition for oil around the world. The U.S. Energy Information Administration identifies crude oil as gasoline’s largest cost component, meaning trouble far from American shores can reach household budgets surprisingly quickly.
That makes oil shipping costs more than a concern for tanker operators. For investors, the challenge is separating businesses that could benefit from expensive energy from those forced to absorb it. A diversified energy investment deserves your consideration, but an eye-catching freight rate alone is no reason to buy.
The Shocking Cost of Moving Oil Around the World
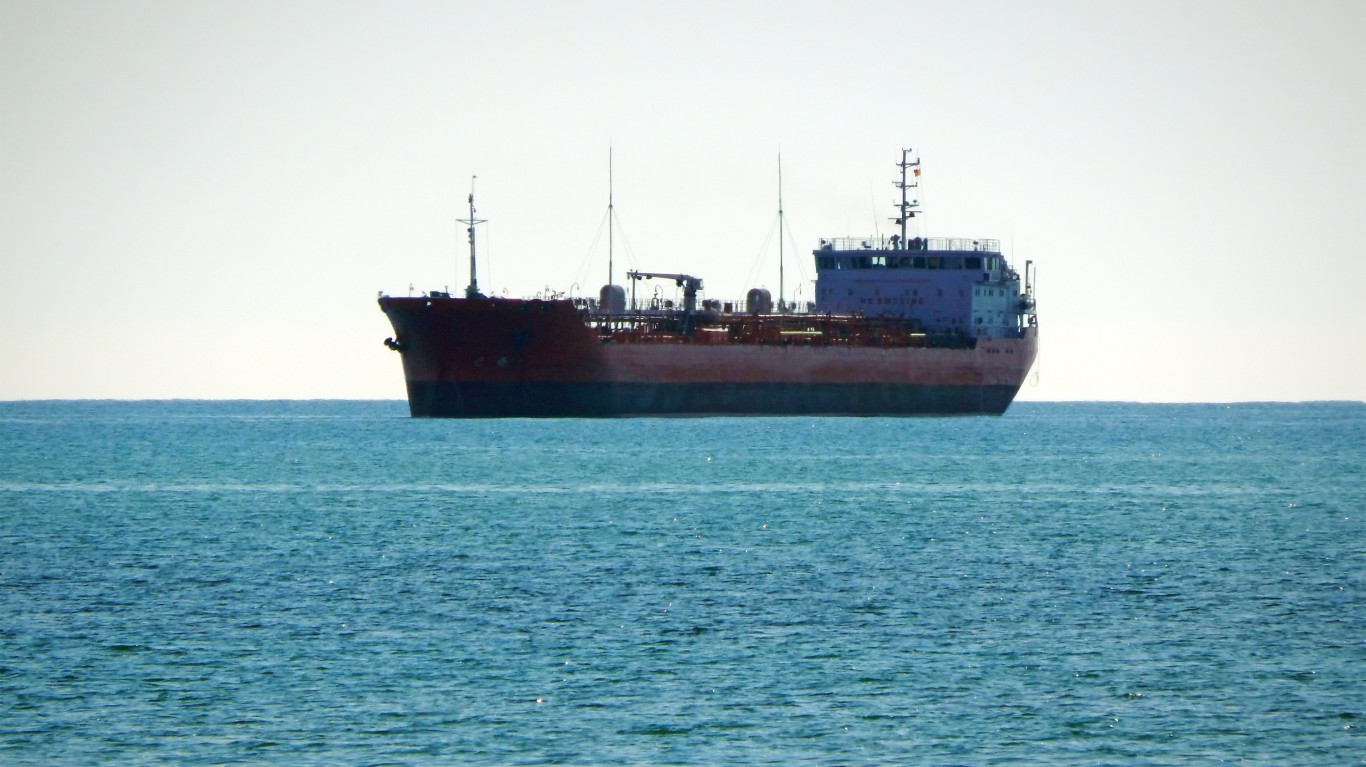
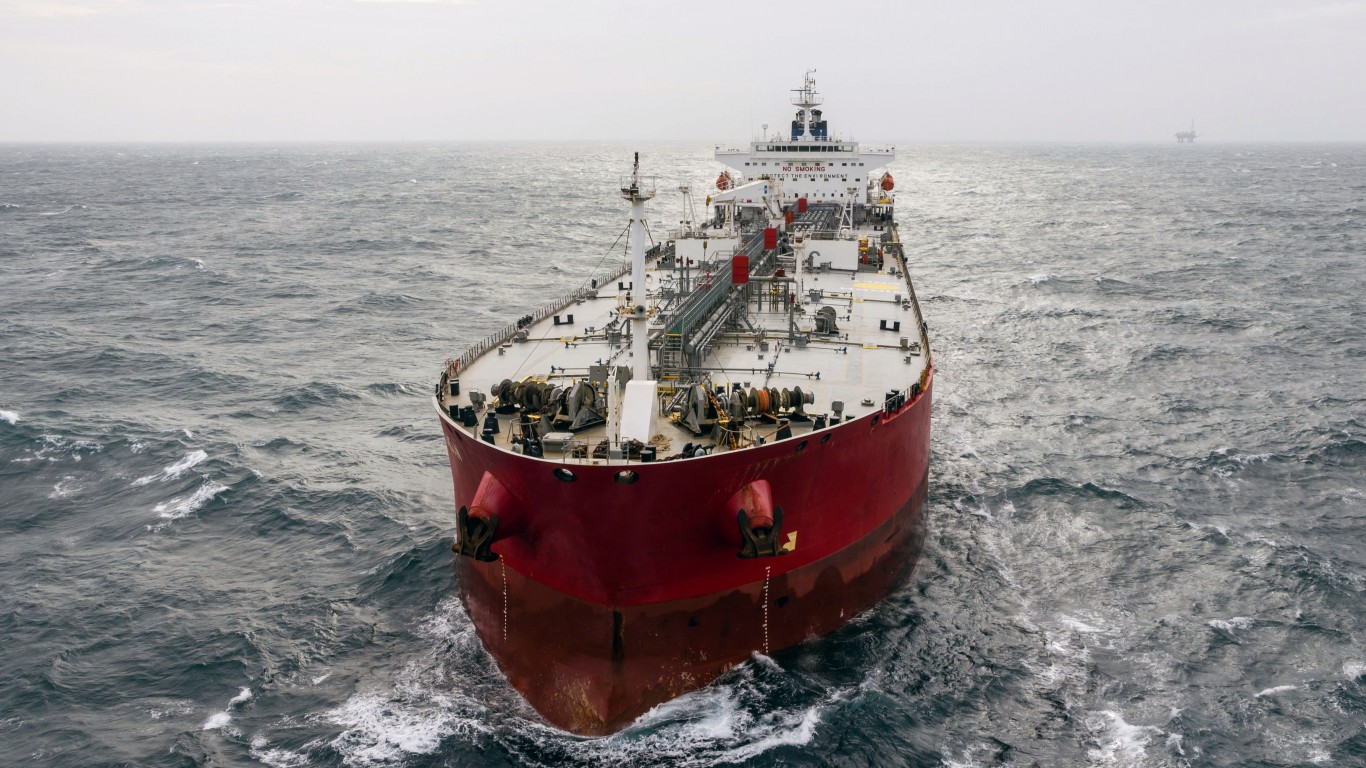
Reuters cited a shipping broker Poten & Partners report that very large crude carrier (VLCC) rates from the Middle East to Asia recently exceeded $1.2 million daily. In January, the very same ship cost just $30,000 a day. That is approximately 40 times the starting rate — a 3,900% increase.
Freight’s share of the delivered cost of oil expanded from around 3% to 27% as longer voyages and tanker transfers around the Strait of Hormuz are tying up vessels.
There is an important caveat, though. This measures a particular tanker market. It does not mean every oil shipment costs 40 times more. Nor does a 3,900% freight increase translate into a matching jump at the pump. Shipping is but one expense within a much larger bill. Producers, refiners, and distributors may absorb part of the pressure. The eventual consumer impact depends on how long disruption lasts and how readily buyers find affordable alternatives.
Why Americans Could Pay More
America’s direct exposure needs some perspective. The EIA’s April 6 analysis reported these figures for 2025:
| U.S. Crude Import Measure | Amount |
| Total crude imports | 6.2 million barrels daily |
| Middle East Gulf imports | 490,000 barrels daily |
| Middle East Gulf share | 8% |
| West Coast share of those Gulf imports | 47% |
The agency also found that 88% of Middle East Gulf imports were medium sour crude — oil with characteristics certain refineries are equipped to process. Domestic production cannot replace every imported barrel interchangeably.
But direct imports explain only part of the risk. The EIA describes oil prices as reflecting global supply and demand. When overseas buyers compete for replacement supplies, American refiners can face higher prices even when their barrels never travel through Hormuz.
The potential household impact extends beyond gasoline. Higher diesel costs can increase delivery expenses, creating pressure on grocery and merchandise prices. Businesses must absorb those costs, offset them elsewhere, or try to pass them along.
For scale, a hypothetical 25-cent-per-gallon increase would cost a household buying 80 gallons monthly another $20. That illustrates the budget sensitivity; it is not a forecast derived from tanker rates.
For shareholders, the same arithmetic becomes a profit-margin test. A hypothetical delivery business purchasing 100,000 gallons monthly would face $25,000 in additional monthly expenses under that scenario. If customers resist higher delivery charges, shareholders absorb the difference through lower earnings. Pricing power therefore deserves attention alongside sales growth when evaluating fuel-dependent businesses.
An Investment Opportunity With Limits
My preference is diversified energy exposure over chasing a shipping windfall. Vanguard Energy ETF (NYSEARCA:VDE) tracks U.S. energy stocks across company sizes. Vanguard lists a 0.09% expense ratio, equivalent to approximately $9 annually per $10,000 invested.
It spreads company-specific risk, although it remains concentrated in one sector. Investors should also distinguish producers, which can benefit from higher selling prices, from refiners, whose results depend on fuel prices relative to crude costs.
Before buying, compare a producer’s free cash flow with its dividend commitments, and examine whether debt remains manageable under lower oil prices. For tanker operators, check how much capacity can capture current rates versus existing contracts. Neither business should require today’s exceptional conditions to justify the price investors pay today.
Key Takeaway
Put diversified energy exposure on your watch list, and evaluate purchases against your existing allocation. The 3,900% shipping spike strengthens the case for reviewing energy risk, but it cannot establish that energy stocks are cheap.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.