Intel’s Biggest Opportunity May Be Its Comeback
After years of losses and stumbles, Intel has strung together seven consecutive quarters of beating its own expectations, and the gap between its bull and bear cases now spans nearly $40 per share. Which side of that divide you land…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
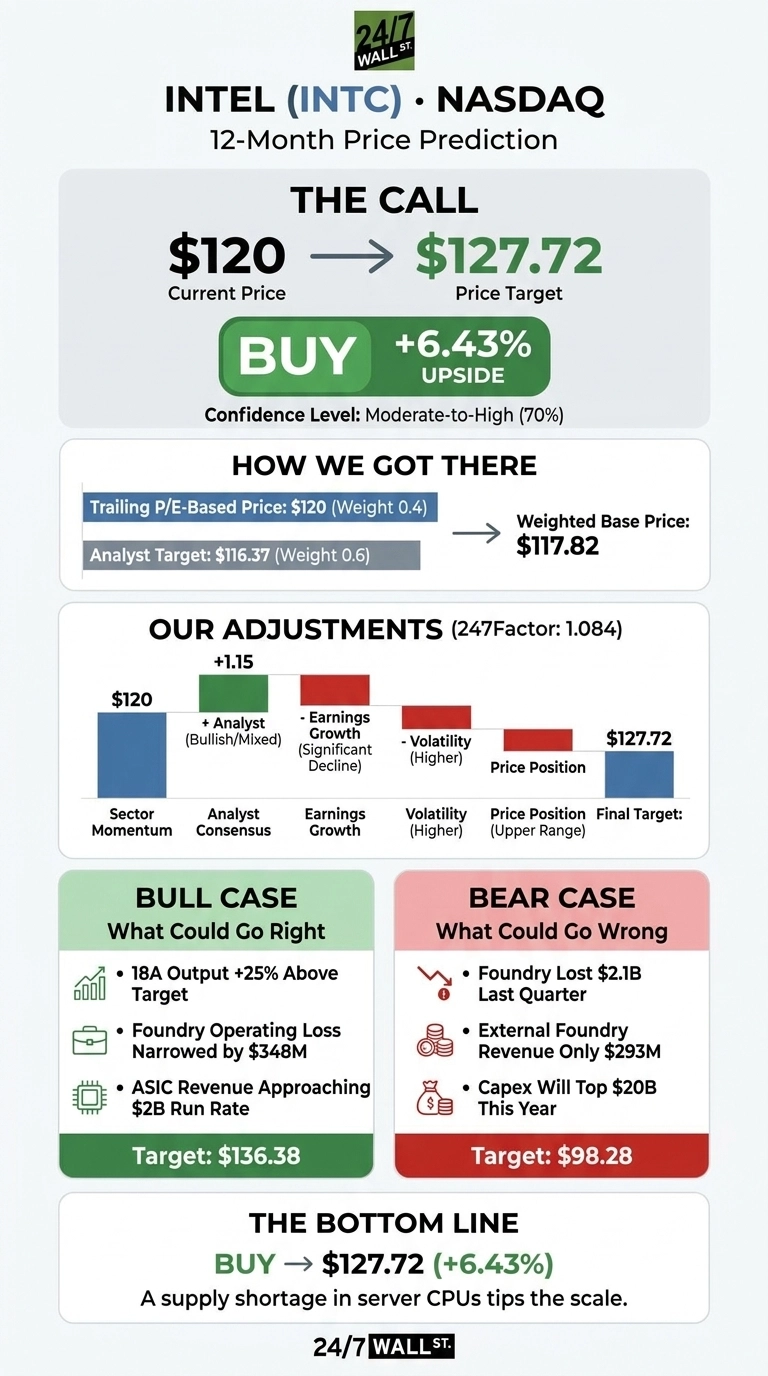
The 24/7 Wall St. price target for Intel (NASDAQ:INTC | INTC Price Prediction) is $127.72 over the next 12 months. From a reference price of $120, that means 6.43% upside. The stock earns a buy rating with moderate-to-high confidence.
| Metric | Value |
|---|---|
| Current Price | $120 |
| Price Target from 24/7 Wall St. | $127.72 |
| Upside/Downside | 6.43% |
| Recommendation | BUY |
| Confidence Level | 70% |
Most of the turnaround is already priced in, but the trend backs a constructive view. Lip-Bu Tan’s Intel has beaten its own financial expectations for seven consecutive quarters. Demand for server CPUs is running ahead of supply, and the 18A manufacturing node is producing more than planned.

Seven Straight Beats Fuel a 230% Rally
Intel shares are up 230.87% year to date and 37.23% over the past month. They sit 18% below the 52-week high of $142.35. September’s rally reflected growing optimism about tight server CPU supply supporting Intel’s AI infrastructure role.
Second-quarter revenue rose 25.4% to $16.13 billion, beating the $14.45 billion consensus. Non-GAAP EPS of $0.42 beat the $0.2175 estimate, and Data Center and AI revenue climbed 59%. Even so, the stock fell 7.89% on earnings day. For the third quarter, Intel guided to revenue of $15.8 billion to $16.8 billion.

Why Bulls See $136 and Beyond
Intel’s 18A output ran about 25% above target. The Foundry operating loss narrowed by $348 million from the prior quarter. ASIC revenue is approaching a $2 billion run rate, with management aiming for $4 billion.
High-volume 14A production is planned for 2028. Recent insider activity shows net buying, and 14 analysts rate the stock Buy or Strong Buy. In the bull scenario, Intel reaches $136.38.

Foundry Losses and Rising Capex Could Test Patience
Intel Foundry lost $2.1 billion last quarter with external foundry revenue of only $293 million. Capex will top $20 billion this year. Of the analysts covering the stock, 32 rate it hold.
Our bear scenario is $98.28. The GAAP loss was driven by a non-cash $12.53 billion mark-to-market charge on CHIPS Act escrow, while operating cash flow reached $7 billion.
Intel Trades on Recovery While AMD and NVIDIA Trade on Earnings
Advanced Micro Devices (NASDAQ:AMD) is Intel’s most direct CPU rival, with revenue growth of 50.11% last quarter and a trailing multiple of 232x.
NVIDIA (NASDAQ:NVDA) trades at a lower 46x multiple with a 71.1% gross margin. Intel’s 34.77% gross margin gives the most room to expand.
| Company | Trailing P/E | Gross Margin | Latest Qtr Revenue Growth |
|---|---|---|---|
| Intel | Negative | 34.77% | 25.4% |
| AMD | 232x | 49.5% | 50.11% |
| NVIDIA | 46x | 71.1% | 105.85% |
Comeback Momentum Earns a BUY Rating
The 24/7 Wall St. price target of $127.72 comes with a buy rating at 70% confidence. A supply shortage in server CPUs tips the scale for me.
A shortage is a far easier problem to fix than weak demand. My view gets stronger if new capacity lands in the fourth quarter as planned and external foundry customers sign on. I would turn cautious if Foundry losses stop narrowing while capex keeps rising.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $127.72 |
| 2027 | $134.95 |
| 2028 | $142.59 |
| 2029 | $150.66 |
| 2030 | $159.18 |
These figures assume Intel delivers on its current plan. The 14A node ramp and external foundry customer wins are the biggest swing factors.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.