Prediction: The Next Chapter of Supermicro Could Be More Important Than the Last
Supermicro booked $60 billion in new orders and targets $72 billion in revenue, yet Wall Street still rates it a near-sell. Here is what analysts are missing and the three conditions that could send shares to $70 by 2027.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction | SMCI Price Prediction) wants to be more than a server assembler. The San Jose company booked more than $60 billion in new orders last quarter. It now targets fiscal 2027 revenue of $65 billion to $72 billion, up from $39.1 billion in fiscal 2026.
Shares are up 48.31% year to date and still trade at about 10x forward earnings. That gap raises the question of whether Supermicro can hit $70 per share in 2027.

What’s Holding Supermicro Back Below Its 52-Week High
The stock has momentum: shares rose 4.58% over the past week and 18.25% over the past month. Even so, they are still down 17.14% over the past year.
Credibility weighs on the stock, as revenue missed estimates in five of the last six quarters. Fiscal 2026 operating cash flow came in at negative $6.8 billion, and the company raised $5.6 billion in equity.
Q1 gross margin guidance of 10.4% to 10.8% sits far below Q4’s 17.6%. An update on the board inquiry is still pending. The stock’s beta is 1.996, so each of these worries hits shares roughly twice as hard as the broader market.
Wall Street Sees No Upside. Our Model Says 12.4%
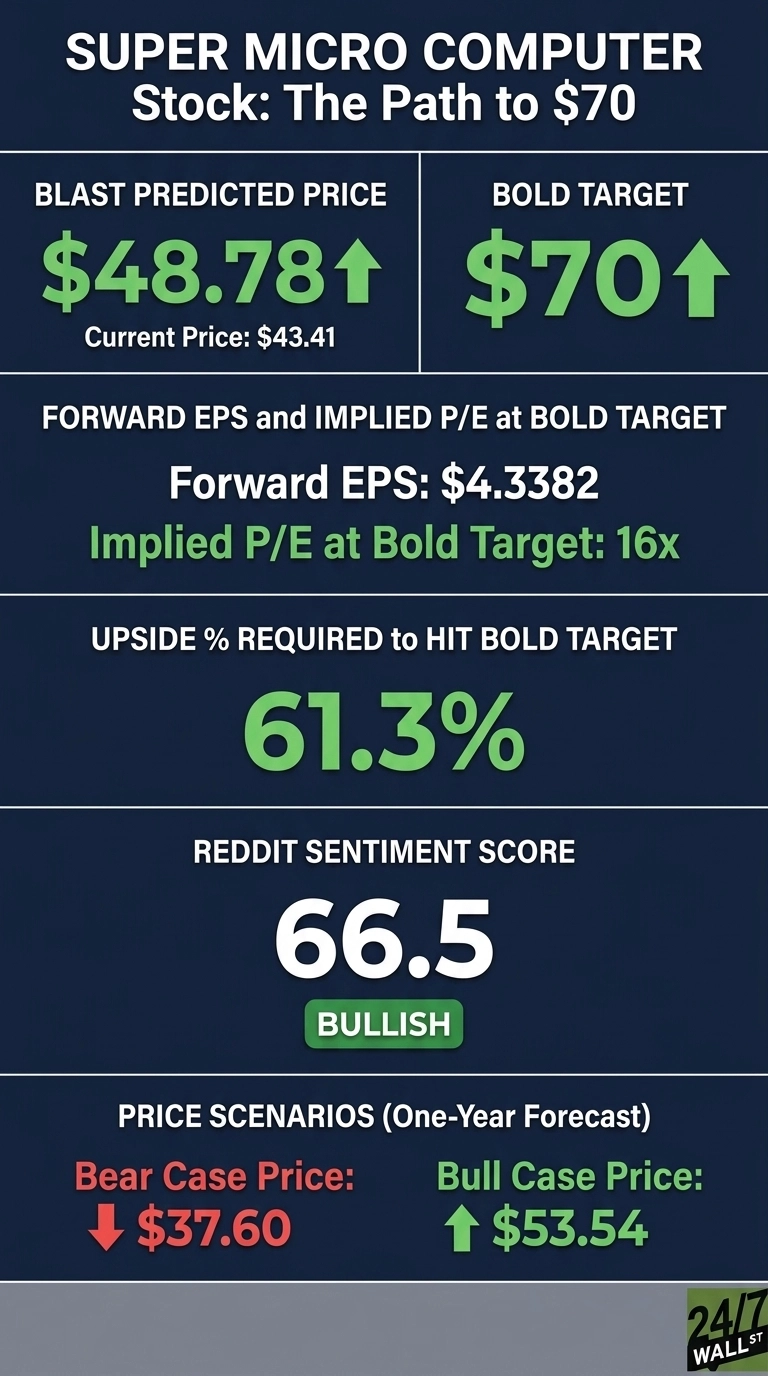
The consensus target is $42.38, about 2.4% below today’s $43.41. Analysts rate it 2 Strong Buys, 3 Buys, 11 Holds, 2 Sells and 1 Strong Sell. Our base case is $48.78, or 12.4% upside. The model’s range runs from $37.60 in the bear case to $53.54 in the bull case, and confidence is high at 0.9.
In my view, analysts are stuck on to old disappointments. Only 26% of them are bullish. In our adjustment, earnings growth contributed 0.03, five times the 0.006 from analyst views. Fundamentals are improving faster than the ratings.
Here’s What It Takes for Supermicro to Reach $70
Getting to $70 from the current $43.41 calls for a 61.3% gain. Forward EPS is $4.3382, so $70 equals to a forward P/E of 16x. Our base case already implies 12x, which means the bold target needs 5x of additional multiple expansion.

That seems achievable. Forward EPS already exceeds fiscal 2026’s $3.63, so the forward multiple falls if guidance holds. Enterprise and channel revenue rose 172% to $5.6 billion in Q4.
CEO Charles Liang said “we are improving profitability through a richer enterprise customer mix and broader adoption of our optimized Data Center Building Block Solutions (DCBBS) architecture.”
Supermicro is one of the picks-and-shovels names behind the AI data-center expansion (we covered seven of these suppliers, from power to cooling, in a report you can download here). The main risk is that power and cooling delays push backlog shipments into later quarters.
Mizuho analyst Vijay Rakesh raised the firm’s price target on Super Micro to $43 from $35 and keeps a Neutral rating on the shares.

Supermicro Trades at a Discount to Its Earnings Power
At $43.41, shares trade at 10x forward EPS. That looks cheap for a business that grew revenue 78%, though cash flow concerns explain part of the discount.
Shares range from a 52-week low of $19.48 to a high of $58.78. Over 10 years, the stock has returned 1,748.02%. A $70 price would still leave Supermicro at a mid-teens multiple.
$70 Is a Stretch, but Here’s Why It’s Possible
Reaching $70 in 2027 calls for a 61.3% advance. I see it as a stretch that is still within reach. Three conditions must be met. First, record backlog has to convert into revenue near the top of guidance.
Second, gross margins need to hold as the enterprise and DCBBS mix grows. Third, operating cash flow has to turn positive without more dilution. Another revenue miss or a bad board inquiry outcome would ruin it. Investors shouldn’t expect this level of return every year, but we’ve outlined the plan for how Super Micro Computer could reach $70 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.