Amazon Stock Has Another Growth Story Investors May Be Missing
Everyone knows the AWS story, but three faster-growing businesses quietly running alongside it could change how investors value Amazon entirely.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
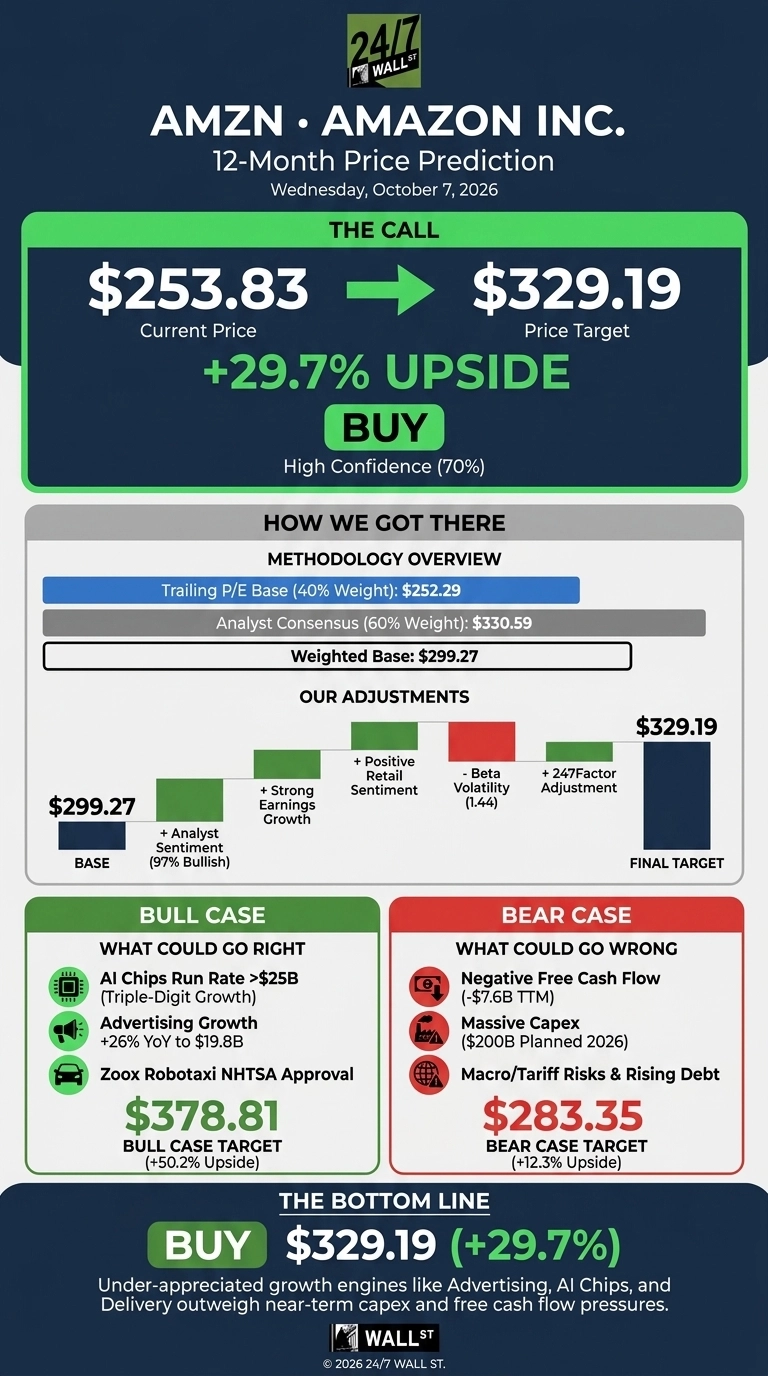
The 24/7 Wall St. price target for Amazon (NASDAQ:AMZN | AMZN Price Prediction) is $329.19 over the next 12 months. With the stock at $253.83, that target means 29.7% upside. Amazon earns a buy rating with fairly high confidence from our model.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $253.83 |
| Price Target from 24/7 Wall St. | $329.19 |
| Upside/Downside | 29.7% |
| Recommendation | BUY |
| Confidence Level | 70% |
Most of the debate centers on AWS. The less-discussed story is everything around it. Advertising grew 26% to $19.8 billion last quarter, the chips business passed a $25 billion run rate with triple-digit growth, and Amazon Now gross sales grew more than 80% from the prior quarter. Of the analysts covering Amazon, 58 of 60 rate it a Buy or Strong Buy.

Shares Trail Their High Despite a Record AWS Quarter
Amazon is up 2.9% over the past week, down 1.81% over the past month, and up 9.97% year to date. It stands 11.6% below its 52-week high of $287.20 and 29.5% above its low of $196.
Second-quarter revenue rose 19.6% to $200.61 billion, ahead of the $196.43 billion estimate. GAAP EPS of $5.75 included a $53.4 billion gain, mostly from Amazon’s Anthropic stake. Excluding that gain, EPS came to about $1.88, slightly ahead of the $1.83 estimate.
AWS grew 37% with a 39.4% operating margin. For the third quarter, Amazon guided operating income to $22.5 billion to $26.5 billion, compared with $17.4 billion a year earlier.

Ads, Chips, and Delivery Could Carry Amazon Toward $379
AWS backlog reached $496 billion, with Anthropic and OpenAI making “multi-year, multi-gigawatt commitments” to Trainium. CEO Andy Jassy said there is “a real chance” Amazon will sell Trainium chips to external customers.
Advertising is accelerating: shoppers clicking sponsored prompts “convert to a sale 48% more often.” Amazon Business runs at $60 billion annualized gross sales. Zoox received NHTSA approval for paid robotaxi service. The bull case puts the stock at $378.81.

Free Cash Flow Is the Pressure Point
Trailing free cash flow is negative at -$7.6 billion. Amazon plans $200 billion in 2026 capex, and long-term debt rose to $119.1 billion from $65.6 billion. All of that expansion has to be powered, cooled, and networked by somebody, and we put seven of those suppliers in a free report on the companies behind the AI data-center boom.
Anthropic gains will not repeat, and tariffs add risk. Management says servers break even in “a little less than three years,” with most AI capacity signed for “at least five-year terms.” Even our bear case of $283.35 stands above today’s price.
Amazon Screens Cheaper Than Walmart, Richer Than Alphabet
| Company | Trailing P/E | Operating Margin |
|---|---|---|
| Amazon | 36 | 11.16% |
| Microsoft | 29 | 46.8% |
| Alphabet | 15 | 32.1% |
| Walmart | 39 | 4.2% |
AWS’s main cloud rival is Microsoft (NASDAQ:MSFT). Azure grew 43%, faster than AWS, but AWS is accelerating while Microsoft’s stock trades at a lower multiple.
Competition in cloud and advertising also comes from Alphabet (NASDAQ:GOOGL). Google Cloud grew 82%, though its low P/E shows a $99.03 billion equity gain.
Walmart (NASDAQ:WMT) is Amazon’s retail media rival. Its ad business grew 38%, yet Walmart trades at a higher P/E with much lower margins. The peer group supports our target.
Amazon Price Prediction 2026-2030
The 24/7 Wall St. price target of $329.19 has a buy rating and 70% confidence. Higher-margin advertising and chip revenue are growing faster than retail.
The case strengthens if AWS keeps accelerating and capex converts to free cash flow by 2027. It weakens if spending rises while advertising or AWS growth slows. On balance, reward outweighs risk.
Here is where our model projects Amazon trading in the years ahead, assuming current growth and market conditions continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $252.29 |
| 2027 | $322.66 |
| 2028 | $385.41 |
| 2029 | $464.01 |
| 2030 | $501.52 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.