Prediction: Tesla Stock Has a Wild Card That Could Change Its Long-Term Value
Tesla is burning through cash, missing earnings estimates, and trading at a valuation that stretches belief, yet one wild card in its portfolio could rewrite the entire story for 2027.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The automaker’s CEO has called 2026 a “massive CapEx year,” and the results show it. Tesla (NASDAQ:TSLA | TSLA Price Prediction) is building Robotaxi fleets, Optimus production lines, AI chips and a semiconductor fab simultaneously.
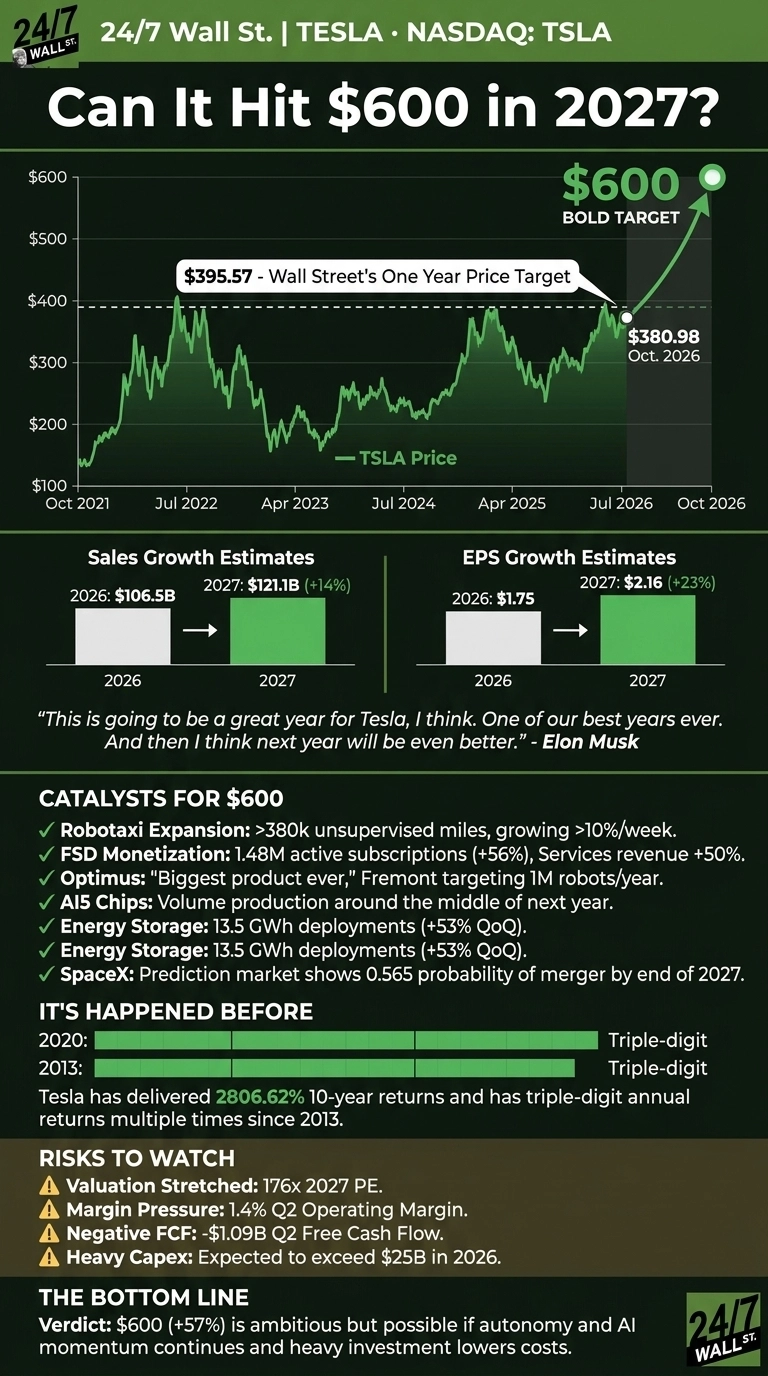
On the second-quarter call, Elon Musk said, “This is going to be a great year for Tesla, I think. One of our best years ever. And then I think next year will be even better.”
Shares are down 15.29% year-to-date at $380.98, though they’ve gained 7.6% over the past month. Autonomy is the key variable for the stock.

Wall Street Sees Little Upside, Which Leaves Room for a Surprise
The consensus price target is $395.57, only about 4% above current levels. Analysts are split, with 19 buys, 20 holds and 4 sells. The 2027 EPS forecast is $2.1630, down from $2.5615 90 days ago.

The Street models roughly 14% revenue growth and 23% EPS growth in 2027. Tesla has exceeded revenue estimates for four straight quarters. Second-quarter EPS of $0.33 missed the $0.5367 estimate as operating expenses rose 47%.
UBS analyst Joseph Spak raised the firm’s price target on Tesla to $391 from $385 and keeps a Buy rating on the shares.
Here’s What It Takes for Tesla to Reach $600
Tesla trades at about 176x 2027 earnings. At $600, that multiple would rise to roughly 277x. Against the bullish analyst estimate of $3.65, it would be about 164x. That multiple tops auto-sector valuations, so the case for $600 rests on valuing Tesla as an AI platform.
A few factors could drive Tesla to $600.
- Robotaxi expansion: Tesla has logged more than 380,000 miles of unsupervised driving, with miles growing “more than 10% a week.”
- FSD monetization: Active subscriptions reached 1.48 million, up 56%, and Services revenue rose 50%.
- Optimus: Musk said, “I think Optimus will be the biggest product ever.” The Fremont line targets 1M robots/year.
- AI5 chips: Volume production could begin around the middle of next year.
- Energy storage: Deployments reached 13.5 gigawatt hours, up 53% from the prior quarter.
- SpaceX: Prediction-market traders put the probability of a Tesla-SpaceX merger announcement by end of 2027 at 0.565.
Tesla’s History Shows 57% Gains Are Within Reach
Reaching $600 would require a gain of about 57%. Tesla posted triple-digit returns in 2020 and 2013. Over 10 years, shares are up 2806.62%. With a beta of 1.845 and a 52-week range of $297.38 to $498.83, large swings are normal.

Operating margin was 1.4% last quarter, free cash flow came in at -$1.092 billion, and 2026 capital spending is expected to exceed $25 billion. Tesla has $43.524 billion in cash to fund it.
$600 Is a Stretch, but Autonomy Could Get Tesla There
A 57% gain tops Wall Street expectations.
Getting there requires four things: Robotaxi miles must compound, FSD subscriptions must climb, Optimus must reach production, and heavy spending must lower costs. If that happens, view could shift quickly. Gains of this magnitude are rare in any single year, and the plan for oversized 2027 gains is outlined.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.